Silicon Sovereignty: Inside Anthropic’s High-Stakes Pivot to Custom AI Chipmaking
NEW YORK & SAN FRANCISCO — Driven by crushing infrastructure costs and a desperate bid to escape Nvidia’s pricing monopoly, artificial intelligence pioneer Anthropic has initiated an aggressive blueprint to design and deploy proprietary AI accelerators, reshaping the enterprise computing landscape forever.
Executive Takeaways
- The Cost Barrier: With Nvidia’s next-generation server racks commanding astronomical price tags, foundation model developers like Anthropic face severe margin compression that threatens long-term enterprise scalability.
- The Silicon Exodus: Anthropic joins a growing cohort of hyperscalers and elite labs—including OpenAI, Meta, Google, and Amazon—shifting capital allocation toward custom ASIC and accelerator development for risk mitigation.
- Ecosystem Disruption: While custom silicon promises superior enterprise ROI and reduced reliance on external supply chains, the immense capital requirements and fabrication bottlenecks introduce fresh financial and operational vulnerabilities.
The economic architecture of the generative AI boom is undergoing a tectonic realignment. For the past four years, the race to build artificial general intelligence has operated on a simple, punishing rule: he who commands the most Nvidia silicon wins. But as model parameters scale into the trillions and enterprise deployment accelerates, the sheer financial velocity of compute procurement has reached a breaking point. Enter Anthropic, the high-flying foundation model lab backed by billions from tech titans like Amazon and Google, which has formally signaled its intent to join the ranks of custom AI chipmakers.
This investigative report breaks down the catalytic market pressures forcing Anthropic’s hand, evaluates the capital allocation and infrastructure scalability challenges of custom silicon design, and analyzes what this vertical integration means for Nvidia's hardware hegemony and the broader global technology markets.
The Catalyst: When Next-Gen Server Racks Break the Balance Sheet
To understand why a software-centric research organization like Anthropic is pivoting toward hardware manufacturing, one must examine the soaring cost of modern AI infrastructure. Nvidia’s flagship server racks no longer represent standard enterprise IT capital expenditures; they are multi-million-dollar luxury assets whose price tags escalate with every subsequent architecture generation. For companies whose primary product is intelligence—specifically, the Claude model ecosystem—compute is the single largest line item on the income statement.
As venture capital funding normalizes and enterprise clients demand strict proof of enterprise ROI before deploying custom LLM workflows, foundational labs are experiencing severe margin compression. Relying entirely off-the-shelf accelerators leaves developers vulnerable to supply chain shocks, allocation politics, and exorbitant hardware markups. By designing bespoke silicon optimized specifically for transformer architectures, reinforcement learning from human feedback (RLHF), and inference execution, Anthropic aims to slash operational costs per token.
Industry insiders note that this move is less about competing directly with Nvidia’s general-purpose graphics processing units (GPUs) across every vertical and more about achieving compute self-sufficiency. Controlling the silicon stack allows frontier labs to optimize cloud compute architecture down to the bare metal, unlocking efficiency gains that off-the-shelf components simply cannot match.
The Race for Vertical Integration: A crowded Field

Anthropic is far from a trailblazer in this specific descent into hardware. The realization that custom silicon is a prerequisite for long-term economic viability has triggered a gold rush across the entire technology sector. Google pioneered this path years ago with its Tensor Processing Units (TPUs), insulating itself partially from external supply shocks. Amazon Web Services, a primary financial and cloud backer of Anthropic, has pushed forward with its Trainium and Inferentia chips. Meanwhile, Meta Platforms and Microsoft have each poured billions into proprietary silicon initiatives.
Even rival foundation model titan OpenAI has spent the past year evaluating foundry partnerships, strategic acquisitions, and direct semiconductor design hires to build its own hardware pipeline. For Anthropic, staying competitive requires matching this strategic vertical integration. Without custom hardware, a model maker remains perpetually tethered to the profit margins and production timelines of third-party chip suppliers.
| Entity | Primary Hardware Strategy | Key Foundry Partner | Primary Objective |
|---|---|---|---|
| Anthropic | Proprietary AI Accelerators (Inference & Training) | Undisclosed / Evaluating TSMC | Margin protection, compute scalability, reduced Nvidia dependency |
| OpenAI | Custom ASIC Design & Foundry Partnerships | Broadcom / TSMC (Reported) | Securing dedicated wafer allocation, lowering inference costs |
| Mature TPU Ecosystem (v5p / v6) | In-house / TSMC | Vertical software-hardware co-design optimization | |
| Meta Platforms | MTIA (Meta Training and Inference Accelerator) | TSMC | Internal recommendation engine and generative AI scaling |
Financial Mechanics: Capital Allocation and Valuation Multiples
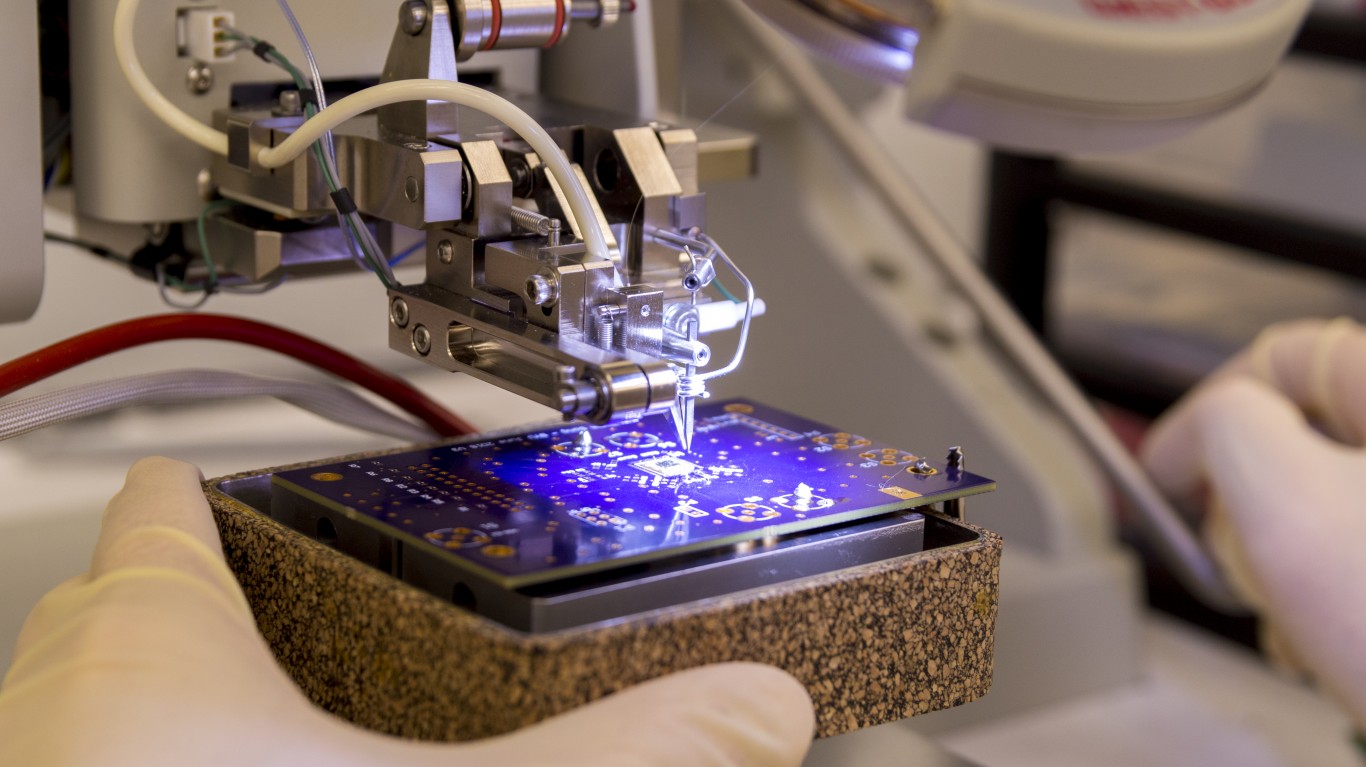
Transitioning from software and algorithmic research to semiconductor manufacturing requires an extraordinary shift in capital allocation. Designing a competitive AI chip at cutting-edge nodes (such as 3-nanometer or 2-nanometer processes) demands hundreds of millions of dollars in upfront research and development, tape-out costs, and sophisticated engineering talent acquisition. Furthermore, securing manufacturing capacity at premier foundries like Taiwan Semiconductor Manufacturing Company (TSMC) involves fierce competition and massive capital outlays.
For private market investors evaluating Anthropic’s valuation multiples, this pivot introduces a complex risk-reward matrix. On one hand, successful custom silicon deployment drastically lowers gross margin hurdles, making the business model infinitely more sustainable at enterprise scale. On the other hand, hardware development is notoriously unforgiving. A single flawed architectural tape-out can result in hundreds of millions of wasted capital and months of delayed deployment schedules.
Risk mitigation, therefore, becomes paramount. Anthropic is likely to leverage strategic partnerships with cloud hyperscalers—particularly Amazon and Google—to co-fund and co-develop these semiconductor initiatives, sharing both the exorbitant capital expenditure burdens and the eventual efficiency dividends.
Industry & Market Implications: Who Wins and Who Loses?
The ripple effects of Anthropic’s chipmaking ambitions will be felt across global financial markets, technology supply chains, and enterprise boardrooms:
- The Winners: Semiconductor IP providers, electronic design automation (EDA) software giants (such as Synopsys and Cadence), and advanced packaging foundries stand to benefit immensely as every major AI player builds internal design teams. Specialized engineering talent will also command unprecedented compensation packages.
- The Vulnerable: While Nvidia’s near-term dominance remains secure due to the unmatched software lock-in of its CUDA ecosystem, the steady migration of hyperscalers and elite labs toward custom silicon represents a long-term erosion of its addressable market for high-margin enterprise sales.
- Enterprise Buyers: Corporate consumers of AI stand to benefit from eventual price deflation. As custom silicon drives down the baseline cost of running advanced intelligence, enterprise software vendors will be able to offer more competitive pricing, driving broader software adoption and accelerating genuine enterprise ROI.
Frequently Asked Questions (People Also Ask)
Why is Anthropic shifting toward custom AI chip development?
Anthropic is pursuing custom silicon to mitigate escalating hardware costs, reduce heavy reliance on dominant suppliers like Nvidia, and improve operational margins. As model sizes expand, proprietary chips allow companies to optimize compute efficiency and secure dedicated hardware supply chains.
How does custom silicon impact enterprise AI adoption and ROI?
By lowering the underlying cost of compute and inference, custom chips make deploying large language models more financially viable for corporate buyers. This reduction in operating expenditures directly accelerates enterprise ROI, encouraging wider software integration across industries.
What are the primary risks associated with AI labs designing their own chips?
Semiconductor design requires massive upfront capital allocation, specialized engineering expertise, and access to limited foundry capacity (such as TSMC). Risks include costly hardware design flaws, delayed tape-outs, and fierce competition for advanced manufacturing nodes.
Will custom chips completely replace Nvidia GPUs in the enterprise market?
Not immediately. While custom ASICs excel at specific, highly optimized workloads, Nvidia’s overarching CUDA software ecosystem and general-purpose flexibility ensure it will remain a dominant industry force for years, even as major labs diversify their infrastructure.
Future Outlook: Milestones to Watch
As Anthropic transitions from software pioneer to silicon architect, market analysts and investors must monitor several critical operational milestones over the next 12 to 24 months:
- Foundry and Partnership Announcements: Watch for formal joint ventures or foundry agreements with major semiconductor fabricators, which will signal the maturity and timeline of Anthropic’s hardware roadmap.
- First-Generation Tape-Outs: The successful completion and benchmark testing of initial proprietary silicon prototypes will prove whether the organization can execute effectively in the complex hardware arena.
- Cloud Infrastructure Integration: Evidence of custom chips being deployed successfully within partner cloud environments (such as AWS) to handle production-scale Claude inference workloads at reduced cost.
Ultimately, Anthropic’s foray into chipmaking underscores a definitive market truth: in the modern artificial intelligence economy, he who controls the silicon dictates the future of software. The battle for algorithmic brilliance has officially evolved into a war for industrial sovereignty.