

Executive Takeaways
- Macro Catalyst: Recent Democratic legislative and gubernatorial wins have triggered a profound reprisal across global equity markets, directly threatening the unprecedented capital allocation directed toward artificial intelligence infrastructure.
- Valuation Multiples Under Siege: High-flying tech darlings and semiconductor giants face severe compression as investors recalculate enterprise ROI amid looming risks of heightened antitrust scrutiny, stricter export controls, and aggressive tax reform.
- Compute Architecture Bottlenecks: Wall Street analysts warn that any shift in federal policy could restrict data center energy access, disrupt power purchase agreements (PPAs), and severely constrain cloud compute scalability.
- Strategic Portfolio Pivot: Institutional asset managers are rapidly executing risk mitigation strategies, rotating out of momentum-driven AI hardware plays and into defensive, cash-generative value equities.
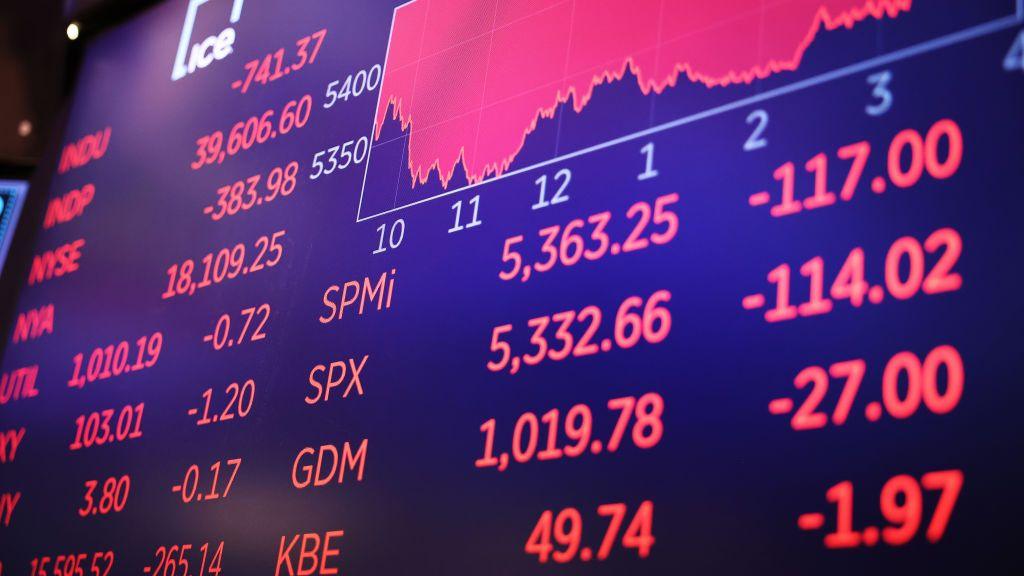
NEW YORK, LONDON, TOKYO — In a jarring reminder of how tightly intertwined modern monetary momentum is with political outcomes, global stock indices slumped sharply in early trading today. The immediate catalyst: a cascade of decisive Democratic electoral victories that have fundamentally altered the legislative calculus in Washington. For months, Wall Street’s consensus trade rested on an assumption of regulatory laissez-faire, boundless energy subsidies for hyperscalers, and uninterrupted capital expenditure cycles. Today, that thesis collided with the reality of shifting political power, triggering a broad-based liquidation across semiconductor fabrication, cloud infrastructure, and large-language-model (LLM) developer ecosystems.
The contagion spread rapidly from Wall Street to European bourses and Asian tech hubs. Futures on the Nasdaq 100 plunged, dragging down bellwether semiconductor manufacturers in Taiwan, South Korea, and the Netherlands. Market liquidity evaporated in key tech-heavy sectors as algorithmic execution desks and quantitative funds aggressively unwound leveraged long positions. The central anxiety driving this sell-off is not merely cyclical; it strikes at the structural heart of the artificial intelligence boom: the assumption of limitless, low-friction corporate growth fueled by unfettered access to capital markets, cheap power, and minimal regulatory oversight.
The Regulatory Reckoning: Antitrust, Compliance, and the AI Oligopoly
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the depth of today's market rout, one must examine the unprecedented nature of the current artificial intelligence buildout. Over the past twenty-four months, hyper-scale cloud providers—including Microsoft, Amazon, Google, and Meta—have committed hundreds of billions of dollars to capital expenditure projects. This colossal outlay has been dedicated to procuring specialized graphics processing units (GPUs), constructing liquid-cooled data centers, and locking down multi-gigawatt energy supplies. Investors priced these expenditures as growth catalysts, assuming that market dominance by a handful of tech behemoths would remain unhindered by federal oversight.
However, the consolidation of political power by the Democratic party signals an emboldened regulatory apparatus. Under the leadership of aggressive antitrust regulators at the Federal Trade Commission (FTC) and the Department of Justice (DOJ), scrutiny over cloud-AI tie-ups, exclusive model-licensing agreements, and acqui-hiring practices is expected to intensify exponentially. For institutional investors, this introduces a severe compliance discount into forward-looking valuation models.
Furthermore, legislative proposals centered on data privacy, algorithmic accountability, and mandatory model safety audits are no longer viewed as distant theoretical risks. A more progressive or interventionist legislative branch possesses the tools to impose stringent regulatory compliance costs on foundation model developers. These compliance burdens directly erode profit margins, pushing out the timeline for sustainable enterprise ROI and forcing venture capital and private equity firms to re-evaluate late-stage tech valuations.
Energy Infrastructure and the PPA Crunch
Beyond software and silicon, the AI boom's most acute vulnerability lies in physical infrastructure—specifically, power generation. Training and running advanced neural networks demand prodigious baseload electricity, leading tech giants to forge direct partnerships with nuclear and fossil-fuel power providers through complex Power Purchase Agreements (PPAs).
Democratic victories frequently align with aggressive decarbonization mandates and stricter environmental oversight. Wall Street is now pricing in the distinct possibility of regulatory hurdles facing data center developments that rely on carbon-intensive energy sources. If federal or state regulators restrict direct-connect nuclear or natural gas deals for hyperscale facilities, the physical scalability of cloud compute architecture faces an immediate bottleneck.
Without guaranteed access to reliable, low-cost power, the projected exponential growth curves for generative AI inferencing begin to flatten. This physical reality check has forced equity analysts to slash long-term revenue projections for utility providers tied to the tech sector, creating a dual-engine sell-off that impacts both software innovators and traditional energy suppliers.
Global Market Metrics & Equity Impact Analysis
| Asset Class / Sector | Immediate Price Action | Primary Risk Vector | Valuation Multiples Impact |
|---|---|---|---|
| Semiconductor & Hardware | -4.8% to -7.2% | Export controls, capex cuts by hyperscalers, supply chain friction. | Compression from 35x to 24x Forward P/E |
| Hyperscale Cloud Providers | -3.1% to -5.5% | Antitrust litigation, data privacy laws, high compliance overhead. | Multiple contraction across core cloud segments |
| Clean Energy & Nuclear PPAs | Mixed / Volatile | Interconnection queue delays, shifting green subsidy allocations. | Neutralized speculative premium |
| Defensive Value Equities | +1.2% to +2.5% | Capital flight from high-beta growth stocks into safe havens. | Stable earnings-backed yields |
Institutional Strategy: Navigating the Risk Mitigation Paradigm
Chief Investment Officers across major asset management firms are moving swiftly to adjust portfolio allocations. The consensus view emerging from trading desks in Mayfair and Wall Street is that the era of blind, momentum-driven buying in artificial intelligence has ended. Moving forward, portfolio managers are demanding tangible proof of enterprise monetization before allocating fresh capital to AI-focused initiatives.
Risk mitigation protocols now involve reducing exposure to high-beta semiconductor manufacturers whose revenue concentration is heavily dependent on the top four U.S. technology conglomerates. In their place, institutional capital is flowing into defensive sectors, dividend-paying industrials, and companies with robust balance sheets insulated from regulatory headwinds. This rotation reflects a broader macroeconomic reality: as political risk rises, the cost of capital increases, penalizing long-duration, high-growth cash flows that lie far out in the future.
Frequently Asked Questions (People Also Ask)
Why are Democratic electoral wins impacting global artificial intelligence stocks?
Democratic victories typically signal a higher likelihood of aggressive antitrust enforcement, stricter data privacy regulations, and potential corporate tax hikes. Investors fear these policy shifts will constrain the massive capital expenditures currently driving the AI infrastructure boom, reducing profit margins and slowing enterprise scalability for tech giants.
How do regulatory changes affect data center energy access and power purchase agreements?
Artificial intelligence data centers require immense amounts of electricity. Progressive policy frameworks often emphasize stringent environmental standards and grid decarbonization. If regulators restrict direct power purchase agreements between tech companies and fossil-fuel or nuclear energy providers, data center expansion faces severe physical bottlenecks.
Are semiconductor manufacturers facing structural headwinds or short-term volatility?
While the long-term secular demand for compute power remains robust, semiconductor manufacturers face immediate valuation compression. If cloud providers trim their capital expenditure budgets in response to regulatory pressures and uncertain enterprise ROI, chipmakers will experience order cancellations and inventory corrections.
What strategies are institutional investors using for risk mitigation during this market slide?
Portfolio managers are executing tactical rotations out of high-beta tech growth stocks and into cash-generative, defensive value equities. They are also demanding verifiable proof of enterprise monetization for AI projects before committing new capital to infrastructure-heavy assets.
Future Outlook: Key Milestones and Market Watchpoints
Looking ahead, the trajectory of global equities will depend heavily on upcoming legislative maneuvers in Washington and corporate earnings guidance reports. Market participants will scrutinize upcoming fiscal quarter disclosures from major cloud hyperscalers to determine whether capital expenditure budgets are being reined in or maintained.
Furthermore, any movement on antitrust legislation or AI safety bills will serve as an immediate stress test for market sentiment. While the foundational transformation driven by artificial intelligence remains intact, the financial mechanisms supporting its growth are entering a more mature, highly regulated phase. Investors must navigate a landscape where political realities carry as much weight as technological breakthroughs, ensuring that valuation models accurately reflect the true cost of regulatory compliance and capital allocation.


