Executive Takeaways
- Commercialization Timeline: BYD has officially slated its proprietary solid-state battery technology for commercial deployment by 2027, compressing industry timelines by years.
- Capital Allocation & Infrastructure Scalability: The Shenzhen-based titan is reallocating tens of billions in capital expenditures toward giga-scale solid-state manufacturing, challenging Western and Japanese incumbents.
- Valuation Multiples & Market Disruption: This technological leap threatens to compress the valuation multiples of legacy ICE automakers and rival EV manufacturers lacking post-lithium-ion roadmaps.
- Supply Chain Risk Mitigation: The shift away from liquid organic electrolytes dramatically reduces thermal runaway risks, alters raw material dependencies, and redefines global supply chain security.
SHENZHEN & LONDON — In the high-stakes theater of global energy transition, few announcements carry the seismic weight of BYD’s latest strategic disclosure. According to industry intelligence first surfaced by Driven Car Guide on February 17, 2025, Chinese electric vehicle hegemony BYD is aggressively accelerating its R&D roadmap to launch commercial solid-state batteries by 2027. For institutional investors, risk analysts, and automotive executives, this is not merely an incremental product update; it is a watershed moment that threatens to upend the competitive moats of global manufacturing, rewrite enterprise ROI models across the mobility sector, and force an immediate recalculation of capital allocation strategies worldwide.
For years, Wall Street and Frankfurt analysts have debated the commercial viability of solid-state architecture—often dubbed the "Holy Grail" of electrochemical energy storage. While legacy players like Toyota, Mercedes-Benz, and a cohort of well-funded Silicon Valley startups have circled the technology with cautious optimism, scaling production past the laboratory threshold has remained an elusive financial and engineering nightmare. BYD’s commitment to a 2027 commercial window signals a profound shift. Backed by unrivaled vertical integration, deep-pocketed cash flows, and aggressive state-backed industrial policy, the world’s largest plug-in vehicle manufacturer is signaling that the era of liquid-electrolyte lithium-ion dominance is entering its twilight years.
The Catalytic Shift: Moving Beyond Liquid Electrolytes
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
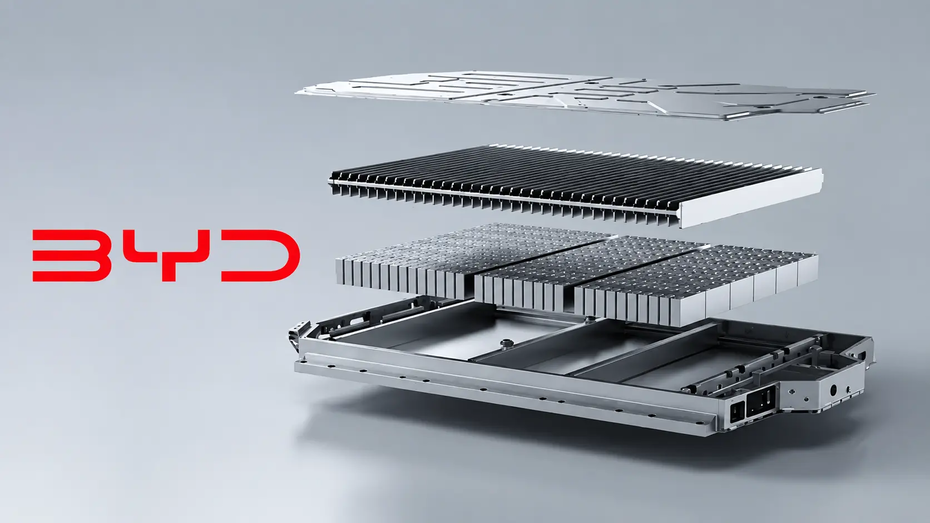
To understand the profound market liquidity and valuation implications of BYD’s 2027 timeline, one must examine the fundamental limitations of current lithium-ion technology. Traditional EV batteries utilize liquid organic solvents to facilitate the movement of lithium ions between the anode and cathode. While effective, these systems present persistent vulnerabilities: thermal instability under high-stress charging cycles, volumetric swelling, and inherent energy density ceilings that cap driving ranges.
Solid-state batteries replace this volatile liquid medium with a solid electrolyte—typically ceramic, sulfide, or polymer-based. The engineering advantages are transformative. By eliminating flammable liquid components, automakers achieve near-total risk mitigation against thermal runaway, the primary catalyst for catastrophic EV fires. Furthermore, solid-state cells allow for the direct use of lithium-metal anodes, drastically increasing volumetric and gravimetric energy density.
For BYD, the 2027 launch represents the culmination of a multi-year, multi-billion-dollar R&D blitz executed through its battery subsidiary, FinDreams Battery. While competitors have struggled with interfacial resistance—the degradation that occurs when solid electrolytes react poorly with electrodes—BYD’s proprietary material science breakthroughs appear to have cracked the code for high-yield, low-cost mass production. This breakthrough promises to deliver vehicles capable of exceeding 1,000 kilometers (620 miles) of range on a single charge while cutting standard DC fast-charging times in half.
Comparative Industry Landscape: BYD vs. Global Incumbents
The announcement immediately intensifies the global race for solid-state supremacy. While Toyota has heavily publicized its own solid-state roadmap—bolstered by recent investments in dedicated electrolyte manufacturing facilities—its commercialization targets have frequently slipped, with early low-volume rollouts anticipated late in the decade. Similarly, European stalwarts like Mercedes-Benz are navigating complex joint-venture frameworks and rigorous regulatory compliance hurdles that often slow capital deployment.
BYD’s structural advantage lies in its peerless industrial ecosystem. By controlling everything from raw lithium refining to semiconductor fabrication and final vehicle assembly, BYD bypasses the supply chain bottlenecks that plague Western competitors. This operational agility ensures that when the 2027 commercial window opens, BYD can achieve infrastructure scalability at a cost per kilowatt-hour that legacy automakers will struggle to match.
| Automaker / Entity | Target Commercialization Year | Primary Electrolyte Focus | Strategic Advantage |
|---|---|---|---|
| BYD | 2027 | Proprietary Sulfide/Oxide Blend | Vertical integration, giga-scale manufacturing, cost control. |
| Toyota | 2027 - 2030 (Staged) | Sulfide-based | Vast patent portfolio, rigorous durability testing. |
| Mercedes-Benz | Late 2020s / 2030 | Solid-state polymer partnerships | Luxury market positioning, high safety tolerances. |
| Solid Power / BMW | 2028+ | Sulfide-based solid electrolyte | Specialized IP development, joint-venture validation. |
Economic Fallout: Market Liquidity, Valuation Multiples, and Geopolitical Pressures
The financial ramifications of BYD’s 2027 timeline extend far beyond the automotive sector, directly impacting global capital markets and commodity trading desks.
1. Compression of Legacy Valuation Multiples
Traditional internal combustion engine (ICE) manufacturers and EV startups that rely on outsourced battery supply chains face severe margin compression. As BYD introduces superior energy density and safety profiles at a competitive price point, consumer preference will pivot sharply. Institutional investors are already beginning to re-price equity valuations, penalizing legacy firms that fail to demonstrate a credible post-lithium-ion product pipeline.
2. Geopolitical and Regulatory Compliance Dynamics
BYD’s technological leap arrives amidst escalating trade tensions, particularly in North America and the European Union, where protective tariffs and regulatory frameworks aim to stymie the influx of low-cost Chinese EVs. However, a technological monopoly on solid-state batteries complicates Western protectionist strategies. If BYD’s solid-state chemistry offers an undeniably superior product—redefining safety and performance standards—global automakers may find themselves structurally compelled to license Chinese intellectual property or risk irrelevance.
Frequently Asked Questions (People Also Ask)
What makes BYD’s 2027 solid-state battery timeline significant compared to competitors?
BYD combines aggressive R&D execution with unmatched vertical integration and manufacturing scale. While many western and Japanese automakers have projected solid-state rollouts for late in the decade or the early 2030s, BYD's established giga-factory infrastructure allows it to transition from lab-scale innovation to mass commercialization significantly faster and at a lower cost per kilowatt-hour.
How do solid-state batteries alter EV safety and performance metrics?
Solid-state batteries replace volatile liquid organic electrolytes with stable solid materials. This eliminates the risk of thermal runaway and fires. Mechanically, they allow for lithium-metal anodes, which dramatically increase energy density—delivering longer driving ranges (often exceeding 1,000 km), faster charging speeds, and superior cold-weather performance.
What are the primary economic risks for legacy automakers following this announcement?
Legacy automakers face immediate valuation multiple contractions and severe margin pressure. Companies relying on traditional liquid lithium-ion technology risk swift consumer obsolescence once vehicles equipped with high-performance, ultra-safe solid-state batteries hit the market at competitive price points in 2027.
How will the raw material supply chain be impacted by the shift to solid-state chemistry?
The transition to solid-state batteries shifts raw material dependencies. While lithium remains a foundational component—often required in higher quantities per cell for lithium-metal anodes—the demand profile for specific liquid electrolyte solvents, separators, and containment architecture will evolve, forcing commodity markets and mining conglomerates to recalibrate capital expenditure allocations.
Future Outlook: Milestones and Strategic Imperatives to 2027
As the industry marches toward the 2027 commercialization window, stakeholders must monitor several critical operational milestones. First, watch for pilot-line yield rates and thermal stress test data released by FinDreams Battery. Achieving high-yield manufacturing without microscopic internal short-circuits remains the ultimate hurdle for solid-state adoption.
Second, observe how global trade regulators respond to this technological leap. As software-defined vehicles and next-generation energy storage converge, geopolitical friction will likely intensify around battery patents, trade tariffs, and cross-border data compliance. For enterprise executives, institutional investors, and sovereign wealth funds, the message is unequivocal: the post-lithium-ion future is no longer a theoretical horizon. It has a confirmed arrival date, and BYD is setting the clock.