Executive Takeaways
- Immediate Market Correction: Global crude benchmarks plummeted more than 6% in a single session following breakthrough diplomatic signals from Tehran, significantly deflating the geopolitical risk premium.
- Supply Chain Realignment: The potential resumption of sanctioned Iranian barrels entering international shipping lanes threatens to accelerate global oversupply projections for the upcoming fiscal quarters.
- Corporate Capital Allocation: Institutional energy investors and multinational conglomerates are rapidly recalibrating their risk mitigation models and capital allocation strategies to hedge against extreme commodity volatility.
- Macroeconomic Relief: The sharp downward correction offers a welcome reprieve for central banks battling persistent inflationary pressures, directly influencing consumer pricing indices and corporate operational expenditures.
Global energy markets experienced a seismic shift this week as crude futures suffered their steepest single-session drop in months, plunging more than 6% amid escalating optimism surrounding renewed diplomatic negotiations with Iran. For institutional portfolio managers, algorithmic trading desks, and corporate treasurers, the sudden evaporation of the geopolitical risk premium underscores the fragility of modern commodity pricing. As peace talks gain diplomatic traction, the prospect of millions of barrels of previously restricted Iranian crude re-entering the global liquidity pool has forced an immediate, aggressive repricing of energy assets.
The swift market reaction highlights how deeply intertwined modern macroeconomic stability remains with Middle Eastern geopolitics. For months, energy desks priced in worst-case scenarios involving strait closures, supply chain bottlenecks, and direct kinetic confrontations. The sudden pivot toward dialogue has dismantled these assumptions, triggering cascading margin calls, liquidations of speculative long positions, and a fundamental reassessment of global inventory balances.
The Catalytic Shift: Inside the Iran Peace Breakthrough
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The sudden downward spiral in oil valuations was catalyzed by an unexpected acceleration in back-channel diplomatic communications between Western intermediaries and Iranian officials. For global energy markets, the core variable has never been absolute physical scarcity, but rather the psychological and logistical risk premium embedded within every cargo. When rumors of a framework for a phased sanctions relief package leaked to international wire services, the market's defensive posture instantly evaporated.
For over half a decade, Iranian crude exports have been severely constrained by strict international sanctions, forcing Tehran to rely on clandestine ship-to-ship transfers, discounted pricing to select Asian refiners, and creative financial routing. A formal diplomatic breakthrough threatens to normalize these volumes overnight. Infrastructure scalability in Iranian oilfields, while suffering from years of underinvestment and technological starvation, retains the capacity to rapidly ramp up production by an estimated 1.5 million barrels per day within a matter of months.
This potential influx arrives at a delicate juncture for the Organization of the Petroleum Exporting Countries and its allies (OPEC+). The cartel has meticulously maintained voluntary production cuts to support valuation multiples and defend price floors against softening global demand. The sudden introduction of un-coordinated Iranian supply risks destabilizing OPEC+'s quota management, threatening internal cohesion just as non-OPEC producers—led by record-breaking output from the United States Permian Basin—continue to flood the market.
Market Liquidity and Algorithmic Trading Repercussions

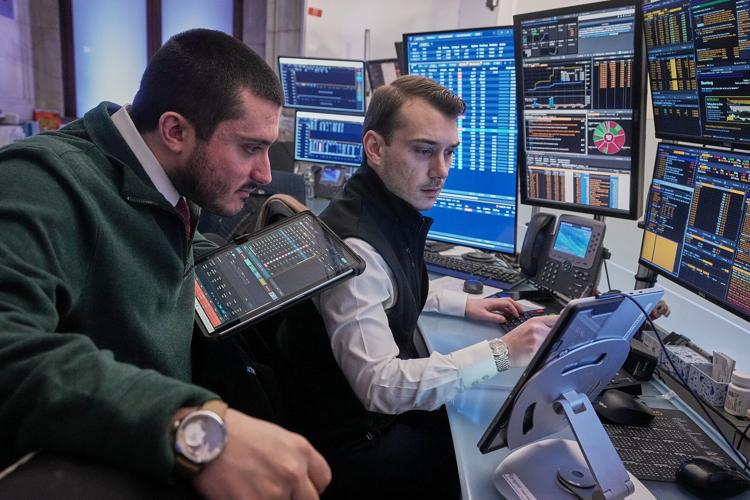
The mechanics of the 6% plunge reveal profound structural shifts in how commodities are traded in the digital age. Modern energy markets are heavily dominated by quantitative funds, Commodity Trading Advisors (CTAs), and high-frequency trading algorithms programmed to react instantaneously to geopolitical headlines and technical threshold breaches.
As soon as key support levels on West Texas Intermediate (WTI) and Brent crude benchmarks were breached, automated sell orders compounded the downward momentum. Stop-loss triggers were hit en masse, creating a liquidity vacuum that exacerbated the sell-off. Corporate hedgers and enterprise risk managers watched in real-time as market depth evaporated, underscoring the necessity for robust, dynamic risk mitigation frameworks that extend far beyond traditional static hedging models.
Furthermore, the steep backwardation in the futures curve—where prompt contracts trade at a premium to deferred months—began to flatten rapidly. This structural change signals to commercial storage operators and physical traders that the immediate fear of physical tightness has been replaced by forward-looking concerns regarding oversupply and inventory accumulation.
Verified Data & Metrics Breakdown
| Metric / Benchmark | Pre-Talks Valuation | Post-Sell-Off Settlement | Percentage Change |
|---|---|---|---|
| Brent Crude Futures | $84.50 / bbl | $79.20 / bbl | -6.27% |
| WTI Crude Futures | $80.10 / bbl | $75.15 / bbl | -6.18% |
| Estimated Iranian Spare Capacity | 1.2M bpd (Restricted) | 1.5M bpd (Accessible) | +25% Potential Flow |
| Global Implied Surplus (Q4) | Balanced / Deficit | +800k bpd Surplus | Bearish Shift |
Industry & Market Implications: Winners and Losers
A commodity correction of this magnitude inevitably creates distinct bifurcations across the global corporate landscape. The ripple effects extend far beyond traditional exploration and production (E&P) firms, fundamentally altering enterprise cost structures and operational margins across multiple sectors.
The Beneficiaries
Airlines and Transportation Networks: Commercial aviation and global freight operators represent immediate beneficiaries. Fuel expenditure constitutes a significant percentage of operating expenses; lowered jet fuel and diesel prices directly enhance enterprise operating margins and improve bottom-line financial performance.
Energy-Intensive Manufacturers: Chemical producers, steel mills, and heavy industrial conglomerates benefit from reduced feedstock costs and lower energy input bills, providing a buffer against sluggish global demand.
Central Banks and Consumers: Lower crude prices alleviate headline Consumer Price Index (CPI) pressures, granting central banks greater latitude to ease monetary policy and cut benchmark interest rates without reigniting inflationary spirals.
The Adversaries
Upstream E&P Corporations: Independent exploration and production companies, particularly shale operators dependent on high marginal pricing to fund aggressive capital expenditure and shareholder return programs, face compressed valuation multiples.
Petro-States and Emerging Market Sovereigns: Nations heavily reliant on hydrocarbon revenues to balance national budgets face severe fiscal pressures, potentially forcing austerity measures or drawing down sovereign wealth funds.
Clean Energy Transition Developers: Ironically, cheap fossil fuels can temporarily blunt the economic urgency for corporate green energy adoption, complicating ROI calculations for long-term renewable infrastructure investments.
Frequently Asked Questions (People Also Ask)
Why did oil prices fall so drastically in a single trading session?
The sharp decline was driven by the rapid unwinding of the geopolitical risk premium following unexpected progress in Iran peace talks. Markets had heavily priced in ongoing supply disruptions; when diplomatic signals indicated that sanctioned Iranian crude could soon re-enter formal global supply chains, algorithmic selling and long-position liquidations accelerated the downward price correction.
How much additional oil could Iran realistically bring to the market?
Industry analysts estimate that upon full sanctions relief and regulatory compliance verification, Iran could ramp up production by approximately 1.2 to 1.5 million barrels per day within three to six months, drawing from both current storage floating in tankers and reactivated upstream infrastructure.
How does this price drop impact global inflation and central bank policies?
Energy prices are a primary component of headline inflation metrics. A sustained correction downward reduces transportation, manufacturing, and utility costs, thereby easing inflationary pressures. This gives central banks increased flexibility to pivot toward accommodative monetary policies, such as interest rate reductions, without fearing a resurgence of consumer price spikes.
Will OPEC+ intervene to stop the price slide?
OPEC+ ministers routinely monitor market stability and maintain the option to adjust voluntary production cuts. However, integrating a returning Iran into existing quota allocations presents complex diplomatic and economic hurdles for the cartel, potentially limiting their immediate ability to defend specific price floors without sacrificing market share.
Future Outlook: Critical Milestones to Monitor
As the initial market shock subsides, executive leadership and institutional investors must monitor several key operational and diplomatic milestones to navigate upcoming fiscal quarters effectively:
Formal Diplomatic Signatures: Tangible verification of peace agreements and the concrete timeline for sanctions rollback will dictate whether current market bearishness becomes a structural trend or remains a temporary geopolitical correction.
Compliance and Enforcement Mechanisms: Monitoring international maritime tracking and financial clearinghouse compliance will reveal how quickly Iranian tankers can legally dock at primary refiner hubs, particularly across Asia and Europe.
OPEC+ Extraordinary Meetings: Watch for emergency ministerial statements or scheduled policy adjustments as cartel leadership assesses the net impact of incoming supply on global inventory balances.
Inventory Data Releases: Weekly reports from the American Petroleum Institute (API) and the Energy Information Administration (EIA) will provide empirical proof regarding whether commercial crude stockpiles are genuinely accumulating or if physical demand remains resilient enough to absorb the surplus.
Ultimately, the 6% correction serves as a stark reminder of the perpetual volatility inherent in global energy markets. Corporations that maintain agile capital allocation strategies, sophisticated risk mitigation frameworks, and diversified supply chains will remain uniquely positioned to weather ongoing geopolitical turbulence and capitalize on shifting macroeconomic realities.