Executive Takeaways
- Broad-Based Capitulation: Wall Street suffered its most severe intraday retreat since June, driven by mounting institutional skepticism over enterprise ROI and infrastructure scalability within the artificial intelligence sector.
- Valuation Multiples Decompressed: Mega-cap technology stalwarts experienced aggressive capital reallocation as portfolio managers re-evaluated forward earnings projections against soaring capital expenditure requirements.
- Macroeconomic Crosswinds: The tech rout coincided with shifting fixed-income yields and tightening liquidity, forcing institutional investors into aggressive risk mitigation strategies across global equities.
NEW YORK — Wall Street’s prolonged love affair with artificial intelligence experienced a violent reality check on Friday, as a cascading sell-off in mega-cap technology equities dragged major U.S. indices toward their worst single-day performance since June. What began as localized profit-taking in high-flying semiconductor designers and cloud compute providers quickly metastasized into a broad-based liquidity event, laying bare institutional anxieties over the timeline of enterprise returns, soaring infrastructure costs, and stretched valuation multiples.
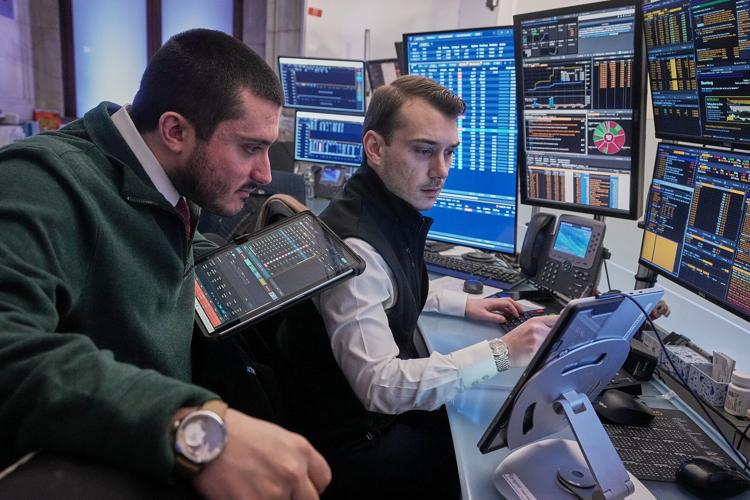
According to wire reports originating from New York and corroborated by trading desks across Lower Manhattan, the market’s sudden reversal highlights a growing divergence between the secular narrative of generative AI adoption and the immediate P&L pressures facing corporate buyers. As equity strategists reassess risk mitigation models, the fundamental question facing capital allocators is no longer whether artificial intelligence will reshape global commerce, but whether the staggering capital expenditure cycle currently underway can generate sufficient cash flow to justify current equity valuations.
The Catalyst: Dissecting the Anatomy of a Tech Correction
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The macroeconomic backdrop leading into Friday’s session was already charged with volatility. For months, equity markets traded on the assumption of immaculate disinflation and a seamless transition toward enterprise-wide AI deployment. However, recent corporate earnings reports and forward guidance from bellwether technology conglomerates revealed a more complex operational reality. Chief Financial Officers across the Fortune 500 are increasingly demanding concrete evidence of enterprise ROI before greenlighting multi-million-dollar cloud compute architectures.
This scrutiny has triggered a domino effect. Semiconductor manufacturers, long considered the undisputed toll-takers of the AI gold rush, faced severe selling pressure as institutional block trades overwhelmed order books. Concurrently, software-as-a-service (SaaS) providers and hyperscalers experienced aggressive multiple compression. Market participants noted a distinct shift in institutional behavior: rather than buying the dip, large asset managers utilized intraday rallies to reduce exposure, indicating a structural shift in portfolio risk appetite.
Capital Allocation and Infrastructure Scalability Realities
At the heart of Friday's sell-off lies a fundamental tension regarding capital allocation. Hyperscale cloud providers have pledged tens of billions of dollars toward next-generation data center buildouts, specialized silicon procurement, and energy grid integration. While these investments are necessary for long-term infrastructure scalability, they are exerting immediate pressure on free cash flow margins.
Wall Street's quantitative and fundamental analysts alike have begun questioning the payback period on these outlays. When interest rates remained near historic lows, equity markets were willing to discount cash flows well into the future. In the current monetary policy environment—characterized by higher-for-longer borrowing costs and stringent regulatory compliance frameworks—investors are demanding near-term earnings visibility. The inability of several mid-tier tech firms to articulate a clear path to monetization has transformed high-growth darlings into capital-efficiency liabilities.
Market Metrics and Performance Breakdown
The scale of Friday’s market action was reflected across multiple asset classes, with volatility indices surging as option market makers adjusted to heavy downside hedging activity.
| Index / Asset Class | Session Movement | Key Driver / Catalyst |
|---|---|---|
| NASDAQ Composite | Significant Intraday Drop | Heavy liquidation in semiconductor and mega-cap tech stocks. |
| S&P 500 Information Technology | Worst Session Since June | Multiple compression and reassessment of AI capital expenditure returns. |
| CBOE Volatility Index (VIX) | Sharp Upward Spike | Surging demand for downside put options and portfolio hedging. |
| U.S. Treasury Yields | Flight-to-Safety Bid | Capital rotation out of equities and into sovereign fixed-income assets. |
Industry & Market Implications: Winners and Losers
Market corrections of this magnitude invariably redistribute wealth and test institutional convictions. As speculative excess is flushed out of the technology sector, the bifurcation between fundamentally sound enterprises and pure-play momentum vehicles becomes starkly apparent.
Who Loses: Speculative Growth and Over-Leveraged Infrastructure
The primary casualties of Friday's rout are early-stage AI startups lacking proprietary data moats, software companies experiencing decelerating organic growth, and hardware suppliers heavily dependent on single-customer concentration. Companies that funded aggressive expansion via debt financing or highly dilutive equity offerings face an unforgiving market environment as borrowing costs remain elevated. Furthermore, portfolio managers who maintained concentrated, over-leveraged long positions in mega-cap technology are being forced into aggressive deleveraging to meet margin requirements.
Who Wins: Defensive Rotation and Cash-Rich Value Stocks
Conversely, capital fleeing the technology sector is finding refuge in defensive, cash-generative sectors. Traditional value plays—including healthcare, consumer staples, and regulated utilities—are experiencing renewed institutional interest. Furthermore, institutional investors are rewarding blue-chip corporations with fortress balance sheets, pristine credit ratings, and proven abilities to generate robust free cash flows independent of macroeconomic cyclicality.
Frequently Asked Questions (People Also Ask)
What caused the sudden deterioration in technology stock valuations?
The correction was triggered by a convergence of factors, notably growing investor skepticism regarding the short-term enterprise ROI of artificial intelligence investments. Coupled with soaring capital expenditure requirements for data center infrastructure and tighter overall market liquidity, institutional investors began aggressively re-evaluating forward earnings multiples.
How does this sell-off compare to previous market corrections in 2024?
While the broader equity market has experienced periodic pullbacks, Friday's session marked the most pronounced downward momentum since June. The depth of the sell-off was exacerbated by heavy unwinding in mega-cap semiconductor and cloud computing equities that previously served as the primary drivers of index gains.
Are fundamental macroeconomic conditions driving the tech rout?
Macroeconomic factors, including persistent debates over Federal Reserve interest rate trajectories and shifting fixed-income yields, provided a difficult backdrop. However, market analysts emphasize that this was primarily a sector-specific fundamental correction centered on corporate spending efficiency rather than a broad macroeconomic crisis.
What should institutional and retail investors monitor moving forward?
Key indicators to watch include upcoming corporate earnings calls for commentary on IT budgets, trends in enterprise cloud migration metrics, sovereign bond yield movements, and liquidity flows in options markets signaling stabilization or continued downside hedging.
Future Outlook: Navigating the Post-Euphoria Landscape
As Wall Street digests the implications of this steep correction, the equity market is entering a transitional phase. The era of frictionless, sentiment-driven rallies across the entire technology complex has yielded to a more discerning, fundamental-driven paradigm. Market participants will scrutinize upcoming quarterly earnings reports for granular evidence of operational efficiency and tangible revenue generation derived from artificial intelligence deployments.
For executive leadership teams, the mandate is clear: capital allocation strategies must prioritize sustainable business models over speculative market share accumulation. As volatility normalizes and institutional portfolios complete their rebalancing acts, surviving this stress test will depend heavily on balance sheet strength, pricing power, and verified technological integration. The long-term secular promise of artificial intelligence remains intact, but the market has officially entered an era where execution, cash flow conversion, and risk mitigation reign supreme.