Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Macro Capital Allocation Pivot: Billionaire hedge fund founders and private equity titans are recalibrating asset allocation models following an unexpected Democratic midterm sweep, bracing for potential shifts in tax policy, heightened regulatory enforcement, and altered treasury yield dynamics.
- Carried Interest and Tax Code Vulnerabilities: Top-tier private equity partners and asset managers are moving swiftly to execute liquidity events and dividend recapitalizations before potential legislative revisions to Section 1061 carried interest rules and corporate tax rate floors take effect.
- Sectoral Re-Hedging: Institutional order flow reflects a sharp rotation out of mega-cap technology M&A targets facing aggressive antitrust oversight toward renewable energy infrastructure, defense supply chains, and high-grade municipal tax-exempt debt.
- Regulatory Compliance and Execution Risk: C-suite executives report escalating equity risk premiums due to anticipated aggressive oversight from the Federal Trade Commission (FTC), Securities and Exchange Commission (SEC), and Consumer Financial Protection Bureau (CFPB).
The Wall Street Shockwave: Dissecting the Blue Wave Shift
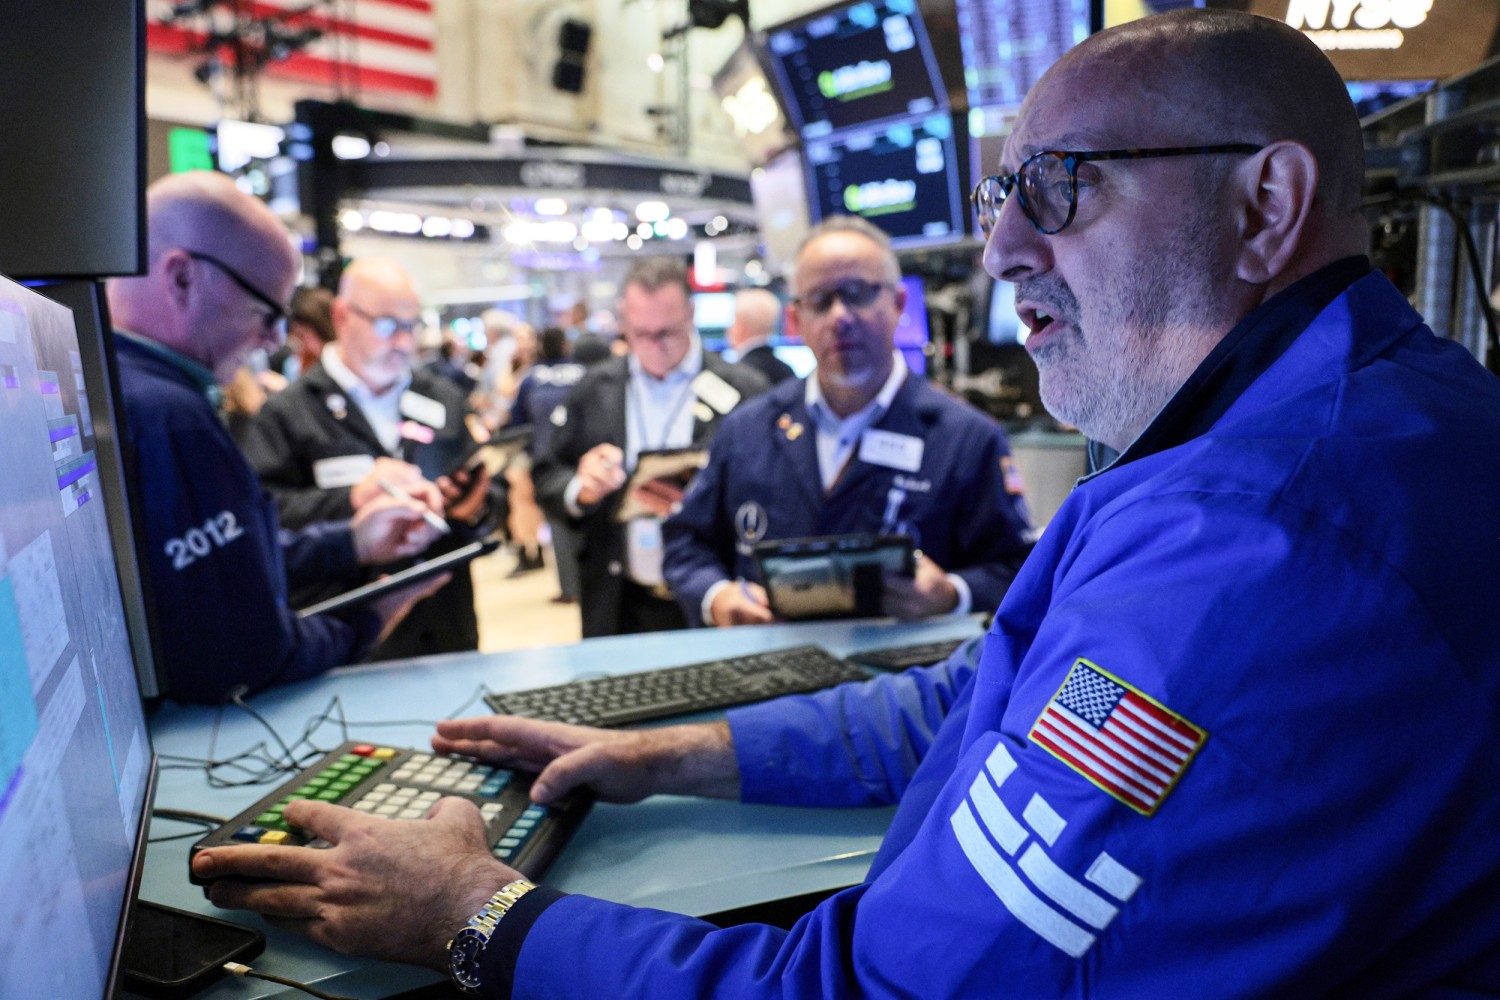
In the high-ceilinged conference rooms of Midtown Manhattan and the private family office enclaves of Palm Beach, financial leaders are coming to terms with a revised political reality. The Democrats' midterm electoral sweep—defying historical mid-term pushback patterns and consensus Wall Street polling models—has triggered an urgent re-evaluation of institutional portfolio positioning. For months, macro trading desks and quantitative strategy groups had priced in a divided government scenario: an operational environment characterized by legislative gridlock, predictable capital gains tax structures, and capped regulatory spending. That consensus model has now dissolved.
The immediate market reaction was registered not only across benchmark indices, but in the private communications of the world's most influential capital allocators. Citadel founder Ken Griffin, speaking at an invitation-only investor symposium in New York, noted that while market liquidity remains robust, the cost of regulatory compliance and legislative uncertainty will necessitate higher discount rates across long-duration asset classes. Meanwhile, JPMorgan Chase Chief Executive Jamie Dimon reiterated the absolute necessity of fiscal discipline, warning that expanded legislative mandates must not exacerbate underlying inflationary pressures or destabilize debt-issuance dynamics at the U.S. Treasury level.
The key point of friction for institutional investors lies in the structural shift of congressional power dynamics. With unified control of both legislative chambers, Democratic leadership gains the procedural leverage to advance revenue-raising measures through budgetary reconciliation—a mechanism requiring only a simple majority in the Senate. This dynamic fundamentally changes the valuation multiples assigned to heavily regulated industries, private partnership structures, and enterprise financial institutions across global markets.
The Billionaire Consensus: Tax Reform, Carried Interest, and Capital Allocation
At the center of Wall Street’s internal deliberation is the threat of sweeping tax reform. For decades, the financial industry has successfully defended the carried interest tax structure, which allows private equity, venture capital, and real estate fund managers to pay capital gains tax rates—typically lower than top-tier income tax brackets—on performance fees. In the wake of the electoral sweep, senior leadership at powerhouse firms including Blackstone, KKR, and Carlyle are accelerating strategic timelines.
According to managing directors familiar with internal portfolio strategies, mega-cap funds are prioritizing near-term exits, initial public offerings (IPOs), and dividend recapitalizations to unlock carried interest profits under current statutory frameworks. Pershing Square Capital Management founder Bill Ackman highlighted in an investor letter that capital allocators must prepare for a structurally higher effective tax environment, urging corporate boards to focus on organic enterprise return on investment (ROI) rather than financial engineering and levered share buyback programs.
Simultaneously, prominent macro investors such as Stanley Druckenmiller and Omega Advisors founder Leon Cooperman have voiced concerns over potential supply-side disruptions resulting from corporate tax rate adjustments. The focus centers on three major fiscal provisions under primary consideration by legislative committees:
- Revisions to Section 1061: Proposals to lengthen the holding period required for carried interest preferential tax treatment from three years to five years, or to eliminate the distinction entirely by treating performance fees as ordinary income.
- Corporate Alternative Minimum Tax (CAMT) Escalation: Potential adjustments to the 15% corporate minimum tax threshold, targeted at high-earning corporations that report significant book income while utilizing legal deductions to reduce taxable income.
- Excise Tax on Share Repurchases: A potential quadrupling of the 1% excise tax on corporate stock buybacks, designed to incentivize capital allocation toward domestic capital expenditures and research and development (R&D) over equity supply shrinkage.
These policy changes carry direct implications for asset valuation models. Quantitative analysts estimate that an elimination of preferential carried interest treatment, combined with heightened corporate minimum taxes, could lower net earnings expectations for listed alternative asset managers by 6% to 11% over the coming fiscal cycles.
Verified Data / Metrics Breakdown: Wall Street Capital Realignment Matrix
The following analysis outlines the shift in institutional strategy, policy-driven risk metrics, and capital allocation priorities across key financial market segments following the Democratic midterm victory.
| Asset Class / Sector | Pre-Sweep Consensus Exposure | Post-Sweep Allocation Shift | Primary Policy / Legislative Driver | 12-Month Projected Risk Profile |
|---|---|---|---|---|
| Private Equity & Venture Capital | Overweight (Aggressive Expansion) | Neutral / Defensive Realignment | Carried interest tax reform & Section 174 amortization | High: Exit valuations compressed; higher cost of leverage. |
| Mega-Cap Software & Tech | Overweight (Growth Dominance) | Underweight / Selective Hedging | FTC/DOJ antitrust oversight & M&A scrutiny | Moderate-High: Structural barriers to major bolt-on acquisitions. |
| Renewable Energy & Infrastructure | Neutral / Moderate Exposure | Aggressive Overweight | Expanded green subsidy frameworks & IRA protection | Low-Moderate: Strong secular tailwinds and direct federal support. |
| Traditional Energy & Midstream | Overweight (High Yield Focus) | Underweight / Capital Extraction | Federal leasing limits & windfall profit tax threats | High: Regulatory friction offset by global supply constraints. |
| Municipal Bonds (Tax-Exempt) | Neutral Exposure | Strong Overweight | Anticipated high-net-worth marginal tax bracket hikes | Low: Premium liquidity refuge for high-net-worth investors. |
Industry & Market Implications: Structural Winners, Losers, and Systemic Risk
The electoral outcome introduces a sharp bifurcated dynamic across equity and credit markets. Capital flows demonstrate that institutional money managers are actively rotating capital away from policy-vulnerable sectors into structural safe havens.
The Structural Winners
Renewable Energy and Clean Infrastructure: Under unified Democratic control, statutory funding mechanisms embedded in federal climate legislation remain insulated from rollbacks. Institutional allocators are directing capital toward utility-scale solar grid infrastructure, battery storage technology developers, and green hydrogen enterprises. Private credit funds are increasingly structuring bespoke debt instruments for infrastructure projects featuring predictable, long-term contracted cash flows.
Municipal Bond Debt Markets: With high-net-worth individuals facing potential surcharges on top-tier income brackets, demand for tax-exempt municipal bonds has surged. Yield curves in state and local government debt instruments have flattened dramatically as wealth management desks recommend municipal debt as an effective yield-preservation vehicle against rising marginal tax liabilities.
Healthcare and Domestic Pharmaceuticals (Select Sub-sectors): While prescription drug price negotiations introduce revenue caps for specialized pharmaceuticals, broader access to coverage mechanisms under expanded federal subsidies provides volume stability for high-throughput health services, managed care entities, and healthcare technology platform infrastructure.
The Structural Losers
Big Tech Mergers and Acquisitions: Under intensified scrutiny from federal regulatory authorities—backed by an aligned congressional mandate—mega-cap technology platforms face unprecedented roadblocks to inorganic expansion. Cross-border tech consolidation and multi-billion-dollar acqui-hire strategies will likely face elongated review periods, heightened antitrust litigations, and structural divestiture requirements.
Traditional Fossil Fuel Exploration: Upstream exploration and production (E&P) entities face heightened environmental compliance standards, increased royalty fees for federal land development, and restricted access to capital markets driven by institutional ESG (Environmental, Social, and Governance) compliance parameters.
Subprime Financial Services and High-LTV Lenders: The Consumer Financial Protection Bureau (CFPB) is expected to resume aggressive rule-making targeting late fees, short-term high-interest credit lines, and non-bank financial intermediaries. Equity risk premia for consumer finance platforms have expanded accordingly.
Frequently Asked Questions (People Also Ask)
How does a Democratic midterm sweep directly impact private equity funds?
A Democratic midterm sweep directly affects private equity through targeted tax legislation—specifically potential alterations to Section 1061 of the Internal Revenue Code, which governs carried interest tax rates. Additionally, higher proposed corporate income taxes and enhanced antitrust enforcement reduce exit multiples for portfolio companies and limit traditional M&A consolidation strategies, forcing funds to rely more heavily on operational improvement rather than debt leverage.
What actions are Wall Street billionaires taking to protect their capital?
Billionaire capital allocators are engaging in three main tactical plays: accelerating exit strategies and dividend recapitalizations ahead of tax code revisions; reallocating liquid funds toward tax-exempt municipal bonds and renewable energy assets backed by federal subsidies; and utilizing derivative overlay strategies to hedge against regulatory volatility in mega-cap tech and traditional energy holdings.
Will corporate tax rates increase immediately following the election sweep?
Tax code revisions require formal legislative drafting and must pass the congressional budget reconciliation process. While statutory changes rarely take effect retroactively, financial markets expect legislative packages to be introduced within the first two quarters of the legislative session, with corporate rate adjustments or alternative minimum tax enforcement taking full effect in the subsequent tax year.
Why are high-net-worth investors turning to municipal bonds after the midterm results?
High-net-worth investors utilize municipal bonds because the income generated from state and local municipal debt is generally exempt from federal income taxes, as well as state and local taxes in many jurisdictions. Anticipating potential increases in the top federal income tax bracket and net investment income tax (NIIT), investors bid up municipal bonds to lock in tax-advantaged yields.
Future Outlook: Strategic Milestones to Watch
As the new legislative session approaches, institutional markets will focus on several structural catalysts to gauge the speed and severity of regulatory changes. The initial critical landmark will be the assignment of key committee chairmanships—most notably the House Ways and Means Committee and the Senate Finance Committee—which will govern the path of upcoming tax policy overhauls.
Fund managers will also monitor Federal Reserve policy integration. If fiscal policy maintains an expansionary stance through direct federal investments, the Federal Reserve may be forced to maintain higher terminal benchmark interest rates to counteract underlying structural demand inflation. This high-rate environment, combined with strict corporate capital minimums, will continue to challenge asset managers operating under high leverage ratios.
Ultimately, Wall Street’s billionaire class is adjusting to a shifting economic regime. Financial success over the coming multi-year cycle will depend less on financial engineering and tax arbitrage, and more on rigorous fundamental capital allocation, regulatory risk mitigation, and operational excellence across resilient enterprise sectors.