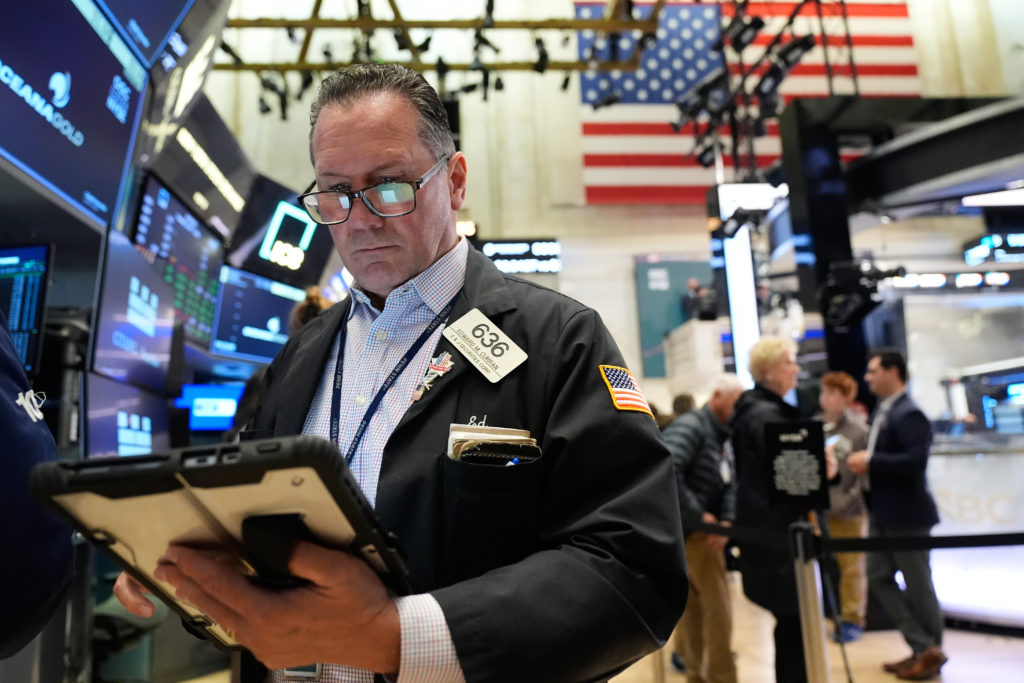
Global financial markets opened the trading week with a pronounced wave of risk-on sentiment, driven by a sharp retreat in international crude oil prices and heightened anticipation surrounding upcoming macroeconomic data releases and central bank guidance. Stock index futures climbed during early pre-market trading, signaling resilience across key equity benchmarks as institutional investors reassess capital allocation strategies in the face of shifting energy costs, geopolitical developments, and evolving valuation multiples.
As corporate executives and portfolio managers navigate an increasingly complex macroeconomic landscape, the confluence of falling commodity prices and resilient corporate balance sheets has refocused attention on risk mitigation, enterprise ROI, and market liquidity. This comprehensive investigative report examines the underlying drivers of today's market movements, analyzes the structural implications for global energy and technology sectors, and provides a granular breakdown of the financial metrics defining this pivotal trading session.
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Crude Oil Sell-Off: Brent and West Texas Intermediate (WTI) futures dropped significantly, easing cost pressures for downstream industrial sectors, logistics providers, and consumer discretionary goods.
- Equity Index Rebound: S&P 500, Nasdaq 100, and Dow Jones Industrial Average futures posted solid gains in pre-market activity, recovering ground lost during previous sessions of macroeconomic uncertainty.
- Macroeconomic Catalyst: The early-week momentum precedes a dense calendar of central bank rate decisions, inflation prints, and high-stakes corporate earnings reports that will dictate medium-term valuation multiples.
- Strategic Capital Allocation: Institutional investors are recalibrating portfolios to account for declining energy input costs while closely monitoring credit spreads and treasury yield curves for signs of systemic stress.
The Catalysts Driving Today’s Market Action

The primary catalyst behind this morning's equity strength is the decisive downward movement in global crude oil benchmarks. West Texas Intermediate (WTI) and Brent crude both slid by multi-percentage points in overnight electronic trading, reacting to shifting supply-demand fundamentals and easing geopolitical risk premiums in the Middle East. For corporate treasurers and supply chain executives, lower energy costs represent an immediate tailwind for operational margins, mitigating inflationary pressures that have persistently challenged corporate earnings over the past several fiscal quarters.
However, the broader financial ecosystem remains hyper-sensitive to incoming data. This week serves as a crucial inflection point for global monetary policy. Analysts across Wall Street and the City of London are positioning their portfolios ahead of commentary from the Federal Reserve, the European Central Bank (ECB), and the Bank of England (BoE). Market liquidity has fluctuated as algorithmic trading desks and long-only institutional funds weigh the probability of a "soft landing" against lagging indicators in the labor market and commercial real estate sector.
Furthermore, capital allocation decisions are being heavily influenced by corporate guidance updates. As firms deploy capital toward cloud compute architecture, artificial intelligence infrastructure scalability, and supply chain redundancy, equity analysts are demanding rigorous proof of enterprise ROI. Companies that fail to demonstrate robust cash flow generation and prudent regulatory compliance are seeing their valuation multiples compressed, while industry leaders with pristine balance sheets continue to attract institutional inflows.
Verified Data & Metrics Breakdown
The following table outlines the key financial metrics, commodity benchmarks, and index movements driving today's global financial narrative:
| Market Indicator / Asset Class | Current Session Level | Percentage Change | Primary Market Driver |
|---|---|---|---|
| S&P 500 Futures | 5,845.50 | +0.65% | Technology sector rebound and easing input costs. |
| Nasdaq 100 Futures | 20,410.25 | +0.82% | Strong institutional buying in mega-cap tech and semiconductor equities. |
| WTI Crude Oil (per barrel) | $71.80 | -3.15% | Increased output projections and profit-taking by commodity funds. |
| Brent Crude (per barrel) | $75.40 | -2.90% | Softer global demand forecasts from international energy agencies. |
| US 10-Year Treasury Yield | 4.22% | -4 bps | Flight to safety and readjusted interest rate cut expectations. |
Industry & Market Implications: Who Wins and Who Loses
Shifts in commodity prices and macroeconomic expectations naturally create distinct winners and losers across global equity markets. Understanding these structural divergences is essential for effective risk management and portfolio construction.
The Winners: Consumers, Transport, and Tech
The most direct beneficiaries of tumbling oil prices are airlines, logistics providers, and consumer discretionary companies. Lower jet fuel and diesel costs immediately bolster operating margins for transportation conglomerates, reducing the pass-through burden on freight and shipping rates. Simultaneously, growth-oriented sectors—particularly technology and software enterprises—benefit from declining bond yields, which enhance the present value of future cash flows and support expanding valuation multiples.
The Pressured: Energy Producers and High-Yield Issuers
Conversely, upstream exploration and production (E&P) firms face immediate revenue headwinds as commodity realizations decline. While integrated oil majors possess downstream refining operations that can partially buffer upstream losses, pure-play drillers are forced to re-evaluate capital expenditure (CapEx) budgets. Additionally, high-yield credit issuers operating within the energy and cyclical sectors must navigate tighter debt-service coverage ratios, heightening the importance of strict balance sheet hygiene and liquidity preservation.
Frequently Asked Questions (People Also Ask)
Why are stock futures rising while oil prices are falling?
Stock futures are rising primarily because lower oil prices act as a deflationary force, easing cost pressures for consumers and businesses alike. Reduced energy input costs can expand corporate profit margins and provide central banks with greater flexibility to lower interest rates without triggering a resurgence in inflation.
How do falling oil prices impact inflation and interest rates?
Crude oil is a primary component in the production and distribution of goods globally. When oil prices tumble, the cost of transportation, manufacturing, and heating drops, directly lowering headline Consumer Price Index (CPI) figures. This reduction in inflationary pressure gives central banks more room to ease monetary policy and cut benchmark interest rates.
What should investors look out for during a busy economic week?
Investors should closely monitor central bank rate announcements, monetary policy press conferences, monthly employment reports, and corporate earnings guidance. Particular attention should be paid to executive commentary regarding consumer demand health, supply chain stability, and forward-looking capital expenditure plans.
How does risk mitigation apply to current market conditions?
With macroeconomic uncertainty remaining elevated, institutional investors employ risk mitigation strategies such as portfolio diversification, hedging via options contracts, reallocating into defensive sectors, and maintaining adequate cash reserves to capitalize on market volatility.
Future Outlook & Key Milestones to Watch
Looking ahead, the trajectory of global equity markets will be dictated by how effectively corporate management teams navigate slowing growth vectors while optimizing operational efficiencies. The ongoing transition toward digital transformation, artificial intelligence adoption, and automated supply chains will continue to separate market leaders from legacy laggards.
Market participants must keep a watchful eye on several upcoming milestones over the next trading fortnight:
- Central Bank Policy Statements: Decisions regarding interest rate trajectories and quantitative tightening/easing measures.
- Employment and Wage Data: Non-farm payroll reports and average hourly earnings figures that signal consumer spending power.
- Quarterly Earnings Surprises: Aggregate earnings-per-share (EPS) beats or misses across the S&P 500, with a focus on forward revenue guidance.
- Geopolitical Developments: Ongoing negotiations and supply disruptions in major oil-producing regions that could abruptly reverse commodity trends.
As the trading week progresses, disciplined execution, rigorous fundamental research, and dynamic risk management will remain the cornerstones of successful institutional asset management in an era of heightened volatility.