Executive Takeaways
- The Paradigm Shift: Institutional capital allocation has definitively pivoted from foundational large language model (LLM) training to specialized vertical AI applications that target workflow friction, operational latency, and structural labor cost burdens.
- Margin Profiles & ROI: The most lucrative 2026 business models exhibit gross margin potential between 70% and 85%, underpinned by proprietary data architectures, fine-tuned Small Language Models (SLMs), and Retrieval-Augmented Generation (RAG) frameworks.
- Regulatory & Infrastructure Moats: Success in the 2026 venture landscape demands strict adherence to global regulatory compliance frameworks (such as the EU AI Act and SEC AI disclosure rules) combined with optimized cloud compute cost structures.
- Primary Value Drivers: B2B platforms offering measurable enterprise ROI—specifically in autonomous risk management, clinical workflows, supply chain orchestration, and legacy system refactoring—are securing top-tier valuation multiples.
Comprehensive Narrative: The Enterprise AI Realignment of 2026
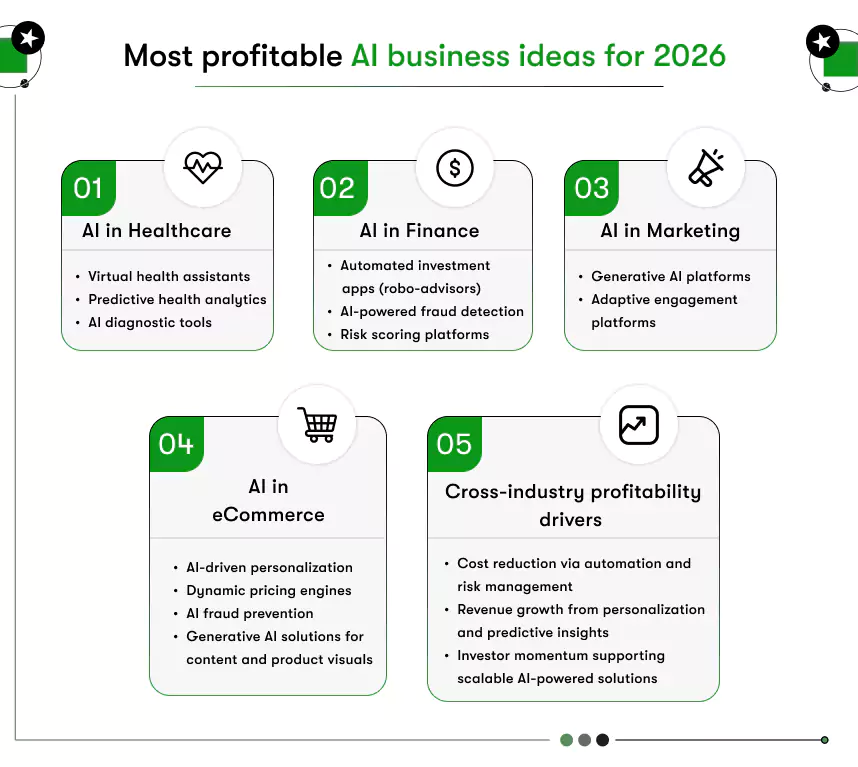
According to investigative wire reports confirmed by industry analysts at Appinventiv, the global enterprise artificial intelligence ecosystem has entered a mature, highly disciplined secondary growth phase. The speculative capital boom that characterized the initial generative AI surge has passed. In its place stands a pragmatic, cash-flow-conscious deployment cycle focused on unit economics, enterprise infrastructure integration, and clear capital allocation returns.
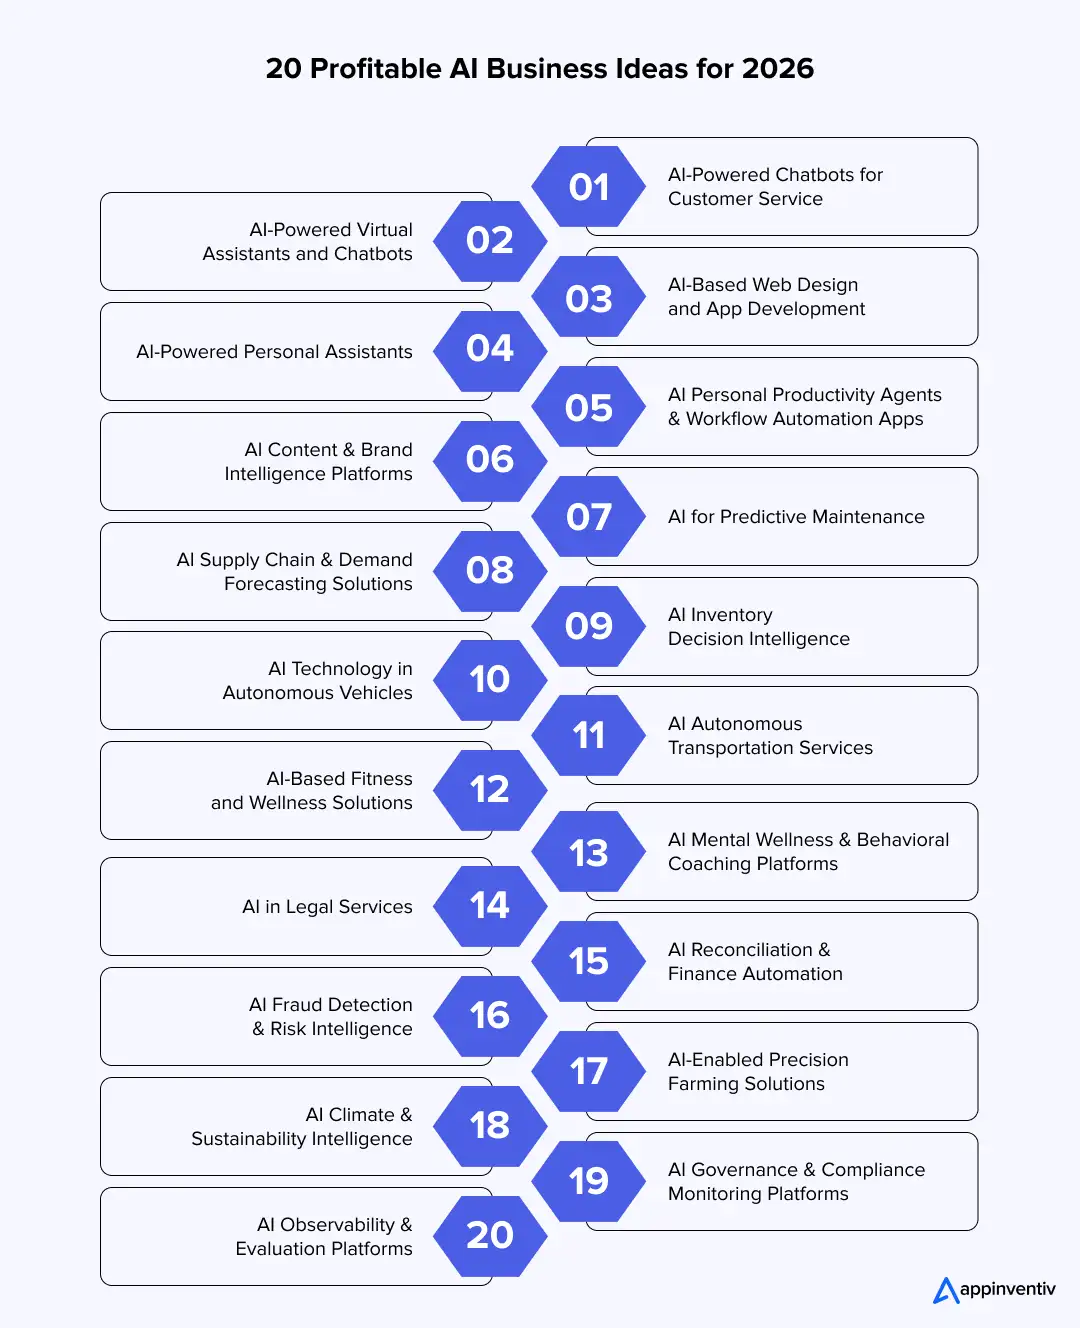
For corporate founders, private equity sponsors, and institutional venture partners, 2026 represents a critical inflection point. As inference costs continue to fall due to hardware innovation and smaller, domain-specific models, the arbitrage opportunity lies in converting raw algorithmic power into specialized, vertical-specific software solutions. Below is an exhaustive strategic breakdown of the 20 most profitable AI business models positioned to capture institutional market share in 2026.
Category I: Enterprise Autonomous Agents & Regulatory Infrastructure
1. AI-Driven Automated Regulatory Compliance & Audit Systems: As regulatory oversight around global supply chains, ESG reporting, and data privacy tightens, enterprises face ballooning compliance overhead. Businesses delivering real-time, autonomous audit engine platforms that continuously analyze corporate transactions against localized compliance databases are replacing manual consulting billable hours with high-margin SaaS subscriptions.
2. Autonomous Legal Discovery & Contract Lifecycle Intelligence: Moving far beyond simple contract storage, next-generation legal tech platforms utilize multimodal RAG architectures to perform deep structural due diligence, flag high-risk liability clauses, and autonomously draft jurisdiction-compliant commercial agreements, drastically reducing legal spend for Fortune 500 legal departments.
3. Automated M&A Due Diligence & Deal-Sourcing Platforms: Middle-market private equity firms are increasingly deploying specialized financial analytics platforms capable of ingesting target company financial statements, customer sentiment data, and market metrics to calculate precise, real-time risk-adjusted valuation multiples and flag balance sheet anomalies.
4. Enterprise Autonomous Cyber Threat Remediation Engines: Legacy cybersecurity tools alert human teams to breaches; 2026 cyber AI business models actively isolate infected cloud containers, rewrite compromised code paths in real time, and deploy synthetic decoys without human intervention, dramatically lowering corporate cyber liability insurance premiums.
5. Cross-Border Supply Chain Orchestration Platforms: Leveraging predictive spatial intelligence and multi-agent systems, these platforms dynamically re-route global freight shipments around geopolitical disruptions, optimize port customs documentation, and forecast inventory stockouts to protect working capital liquidity.
Category II: Healthcare, BioTech & Precision Industrial Systems
6. Synthetic Data Platforms for Clinical Trial Simulation: By building privacy-compliant, algorithmically generated patient cohorts, clinical trial simulation providers allow pharmaceutical companies to stress-test drug candidate toxicity profiles early, compressing clinical development timelines and saving tens of millions in clinical burn rates.
7. Medical Coding & Autonomous Revenue Cycle Management (RCM): Healthcare providers operate on razor-thin operating margins due to claims denials and administrative latency. AI RCM platforms convert complex physician notes into precise medical billing codes instantly, mitigating insurer pushback and improving hospital cash-flow liquidity.
8. Industrial Digital Twins & Predictive Asset Maintenance: Combining computer vision with Internet-of-Things (IoT) telemetry, predictive asset maintenance businesses sell software that monitors industrial machinery health, predicting mechanical failures weeks in advance to prevent catastrophic factory floor downtime.
9. Precision Agriculture & Yield Optimization Infrastructure: Autonomous agronomy startups utilizing localized satellite imagery, soil sensors, and micro-climate forecasting algorithms deliver real-time variable fertilizer and water prescriptions, maximizing crop yields while lowering input costs for commercial farming conglomerates.
10. AI Computational Biology & Target Discovery Engines: Specialized bio-AI services leverage specialized deep-learning models to analyze protein folding structures and target dynamic cellular pathways, partnering with large pharma via upfront licensing fees and milestone royalty arrangements.
Category III: Algorithmic Finance & Capital Allocation Infrastructure
11. Real-Time Fraud Mitigation & Algorithmic Risk Analytics: Financial institutions are replacing legacy rule-based fraud software with dynamic neural networks that analyze user behavioral biometrics and transactional contexts in milliseconds, halting sophisticated synthetic identity fraud while preserving transaction throughput.
12. Automated Institutional Real Estate Underwriting & Valuation: By aggregating hyper-localized zoning micro-data, foot-traffic pattern telemetry, satellite imagery, and localized economic trends, automated real estate platforms enable commercial lenders to underwrite multi-million-dollar property loans in hours rather than weeks.
13. Next-Generation InsurTech Adjusting & Computer Vision Claims: InsurTech platforms utilizing high-resolution drone imagery and mobile video capture automatically assess physical property and automotive damage, generating accurate repair cost estimates and disbursing payouts autonomously.
14. Hyper-Personalized Wealth Management Micro-Services: B2B platforms providing private banks and registered investment advisors (RIAs) with personalized portfolio rebalancing, algorithmic tax-loss harvesting, and automated tax-optimized estate planning tools at scale.
Category IV: Vertical SaaS, Enterprise Operations & Compute Efficiency
15. Multi-Modal Voice AI for Enterprise Field Operations: High-reliability, low-latency conversational AI platforms tailored for logistics dispatchers, field technicians, and emergency service operators, converting natural speech commands into structured ERP system inputs in real time.
16. Enterprise Refactoring Engines for Legacy Code Migration: Thousands of institutions remain trapped on mainframe architecture running legacy COBOL or FORTRAN. AI code migration platforms parse, translate, test, and containerize legacy code bases into modern micro-services software at a fraction of manual consulting costs.
17. Enterprise RAG Orchestration & Knowledge Graph Platforms: Middleware companies that securely aggregate fragmented corporate data across cloud repositories (Slack, Google Workspace, SAP, Salesforce) into dynamic, queryable graph databases, driving unified organizational search.
18. Specialized Vertical SaaS for Trades and Logistics: Custom operational management systems embedded with generative scheduling, automated invoice dispatching, and predictive route optimization designed specifically for mid-market HVAC, plumbing, electrical, and localized freight operators.
19. High-Scale Synthetic Video & Enterprise Localization Pipelines: B2B content pipelines enabling global brands to automatically re-render training video materials, executive communications, and marketing media into dozens of native languages with localized visual lip-sync accuracy.
20. AI Cloud Compute Optimization & Data Center Thermal Infrastructure: Software platforms designed to monitor data center workload execution, optimizing GPU utilization rates, dynamically shifting training workloads to lower-cost energy grids, and optimizing liquid cooling deployments to reduce power bills.
Verified Data / Metrics Breakdown Table
The following metrics highlight the projected economic profiles, capital expenditure demands, and market valuations across the foundational core sectors of the 2026 AI ecosystem.
| Market Sector Segment | Projected 2026 TAM ($B) | Avg. Initial CapEx Requirements | Target Gross Margins (%) | Dominant Enterprise Tech Stack |
|---|---|---|---|---|
| Enterprise Autonomous Agents & RegTech | $48.5 B | $1.5M - $3.5M | 78% - 85% | Fine-tuned SLMs, Hybrid RAG, Vector Databases |
| Healthcare RCM & Synthetic Bio-Tech | $62.0 B | $2.5M - $6.0M | 70% - 78% | HIPAA-compliant Enclaves, Multimodal Models |
| Algorithmic Finance & InsurTech Risk | $54.2 B | $2.0M - $5.0M | 75% - 82% | Graph Neural Networks, Edge Compute Nodes |
| Industrial Digital Twins & Agritech | $39.8 B | $1.0M - $3.0M | 68% - 75% | IoT Edge Vision, Spatial Computing Algorithms |
| Legacy Refactoring & GPU Compute Software | $31.4 B | $800K - $2.2M | 80% - 88% | AST Parsing Engines, Dynamic Resource Allocation |
Industry & Market Implications
The transition toward operational, value-focused AI applications creates distinct shifts across the macroeconomic landscape, redefining competitive moats and capital flows.
The Market Winners
- Vertical Data Owners: Legacy enterprises possessing proprietary, non-public data sets (e.g., specialized medical records, historical freight logs, proprietary underwriting tables) hold powerful strategic leverage over pure software players.
- Agile Infrastructure Optimizers: Software platforms that reduce inference compute costs and manage GPU cluster latency are essential infrastructure partners for enterprise CTOs working under strict IT budget allocations.
- Modular API Architecture Platforms: B2B platforms built with open, modular architectures allow enterprise clients to swap out underlying foundational models seamlessly without destroying workflows.
The Market Losers
- Generic "Wrapper" Startups: Early-stage startups offering basic thin-layer user interfaces on top of third-party foundation LLMs without proprietary workflow integrations continue to suffer severe margin compression and high churn rates.
- Time-and-Materials IT Consultants: Traditional professional service firms reliant on billable hours for manual code maintenance, standard compliance auditing, and document processing face structural revenue declines as enterprise clients adopt autonomous software agents.
People Also Ask (FAQ)
Which AI business models offer the highest gross margins and retention in 2026?
Vertical AI applications built directly into core operational workflows—such as Medical Revenue Cycle Management (RCM), legacy code refactoring platforms, and automated regulatory compliance engines—yield the highest gross margins (78% to 88%). Retention rates for these platforms remain exceptionally high because they operate as critical institutional systems of record, making switching costs prohibitive for business clients.
How are foundation model upgrades impacting specialized enterprise AI startups?
While foundation model upgrades occasionally render simple productivity tools obsolete, specialized enterprise startups insulate themselves by building proprietary data loops, security integrations, and deep API integrations into complex software (e.g., ERP, CRM, and EHR platforms). The foundational model serves merely as the underlying commodity inference engine, while the startup captures value through domain specificity and context.
What is the typical seed-to-Series-A capital requirement for enterprise AI platforms?
Due to falling open-source model optimization costs and cheap cloud inference options, initial capital requirements have bifurcated. Specialized SaaS and refactoring platforms often reach market readiness with seed capital allocations between $800,000 and $2.5 million. Conversely, clinical drug discovery and computer-vision-heavy industrial applications require larger seed allocations ($3 million to $6 million) to handle regulatory validation and hardware integration testing.
How will the EU AI Act and global regulations affect early-stage enterprise startups?
Global regulations represent both an operational hurdle and a significant commercial opportunity. While high-risk AI applications (such as automated hiring tools or biometric security) require rigorous audit trails, safety testing, and compliance costs, startups that specialize in automated compliance and risk mitigation software stand to capture significant market share as corporations spend heavily to avoid regulatory fines.
Future Outlook & Strategic Milestones to Watch
As the corporate market navigates 2026, market observers should track three pivotal operational metrics to gauge the health of the commercial AI market:
First, the stabilization of cloud compute unit economics. The continued adoption of small, domain-specific models trained on optimized synthetic data will lower inference costs, expanding gross margin profiles for vertical SaaS operators. Second, the speed of autonomous agent orchestration. As multi-agent frameworks transition from experimental labs to production environments, companies capable of managing multi-agent workflow reliability without human oversight will attract premium acquisition valuations from private equity acquirers. Finally, regulatory clearings and enterprise audit frameworks will solidify structural moats, favoring well-capitalized startups that prioritize risk mitigation, data privacy compliance, and undeniable enterprise ROI from day one.