The Compute Dilemma: Inside Alphabet’s Aggressive Q2 Capex Escalation, Gemini’s Enterprise Inflection, and the Battle for Search Margins
Executive Takeaways
- Unapologetic Infrastructure Expansion: Alphabet signaled zero near-term margin concessions to Wall Street, elevating quarterly capital expenditures past $13 billion—driven by high-density data center buildouts, custom TPU silicon deployments, and next-generation liquid-cooled server clusters.
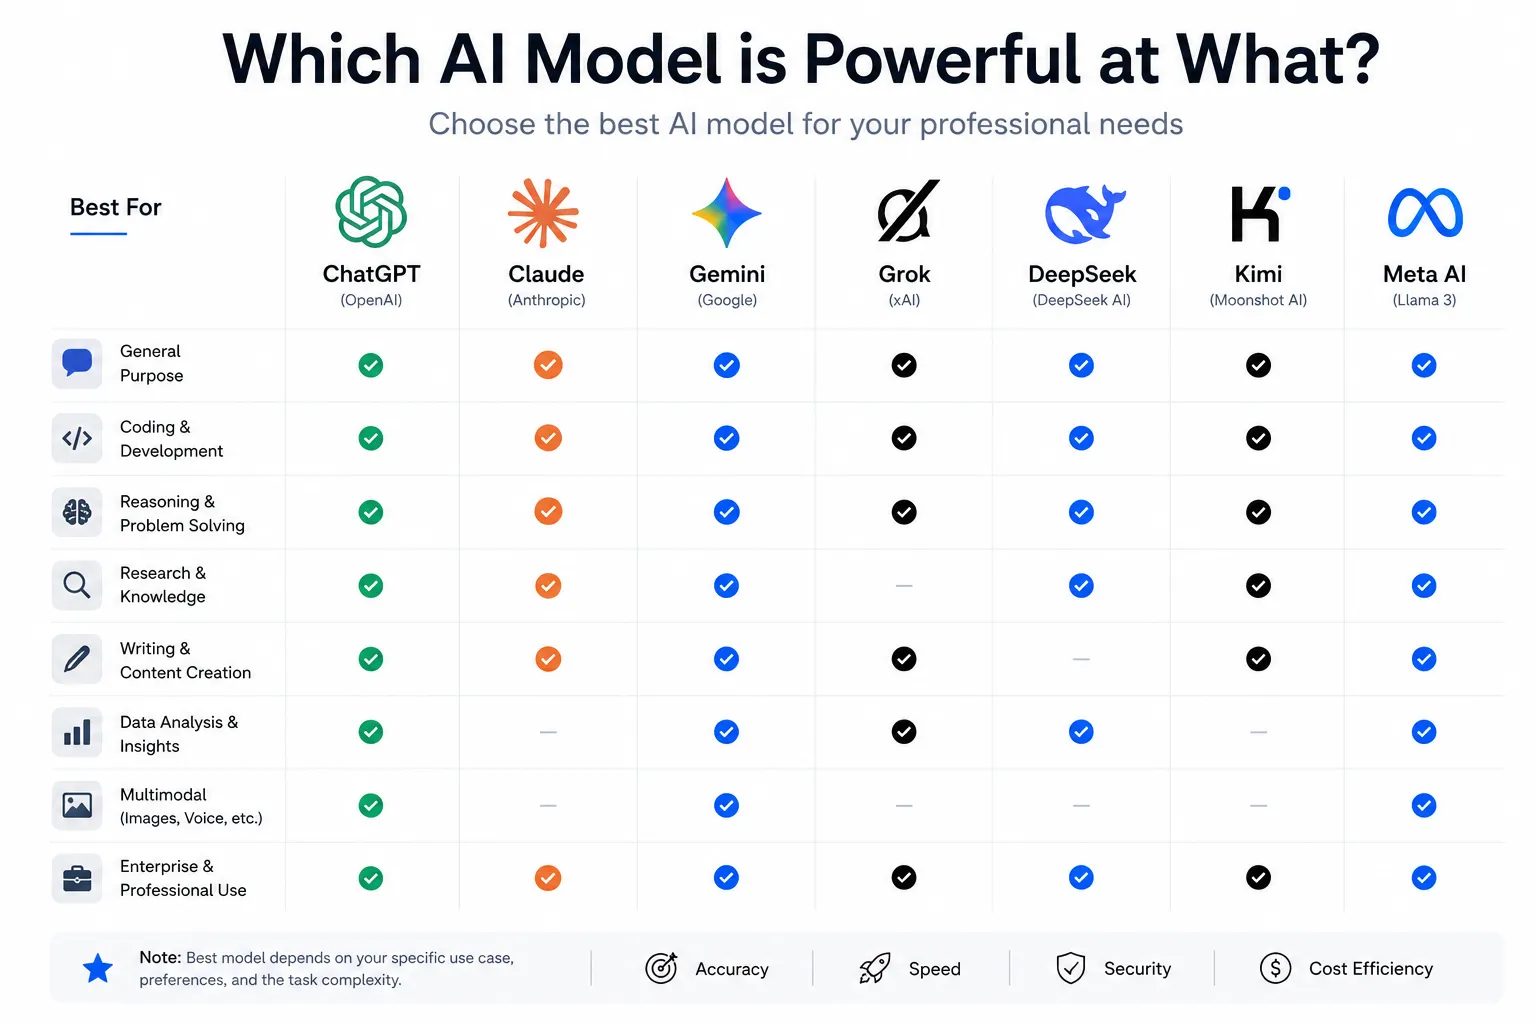
- Gemini Crosses the Scale Threshold: Beyond consumer-facing chatbots, Gemini 1.5 Pro and Flash have achieved critical enterprise developer velocity via Vertex AI, moving the generative AI narrative from speculative pilot programs to recurring enterprise API run-rates.
- Google Cloud Operating Leverage Breakout: Cloud revenue surpassed the historic $10 billion quarterly milestone, generating expanding operating income that begins to insulate Alphabet from the compute-heavy cost structures of search-integrated inference.
- The Under-Investment Risk Doctrine: Chief Executive Sundar Pichai codified a pivotal strategic posture for institutional investors: in the foundation model arms race, the corporate downside of structural under-investment vastly outweighs the transitory friction of excess hardware depreciation.
The Macro Context: A High-Stakes Balancing Act in Silicon Valley
When Alphabet filed its second-quarter financial results, equity desks across London, New York, and Singapore were not merely scrutinizing top-line search buoyancy. The pivotal concern was the health of corporate unit economics in an era dominated by hyper-scaler capital cycles. For the past six quarters, the tech sector has operated under the shadow of generative AI’s astronomical infrastructure overhead. Investors demanded concrete signals that the hundreds of billions funneled into high-bandwidth memory (HBM), bespoke silicon, and specialized data centers would translate into measurable enterprise ROI rather than systemic gross margin compression.
Alphabet’s Q2 print provided unequivocal answers—and revealed a corporation operating on war footing. The Mountain View-based conglomerate delivered an assertive operating narrative: rather than trimming compute budgets to appease short-term valuation multiples, Alphabet is leaning decisively into capital allocation intensity. In parallel, the commercialization of its proprietary Gemini ecosystem has matured from defensive brand-building into an aggressive developer monetization funnel. Below is the forensic breakdown of the three defining developments from Alphabet's Q2 earnings and their downstream ramifications for enterprise software, global data center supply chains, and Big Tech antitrust realities.
Takeaway 1: The Capex Escalation — Why the “Risk of Under-Investing” Dictates Strategy
The single most market-moving metric inside the filing was the aggressive ramp in capital expenditure. Alphabet deployed more than $13 billion in a single quarter—predominantly funneled into technical infrastructure, high-tier compute clusters, and proprietary real-estate interconnects. With an annualized capex run-rate trajectory threatening to breach $50 billion, institutional analysts immediately probed the durability of free cash flow conversion.
Sundar Pichai’s response during the institutional call captured the contemporary hyper-scaler orthodoxy: "The risk of under-investing is dramatically greater than the risk of over-investing." This statement represents an existential pivot. In the estimation of Alphabet’s leadership, over-building compute yields tangible, multi-year residual value—principally in the form of general-purpose data centers, dark fiber, and reusable accelerator racks that possess a five-to-six-year operational lifespan. Conversely, under-building infrastructure risks catastrophic platform obsolescence, surrendering developer ecosystems to Microsoft-backed OpenAI or Amazon Web Services (AWS).
A crucial financial buffer mitigating this compute burden is Alphabet’s internal silicon diversification. Unlike cloud competitors entirely beholden to merchant silicon pricing, Alphabet continues to deploy its proprietary Tensor Processing Unit (TPU) architecture—most notably the TPU v5p and the recently unveiled Trillium (TPU v6). By driving a substantial fraction of Gemini’s internal pre-training and real-time inference workloads away from external merchant silicon and onto custom ASICs, Alphabet captures significant structural cost efficiencies, blunting the impact of escalating megawatt costs and enterprise GPU spot pricing.
Takeaway 2: Gemini’s Architectural Pivot — Context Windows and Enterprise Velocity
Six months ago, market skeptics questioned whether Alphabet’s foundational model lineup could differentiate itself amidst a deluge of open-weights competition and cutting-edge closed models. Q2 demonstrated that Gemini has achieved both technical and commercial product-market fit, particularly within the enterprise developer cohort.
The critical catalyst is Gemini 1.5 Pro’s breakthrough architecture—specifically its production-level long context window scaling from 1 million to 2 million tokens. In production environments, this capability has decoupled enterprise development from complex, brittle Retrieval-Augmented Generation (RAG) pipelines. Corporations can now pass entire institutional codebases, multi-hour video streams, or comprehensive balance sheets directly into the model’s active attention mechanism.
Simultaneously, the aggressive rollout of Gemini 1.5 Flash targeted the economics of enterprise inference. Historically, integrating advanced model intelligence into real-time applications generated latency bottlenecks and prohibitive cost-per-query overhead. By slashing token latency and pricing by orders of magnitude, Alphabet has driven explosive adoption across its Google Cloud Vertex AI portfolio. Tens of thousands of enterprise clients are now building customer-facing workflows directly on Google-managed generative models. Gemini is no longer an algorithmic showcase; it is a scaled utility layer delivering compounding API billing.
Takeaway 3: Google Cloud Margins Decouple From Search Subsidies
For more than a decade, institutional fund managers treated Google Cloud Platform (GCP) as a heavily subsidized enterprise experiment—a platform funded by the peerless cash generation of Google Search's cost-per-click (CPC) empire. Q2 decisively shattered that historical framing.
Google Cloud surpassed the landmark $10 billion quarterly revenue threshold, posting double-digit operating margins that highlight genuine operational leverage. This marks a profound inflection point for Alphabet's consolidated margin profile. Cloud is no longer merely crossing break-even; it is expanding profitability via automated infrastructure management, tiered multi-tenant storage, and specialized enterprise AI software licenses.
This standalone operational profitability arrives at a critical juncture for Google’s legacy Search franchise. The rollout of AI Overviews across global search surfaces fundamentally alters the unit economics of a query. Generating dynamic, synthesized AI overviews requires multiple orders of magnitude more compute per impression than legacy inverted-index algorithmic retrieval. The surging operating income generated by Google Cloud provides Alphabet the exact financial cushion required to defend search volume, experiment with ad insertion formats in generative results, and absorb higher cost-per-query realities without deteriorating corporate operating margin integrity.
Financial Architecture: Alphabet Q2 Strategic Performance Metrics
The following audit tracks Alphabet's core operational metrics, contrasting Q2 performance against baseline historical trends and reflecting the infrastructure-heavy transformation underway across the firm’s key units.
| Operational / Financial Metric | Q2 Baseline Context | Strategic Driver & Segment Dynamic | Wall Street Implication |
|---|---|---|---|
| Quarterly Capital Expenditures (Capex) | ~$13.2 Billion+ | Accelerated procurement of technical infrastructure, TPU v5p/Trillium, data center mechanicals. | Near-term free cash flow yield compression offset by long-term capacity ownership. |
| Google Cloud Segment Revenue | >$10.3 Billion | Vertex AI enterprise uptake, SaaS consumption models, cross-selling with Google Workspace. | Validates GCP as an enterprise-grade profit center independent of advertising. |
| Cloud Operating Margin | Expanding double-digit (>11%) | Hyper-scaler operating efficiency, optimized resource virtualization, enterprise contract size growth. | Re-rates Alphabet’s valuation multiple toward enterprise software comparables. |
| Gemini Context Token Capacity | Up to 2.0M Tokens | Gemini 1.5 Pro deep multimodal retrieval; migration away from complex vector databases. | Creates a wide technical moat against competing models constrained by 128k context limits. |
| Search & Other Advertising Momentum | Mid-to-High Single Digit Growth | Integration of AI Overviews, algorithmic auction matching, retail vertical resilience. | Demonstrates traditional query volume is not collapsing in the face of standalone LLMs. |
Industry & Market Implications: Structural Winners and Losers
Alphabet’s assertive print cascades across the broader tech landscape, shifting dynamics across several core sectors:
The Clear Beneficiaries
- Data Center Infrastructure & Thermal Management Providers: With power consumption scaling exponentially due to high-density racks, suppliers of liquid cooling systems, high-voltage transformers, and modern transmission lines retain multi-year pricing power.
- Enterprise Cloud Clients: Alphabet’s willingness to aggressively price Gemini 1.5 Flash triggers competitive deflation among model providers, lowering token processing costs for startups and Fortune 500 automation pipelines alike.
- Custom Silicon Design Ecosystems: Alphabet’s sustained validation of custom ASIC pathways (TPUs) cements the industry consensus that commercial dominance requires bespoke hardware co-designed with model architectures.
The Exposed Challengers
- Thin AI Software Wrappers: Startups whose sole value proposition was indexing or performing simplistic RAG pipelines across large documents are rendered largely redundant by Gemini’s 2-million-token native context window.
- Margin-Constrained Search Challengers: Independent generative search engines face an unsustainable cost of capital. Absorbing compute overhead without an enterprise cloud arm or an ecosystem to monetize downstream ad conversions creates existential burn rates.
Frequently Asked Questions (People Also Ask)
Why is Alphabet willing to risk over-investing in AI infrastructure?
Alphabet views compute infrastructure as an asymmetric risk environment. If the company over-allocates capital, the hardware assets—such as data centers, fiber infrastructure, and TPU clusters—can be repurposed across search indexing, YouTube video processing, internal research, and enterprise cloud hosting over several years. However, if the company under-invests, it faces an unrecoverable structural decline: developers migrate to competing cloud ecosystems, and users transition to alternative intelligence engines, permanently damaging its core monetization moats.
How does Gemini 1.5 Pro's 2-million-token context window impact enterprise adoption?
A 2-million-token context window fundamentally changes how software engineers interact with foundational models. Instead of chunking documents, generating vector embeddings, and running retrieval algorithms through specialized vector databases, developers can feed entire enterprise repositories, historical datasets, or massive regulatory archives directly into the prompt. This eliminates operational complexity, reduces hallucination rates in document synthesis, and accelerates the time-to-market for production-grade enterprise software.
Will AI Overviews permanently compress Google’s Search profit margins?
While serving generative AI inference initially costs significantly more than processing a traditional keyword search query, Alphabet is neutralizing this compression via two vectors: aggressive hardware optimization (using custom TPUs and smaller, specialized models like Gemini Flash) and programmatic ad integration. Furthermore, historical search data shows that AI Overviews increase total user engagement and query volume among younger demographics, expanding the aggregate addressable monetizable search surface.
What made Google Cloud’s Q2 financial performance historic?
For years, Google Cloud was unprofitable as Alphabet invested heavily to catch up to Amazon Web Services (AWS) and Microsoft Azure. In Q2, Google Cloud not only crossed an annualized run-rate of $40 billion ($10 billion quarterly), but it also generated robust, expanding operating margins. This demonstrates that Google Cloud has achieved critical mass and operational leverage, transforming from a capital-drain segment into a dependable driver of consolidated corporate profits.
Strategic Horizon: What to Watch Through the Rest of the Fiscal Cycle
As Alphabet accelerates through the current fiscal year, executive focus shifts to execution efficiency and regulatory resilience. Institutional investors will be monitoring three critical metrics: first, the pace of ad insertion inside AI Overviews and whether cost-per-click realizations outpace the compute cost of running inference; second, the initial enterprise migrations to Alphabet’s next-generation Trillium TPU silicon; and third, the judicial developments surrounding Alphabet’s high-profile Department of Justice antitrust proceedings.
Alphabet has drawn a sharp line in the sand. It will not allow its foundation model positioning to be undermined by short-term balance sheet conservatism. Armed with a newly self-sustaining Cloud division, custom ASIC hardware moats, and a Gemini model architecture that is setting standard benchmarks across global enterprise software, Alphabet has proved that it has both the capital firepower and the technological endurance to lead the generative era.