⚡ Interactive Technical Utility
Launch Free Tools →
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
Executive Takeaways
- The End of Cheap Capital: After more than three years of historic monetary accommodation, central bank policy pivots toward tightening, fundamentally altering global capital allocation and corporate valuation multiples.
- Enterprise Exposure: Organizations relying on continuous leverage, heavy infrastructure scalability via debt financing, and aggressive growth models face immediate margin compression and rigorous risk mitigation audits.
- Valuation Resets: Equity markets are aggressively repricing risk, shifting institutional capital flows away from speculative high-growth assets toward cash-generative, defensive equities with strong market liquidity.
- Strategic Imperatives: CFOs and treasurers must overhaul treasury management, fortify balance sheets, and optimize regulatory compliance as debt servicing costs scale globally.
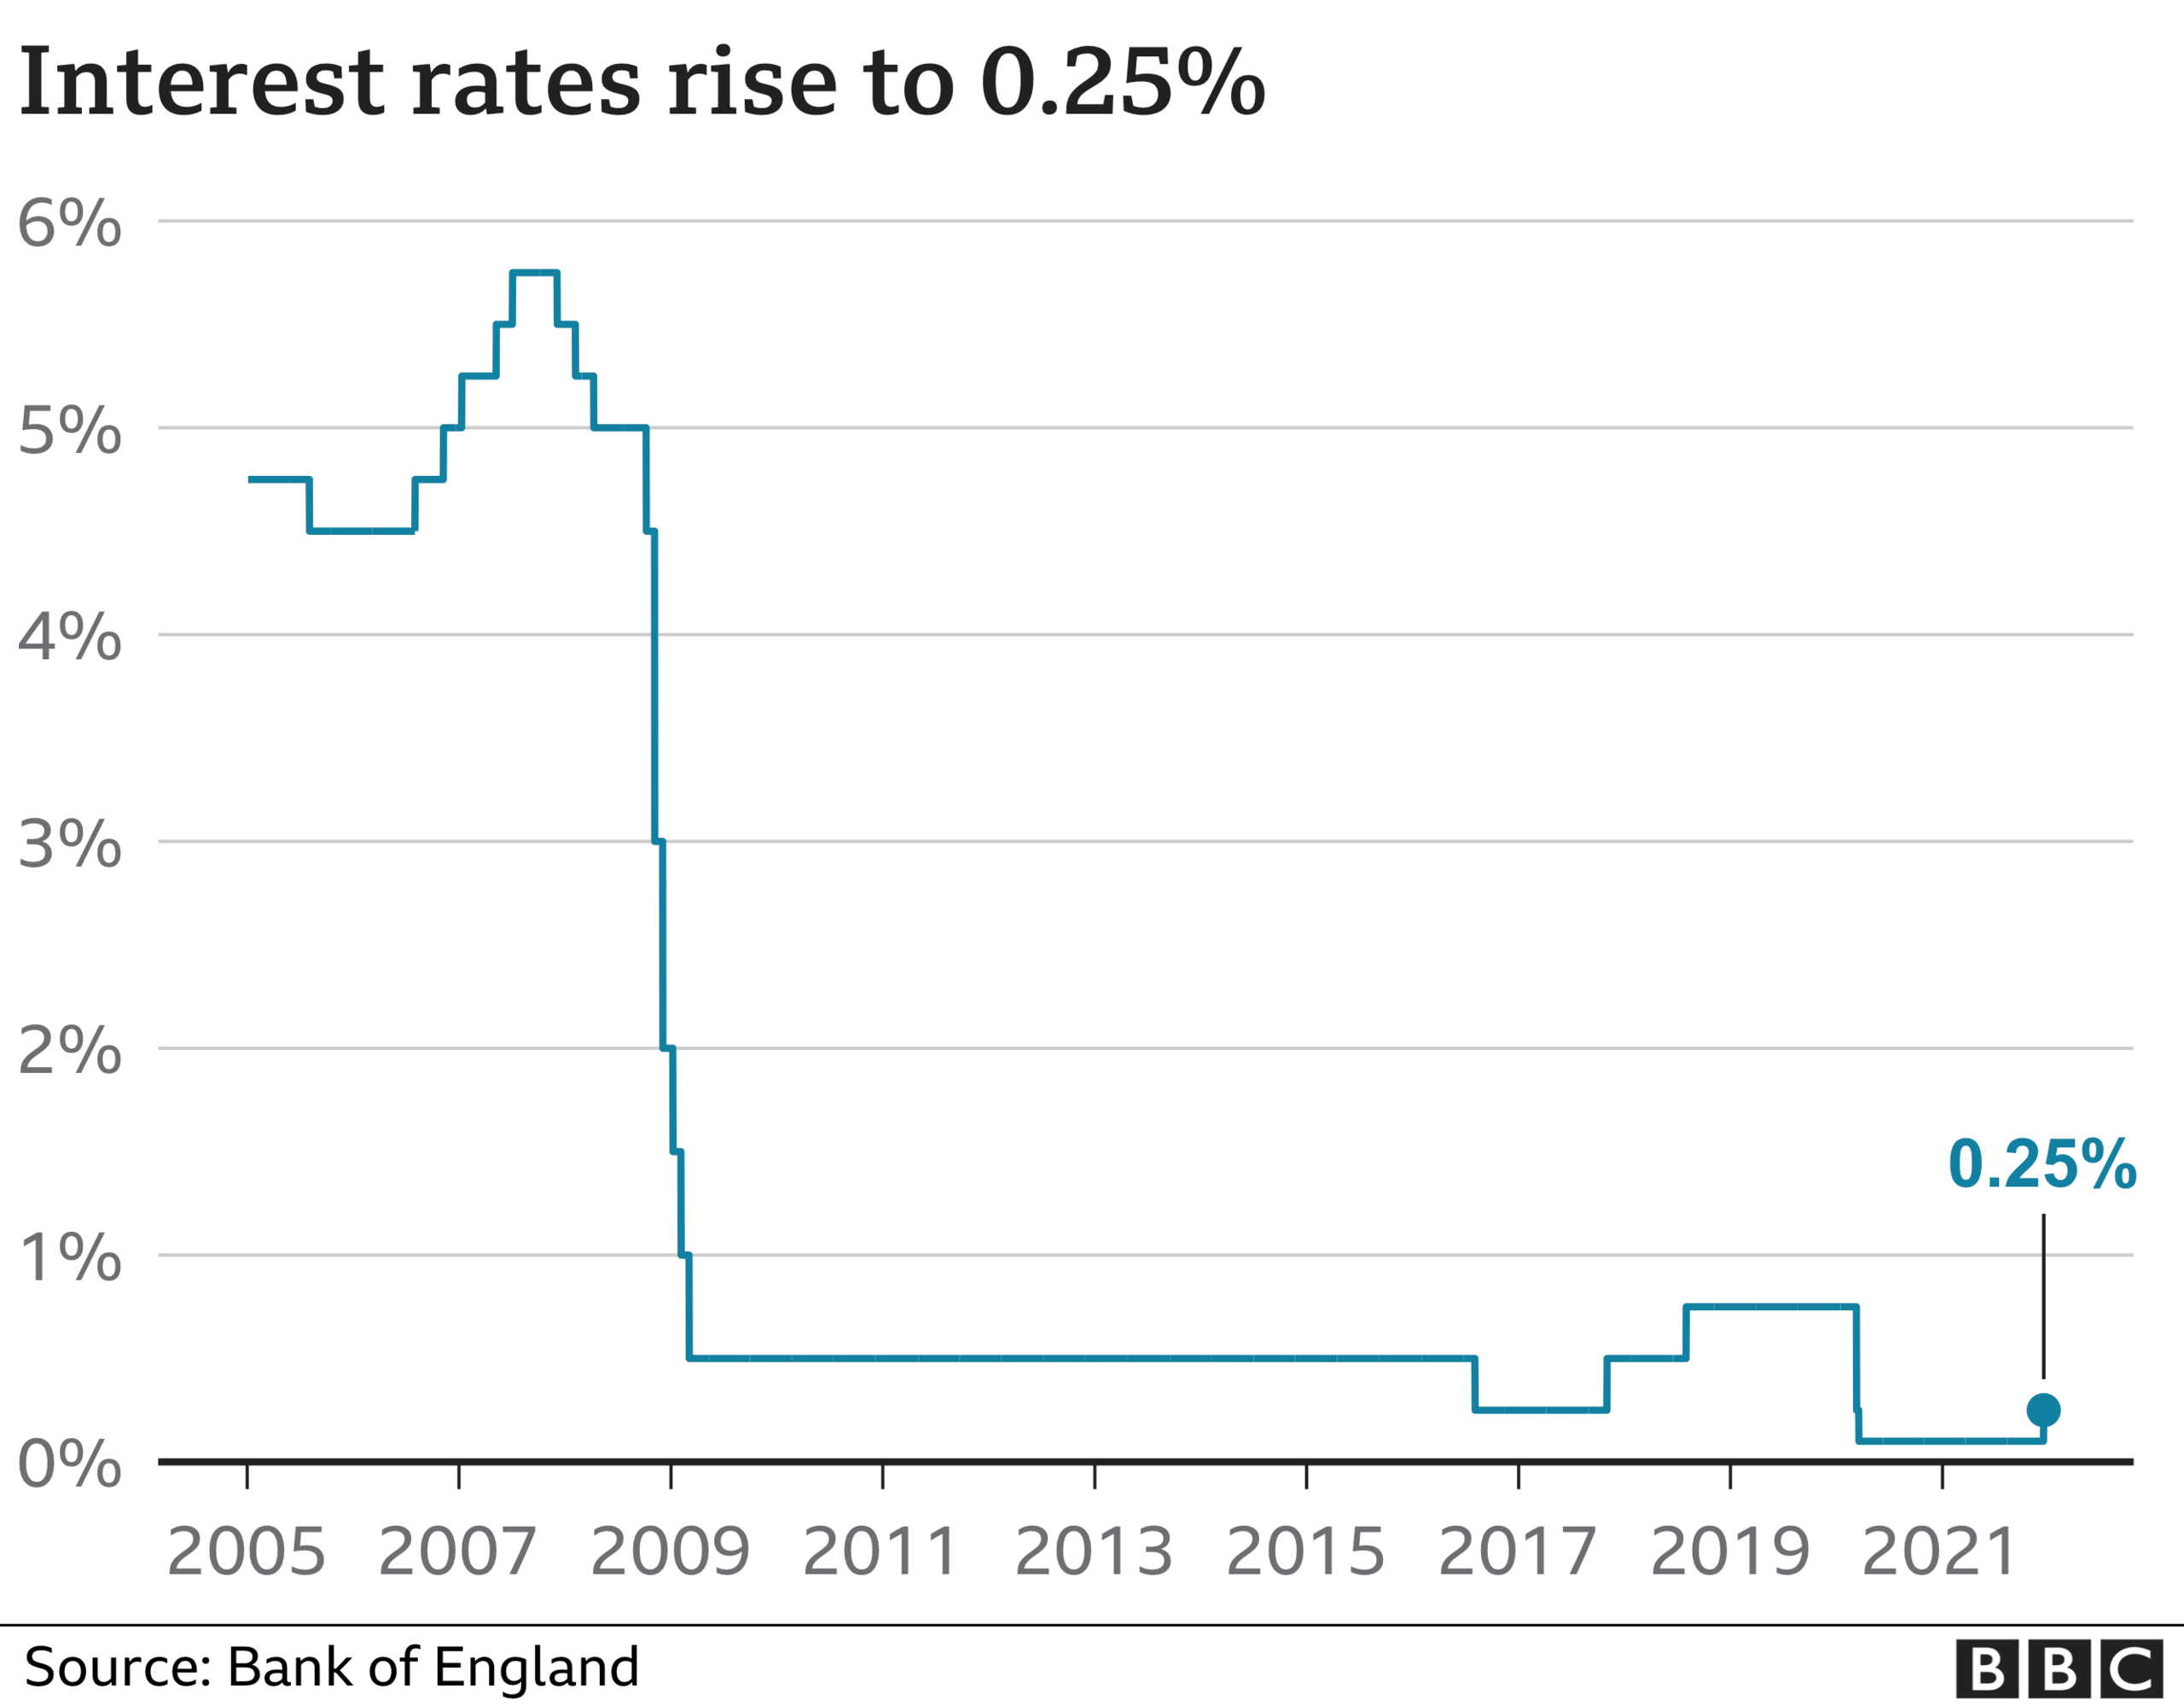
For more than thirty-six months, global financial markets have operated under the comforting umbrella of ultra-low interest rates—an era defined by accessible liquidity, aggressive venture expansion, and compressed corporate borrowing costs. Today, that paradigm stands on the precipice of a historic rupture. According to fresh macroeconomic data and central banking signals captured across real-time wire services and search analytics, benchmark interest rates are projected to rise for the first time in over three years. This
Related Newsroom Intelligence & Analysis
NYT Spelling Bee Answers Today: November 4, 2026 Hints, Pangram Breakdown, and the Financial Engine Driving Digital Subscriptions →