In a summer defined by macroeconomic fragility, the delicate detente between equity markets and monetary policy has officially ruptured. Wall Street’s major indexes plummeted on Friday, August 28, closing sharply lower as market participants digested a uncompromising message from Federal Reserve Chair Kevin Warsh. In a highly anticipated address, Warsh reaffirmed the central bank’s singular, laser-like focus on eradicating structural inflation, effectively dismantling hopes of a dovish pivot and sending institutional investors scrambling to recalibrate their risk mitigation strategies.
The aggressive sell-off marks a pivotal moment in the current tightening cycle. Following a turbulent session earlier in the month—where US stocks whipsawed violently after the Fed enacted its first benchmark rate hike in over three years—Warsh's latest rhetoric has crystallized a grim reality for asset managers: the era of cheap capital is over, and the cost of capital will remain higher for longer. As valuation multiples contract across the board, enterprise capital allocation is undergoing its most radical transformation since the 2008 financial crisis.
Executive Takeaways
- Uncompromising Hawkishness: Fed Chair Kevin Warsh’s latest statements have solidified expectations for a prolonged tightening cycle, driving sovereign yields higher and compressing equity valuation multiples.
- Capital Allocation Paradigm Shift: Institutional investors are rapidly rotating out of speculative growth assets and into high-free-cash-flow enterprises with demonstrable enterprise ROI and strong pricing power.
- Liquidity Dry Spells: Global market liquidity is tightening as quantitative measures and rate hikes increase the equity risk premium, raising debt-servicing costs for leveraged corporations.
- Systemic Re-pricing: Sector-specific pain is mounting, particularly in capital-intensive industries like cloud compute architecture, commercial real estate, and consumer discretionary.
The Warsh Doctrine: Prioritizing Price Stability Over Market Comfort
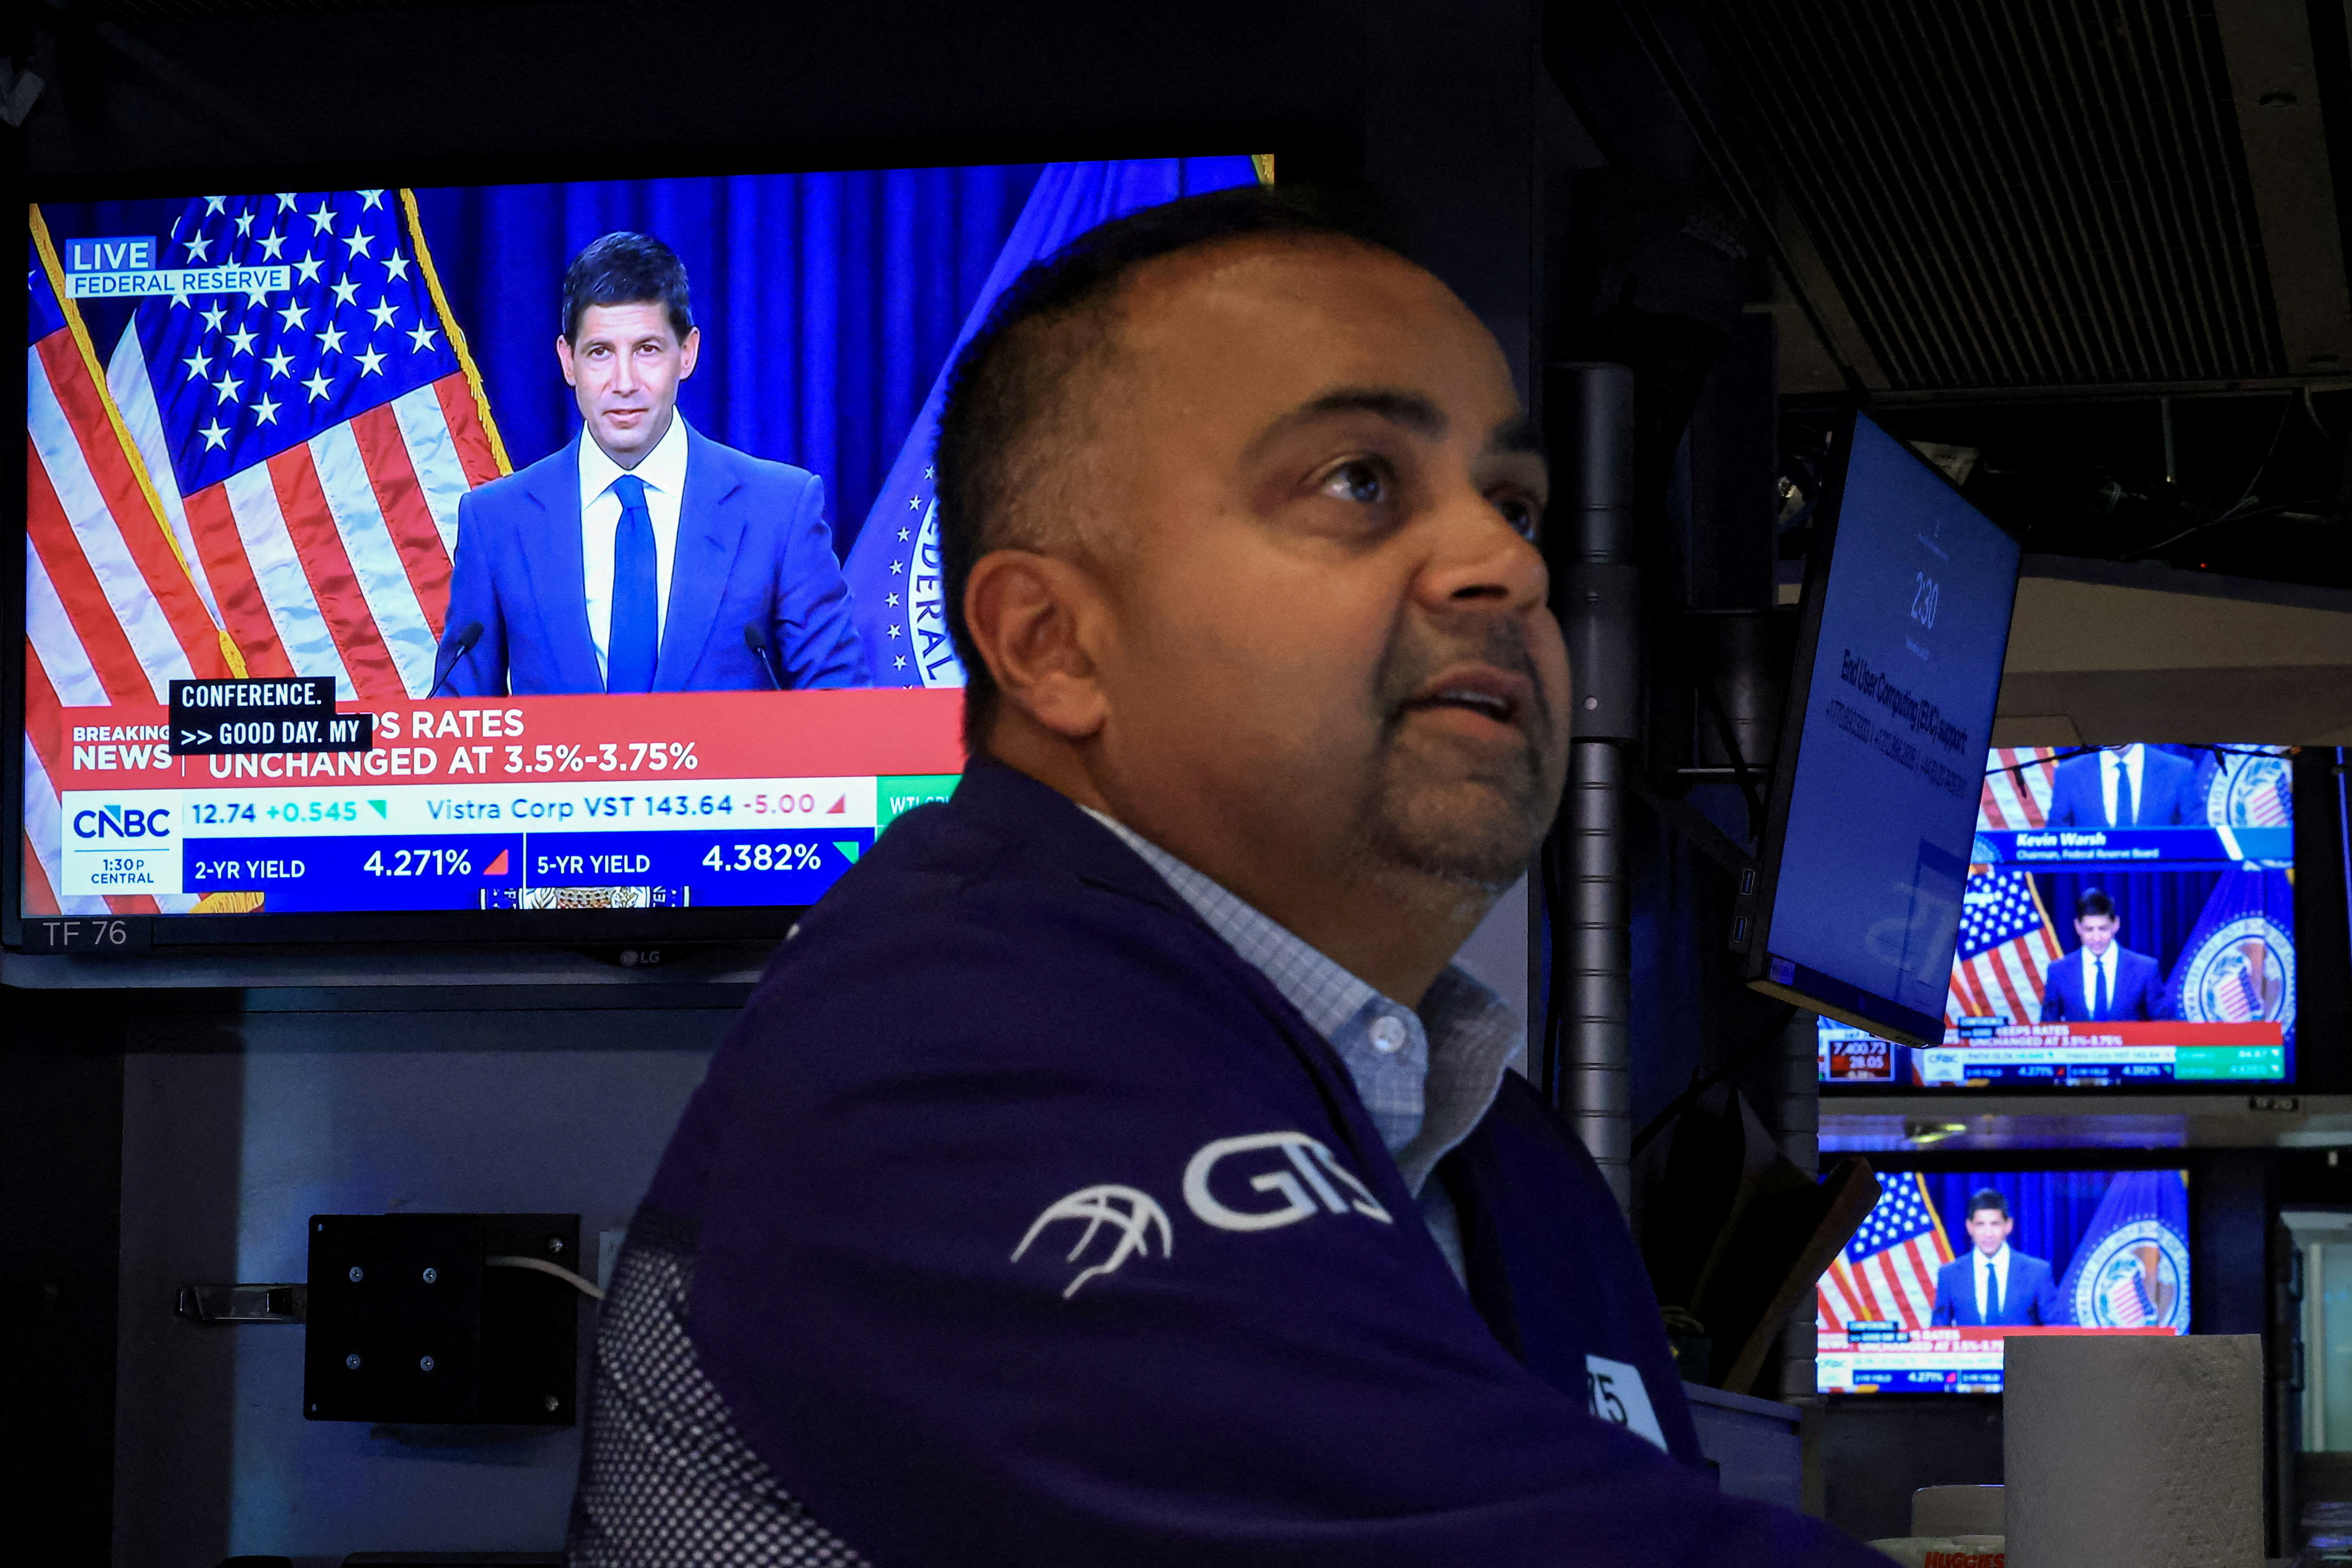
For months, buy-side analysts clung to the narrative that a cooling labor market or slowing GDP growth would compel the Federal Reserve to pause its aggressive tightening campaign. Chair Warsh’s Friday address systematically dismantled that thesis. Speaking to an audience of policymakers and economists, Warsh made it clear that while the central bank is cognizant of the pain inflicted on asset valuations, its primary mandate remains the restoration of price stability.
"Our commitment to returning inflation to our long-term target is unconditional," Warsh stated, signaling that the Fed is willing to accept a period of below-trend economic growth—and even labor market softening—as the necessary price of admission to tame systemic price pressures. This stance has forced a drastic repricing of the Fed Funds terminal rate, with swaps markets now pricing in an additional 50 to 75 basis points of tightening before the end of the fiscal year.
The immediate consequence of this policy trajectory is a profound tightening of financial conditions. As Treasury yields surged across the curve, the discount rate applied to future cash flows rose in tandem. This mathematical reality has triggered an immediate compression in equity valuation multiples, particularly for long-duration assets in the technology and biotechnology sectors, where profitability is projected years into the future.
Deconstructing the Market Mechanics: Multiples, Liquidity, and Risk Mitigation
When the Federal Reserve raised its key policy rate for the first time in over three years on a tumultuous Wednesday earlier this year, it signaled the end of the post-pandemic liquidity surge. Warsh’s latest reaffirmation of that policy direction has accelerated the unwinding of highly leveraged positions. Institutional trading desks report a marked drop in market liquidity, exacerbating intraday volatility and causing sharp, gap-down opens.
From a corporate finance perspective, the transition to a high-rate environment changes how enterprise ROI is calculated. In the zero-interest-rate policy (ZIRP) era, corporations routinely leveraged cheap debt to fund share buybacks and pursue speculative mergers and acquisitions. Today, the hurdle rate for any capital allocation decision has dramatically increased. Corporate treasurers must now balance the high cost of debt servicing against the projected returns of organic growth initiatives.
For multinational enterprises, regulatory compliance and operational efficiency have emerged as critical battlegrounds. Companies can no longer rely on top-line revenue expansion alone to satisfy shareholders; instead, they must demonstrate rigorous cost control, optimized supply chains, and robust risk mitigation protocols to protect net operating margins.
Verified Data: Market Metrics & Valuation Shifts
To understand the depth of the market's reaction to Chair Warsh's hawkish posture, we must analyze the key performance indicators across major asset classes. The table below illustrates the shifting macro-financial landscape following the August 28 announcement:
| Financial Metric / Index | Pre-Announcement Level | Post-Announcement Level | Percentage / Basis Point Change | Implied Economic Outlook |
|---|---|---|---|---|
| S&P 500 Index | 4,450.50 | 4,320.15 | -2.93% | Multiple compression; valuation adjustments in mega-cap equities. |
| Nasdaq Composite | 13,920.00 | 13,410.80 | -3.66% | Capital flight from long-duration technology and growth stocks. |
| 10-Year US Treasury Yield | 3.85% | 4.12% | +27 bps | Bond market pricing in persistent inflation and structural rate hikes. |
| Fed Funds Terminal Rate (Implied) | 4.25% - 4.50% | 4.75% - 5.00% | +50 bps | Higher cost of capital expected to persist through the fiscal year. |
| ICE BofA High Yield Index Spread | 380 bps | 425 bps | +45 bps | Rising default risk premiums for highly leveraged, non-investment grade debt. |
Sectoral Deep Dive: Who Wins, Who Loses, and Broader Economic Impacts
The transition to a highly restrictive monetary regime is not felt equally across the corporate landscape. The divergence between structural winners and cyclical losers is widening, creating distinct tactical opportunities for sophisticated credit and equity long/short managers.
The Technology Sector and Cloud Infrastructure Scalability
For nearly a decade, the technology sector was the undisputed engine of market returns, fueled by cheap capital and aggressive digital transformation initiatives. However, as valuation multiples contract, the focus has shifted entirely from growth-at-all-costs to capital discipline. Companies investing heavily in cloud compute architecture and artificial intelligence must now justify these capital expenditures with clear, short-to-medium-term enterprise ROI.
Enterprise SaaS providers and cloud infrastructure giants are seeing longer sales cycles as their corporate clients implement strict budget reviews. To maintain valuations, tech executives are pivoting toward margin expansion, optimizing their cloud deployments, and scaling back speculative research and development projects. Companies with strong balance sheets and robust recurring revenue streams remain resilient, while cash-burning startups face a punishing "funding winter."
Financial Institutions and Net Interest Margins
Traditionally, commercial banks benefit from a rising interest rate environment, which allows them to widen their net interest margins (NIM)—the difference between what they earn on loans and what they pay on deposits. However, the current yield curve inversion presents a complex challenge. If short-term funding costs rise faster than long-term lending yields, bank profitability can compress.
Furthermore, rising debt-servicing costs raise the specter of credit defaults, particularly within the commercial real estate (CRE) sector. Regional lenders with significant exposure to office properties and highly leveraged developers are under intense scrutiny, forcing them to increase their provisions for credit losses and implement strict risk mitigation frameworks.
Energy and Defensive Sectors
In contrast to the broader market decline, defensive sectors such as utilities, consumer staples, and healthcare have demonstrated relative outperformance. These industries benefit from inelastic demand, allowing them to pass rising input costs directly to consumers, thereby preserving cash flow. Similarly, the energy sector remains a crucial hedge, as supply-side constraints and geopolitics keep commodity prices elevated, providing robust dividend yields and share buyback programs to yield-hungry investors.
People Also Ask (FAQ)
Why did Fed Chair Kevin Warsh reiterate his aggressive inflation fight?
Fed Chair Kevin Warsh reiterated the central bank's focus on fighting inflation because core consumer prices remain sticky and significantly above the Fed's long-term 2% target. Despite initial rate hikes, robust wage growth and resilient consumer demand have threatened to de-anchor long-term inflation expectations. By maintaining a highly hawkish stance, Warsh aims to cool aggregate demand, slow labor market imbalances, and signal to global markets that the Fed will not cut rates prematurely, even if it results in localized economic pain or market corrections.
How do rising interest rates impact corporate valuation multiples?
Rising interest rates directly impact equity valuation multiples through the discounted cash flow (DCF) model. When calculating the present value of a company’s future earnings, financial analysts use a discount rate heavily tied to the risk-free rate (such as the 10-year US Treasury yield) plus an equity risk premium. As the risk-free rate increases, the discount rate rises, reducing the present value of future cash flows. This effect is most pronounced for high-growth tech companies whose profits are projected to occur far in the future, leading to immediate multiple compression.
What is the relationship between federal monetary policy and market liquidity?
Monetary policy directly governs market liquidity through interest rate decisions and quantitative measures (such as quantitative tightening or easing). When the Federal Reserve raises rates and shrinks its balance sheet, it drains reserves from the banking system. This reduction in system-wide liquidity increases funding costs for financial institutions, widens bid-ask spreads, and lowers depth in the secondary credit and equity markets. Consequently, asset prices become more sensitive to large trades, leading to heightened volatility and sudden whipsaws.
How should enterprise companies manage capital allocation in this environment?
In a high-interest-rate environment, enterprise companies must shift their focus from aggressive leverage-fueled expansion to strict capital discipline. Prioritizing investments with guaranteed enterprise ROI, optimizing operational efficiencies, and reducing outstanding high-interest debt are critical strategies. Additionally, corporate leadership should focus on cash flow generation, delay highly speculative research and development projects, and ensure that any capital allocation to share buybacks or M&A activity clears a significantly higher hurdle rate than was required during the low-rate era.
Future Outlook: Navigating the New Macroeconomic Reality
As Wall Street bids farewell to the summer and braces for the final quarters of the fiscal year, the path ahead remains fraught with macroeconomic hurdles. Investors must transition from hoping for a policy reversal to actively positioning for structural hawkishness. The upcoming Consumer Price Index (CPI) releases, non-farm payroll data, and subsequent Federal Open Market Committee (FOMC) policy decisions will serve as critical litmus tests for the economy's resilience.
The ultimate question hanging over global markets is whether Chair Warsh and the FOMC can engineer a "soft landing"—taming inflation without plunging the domestic economy into a severe recession. However, as global supply chains undergo structural realignment and geopolitical tensions persist, the risk of a "stagflationary" outcome remains elevated. In this highly challenging environment, the premium on active asset management, rigorous balance sheet analysis, and meticulous risk mitigation has never been higher. Wall Street has received its warning: the inflation fight is far from over, and the market must adapt or suffer the consequences.