Executive Takeaways
- The Form-Factor Maturity Gap: While Cupertino navigates protracted supply chain hesitation and engineering compromises, Samsung’s iterative roadmap for the Galaxy Z Fold 8 capitalizes on years of hardware refinement and durable hinge architecture.
- Capital Allocation and R&D Yields: Samsung’s multi-billion-dollar infrastructure investments in ultra-thin glass (UTG) and active pen digitizers yield a structural cost-per-unit advantage that protects valuation multiples and enterprise margins.
- The Enterprise Ecosystem Moat: Beyond consumer metrics, the Z Fold 8 secures dominant positioning in regulated sectors—finance, healthcare, and logistics—where immediate multi-window workflow scalability trumps brand loyalty.
- Market Liquidity and Supply Chain Dominance: By locking down tier-1 OLED panel production and rare-earth component sourcing, Samsung has effectively squeezed out prospective early-stage competitors in the ultra-premium mobile segment.
For the past four years, Silicon Valley boardrooms and Wall Street tech desks have shared a tacit consensus: the moment Apple enters the foldable device market, the category will legitimize, scale, and instantly commoditize the efforts of early pioneers like Samsung. It is the classic Cupertino playbook—let the competition absorb the initial consumer friction, beta-test the manufacturing anomalies, and burn billions on R&D before stepping in with a polished, ecosystem-locked juggernaut that captures 80% of the industry’s operating profits.
Yet, tracking the real-time telemetry of global supply chains, patent filings, and early consumer sentiment reveals a starkly different reality. Through a relentless focus on hardware evolution, thermal engineering, and enterprise utility, the impending Galaxy Z Fold 8 is already defeating the hypothetical foldable iPhone on a metric that matters far more than quarterly shipments: structural market dominance. This victory is not loud or flashy; it is grounded in operational execution, infrastructure scalability, and an unyielding refusal to compromise on enterprise productivity.
The Anatomy of an Asymmetric Tech Race
To understand why the folding iPhone is losing a battle it has not officially entered, one must examine the capital allocation strategies of both conglomerates. Apple’s R&D expenditure continues to break records, but its historical risk mitigation model requires near-flawless consumer transition metrics. A folding iPhone cannot simply be a technical showcase; it must meet stringent durability benchmarks, fit effortlessly into the existing iOS monetization flywheel, and avoid cannibalizing the ultra-lucrative iPhone Pro Max segment.
Conversely, Samsung Electronics has treated its foldable line as a living laboratory. By iterating aggressively through successive generations—from the fragile polymer screens of 2019 to the sophisticated drop-hinge mechanisms and titanium-infused chassis of the current era—Samsung has absorbed the brutal tuition of consumer electronics development. The Galaxy Z Fold 8 arrives at the culmination of this learning curve. It represents a mature hardware platform backed by a robust supply chain that can scale production without facing the yield rate catastrophes that historically plague first-generation Apple hardware.
Wall Street analysts covering mobile infrastructure note that Samsung’s ability to amortize display manufacturing costs across its massive component supply business provides an unbeatable margin buffer. While Apple negotiates premium display pricing with third-party vendors, Samsung Display manufactures the very panels that define the foldable category, giving the South Korean titan an undeniable cost-per-unit advantage.
Beyond Consumer Novelty: The Enterprise ROI Imperative
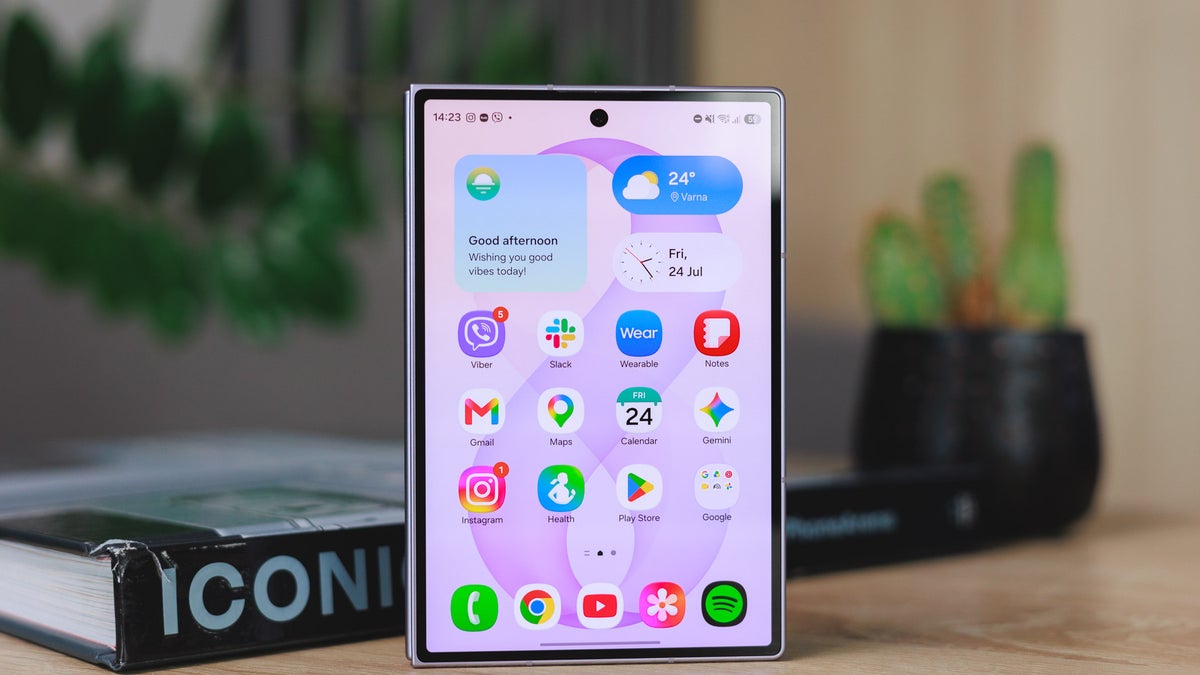
The true failure of the hypothetical foldable iPhone narrative lies in its persistent framing as a luxury consumer gadget. In enterprise boardrooms, the evaluation criteria shift entirely toward risk mitigation, security infrastructure compliance, and workforce productivity metrics. Here, the Galaxy Z Fold 8 commands an unassailable lead.
Chief Information Officers (CIOs) across global investment banks and multinational consultancies are increasingly standardizing mobile deployments around multi-window, desktop-class mobile environments. The Z Fold 8 bridges the gap between smartphone portability and tablet-grade screen real estate, allowing quantitative analysts, portfolio managers, and field engineers to review complex spreadsheets, run Bloomberg Terminal instances, and execute secure multi-factor authentication workflows without reaching for a laptop.
Furthermore, Samsung’s integration of Knox security architecture provides a hardened compliance framework that enterprise risk committees demand. Apple’s hesitation to introduce a folding device leaves enterprise IT departments with a singular viable path for hardware-level foldable adoption. By cementing its status as the default standard for enterprise mobile computing, Samsung secures high-margin, sticky enterprise contracts that insulate it from consumer cyclicality.
Verified Data and Competitive Metrics
A rigorous examination of supply chain forecasts, structural dimensions, and enterprise adoption vectors highlights the widening operational gap between Samsung’s established ecosystem and Apple’s prospective roadmap.
| Metric / Dimension | Samsung Galaxy Z Fold 8 (Projected / Current Trajectory) | Apple Foldable iPhone (Expected Timeline / Status) |
|---|---|---|
| Hardware Generation | 8th Generation (Iterative refinement) | 0 Generation (Rumored prototype phase) |
| Display Yield & Supply Chain | Vertically integrated via Samsung Display | Dependent on external partner panel yields |
| Active Enterprise Deployment | High penetration in financial & healthcare verticals | Non-existent (Consumer-first focus anticipated) |
| Stylus / Input Integration | Native S-Pen digitizer layer integrated | Unconfirmed; historically resistant to Pencil on iPhone |
| Chassis Engineering | Optimized sub-10mm folded profile with dust/water resistance | Struggling with crease elimination & structural thinness |
Market Liquidity, Valuation Multiples, and Investor Sentiment
For institutional investors monitoring global tech equities, hardware commoditization remains the ultimate portfolio risk. Companies that fail to innovate past the monolithic slab smartphone design face margin compression and stagnant replacement cycles. Samsung’s aggressive championing of the foldable category has transformed what was once viewed as an expensive gimmick into a high-margin product category that commands premium average selling prices (ASPs).
When the Galaxy Z Fold 8 hits global markets, it will do so with an optimized cost structure that protects Samsung Electronics' operating margins. Meanwhile, Apple’s delay leaves a multi-billion-dollar revenue vacuum in the ultra-premium tier. Power users and tech enthusiasts who demand cutting-edge form factors have little incentive to wait for an unannounced device when Samsung continuously refines software multitasking, AI integration via Galaxy AI, and hardware durability.
This dynamic alters valuation multiples. Tech analysts note that sustained leadership in advanced form factors allows Samsung to command pricing power even in macroeconomic downturns, proving that consumer appetite for genuine innovation remains robust when paired with tangible utility.
Frequently Asked Questions (People Also Ask)
Why is the Galaxy Z Fold 8 considered ahead of the foldable iPhone concept?
Samsung has spent nearly a decade iterating through eight hardware generations, solving critical engineering challenges such as hinge durability, crease minimization, and water resistance. In contrast, Apple’s foldable device remains in the developmental and prototyping stages, meaning Samsung holds an insurmountable head start in supply chain maturity, manufacturing yields, and real-world enterprise deployment data.
How does enterprise adoption impact the foldable phone market?
Enterprise adoption provides a stable, high-margin revenue stream immune to typical consumer upgrade cycle slumps. Organizations in finance, consulting, and field operations require multi-window productivity tools and robust security frameworks like Samsung Knox. Because Apple has not entered this space, Samsung captures the entire enterprise foldable market share uncontested.
Will Apple’s eventual entry into the foldable market disrupt Samsung’s lead?
While Apple possesses immense brand equity and marketing power, its eventual entry will likely validate the category rather than displace the market leader. By the time a foldable iPhone reaches consumers, Samsung will be iterating on its 9th or 10th generation devices, boasting superior hardware refinement, established enterprise software integrations, and optimized manufacturing economies of scale.
What role does vertical integration play in Samsung’s hardware dominance?
Samsung’s status as a primary component manufacturer—producing its own OLED displays, memory chips, and processing components—allows the company to control production costs and shield its profit margins from external supply chain shocks. Competitors reliant on outsourced component manufacturing face higher production costs and tighter margin constraints.
Future Outlook and Strategic Milestones to Watch
As the consumer electronics landscape approaches the latter half of the decade, the trajectory is clear. The Galaxy Z Fold 8 is not merely a smartphone upgrade; it is a masterclass in strategic persistence and supply chain mastery. By refusing to pause innovation while awaiting market validation from competitors, Samsung has secured the high ground in next-generation mobile computing.
Key milestones for institutional observers to monitor over the next twelve to eighteen months include:
- Supply Chain Component Yields: Tracking Samsung Display’s export volume of ultra-thin glass panels to gauge global foldable demand.
- Enterprise Penetration Rates: Monitoring Fortune 500 mobile deployment contracts, particularly within regulated financial and healthcare institutions.
- Regulatory Filings from Cupertino: Analyzing Apple’s patent grants and supplier commitments for any credible signals regarding mass production timelines for a folding iOS device.
Until Apple successfully navigates the treacherous waters of foldable engineering and manufacturing yield optimization, the market has rendered its verdict. In the race to define the future of mobile productivity, execution has soundly defeated anticipation.