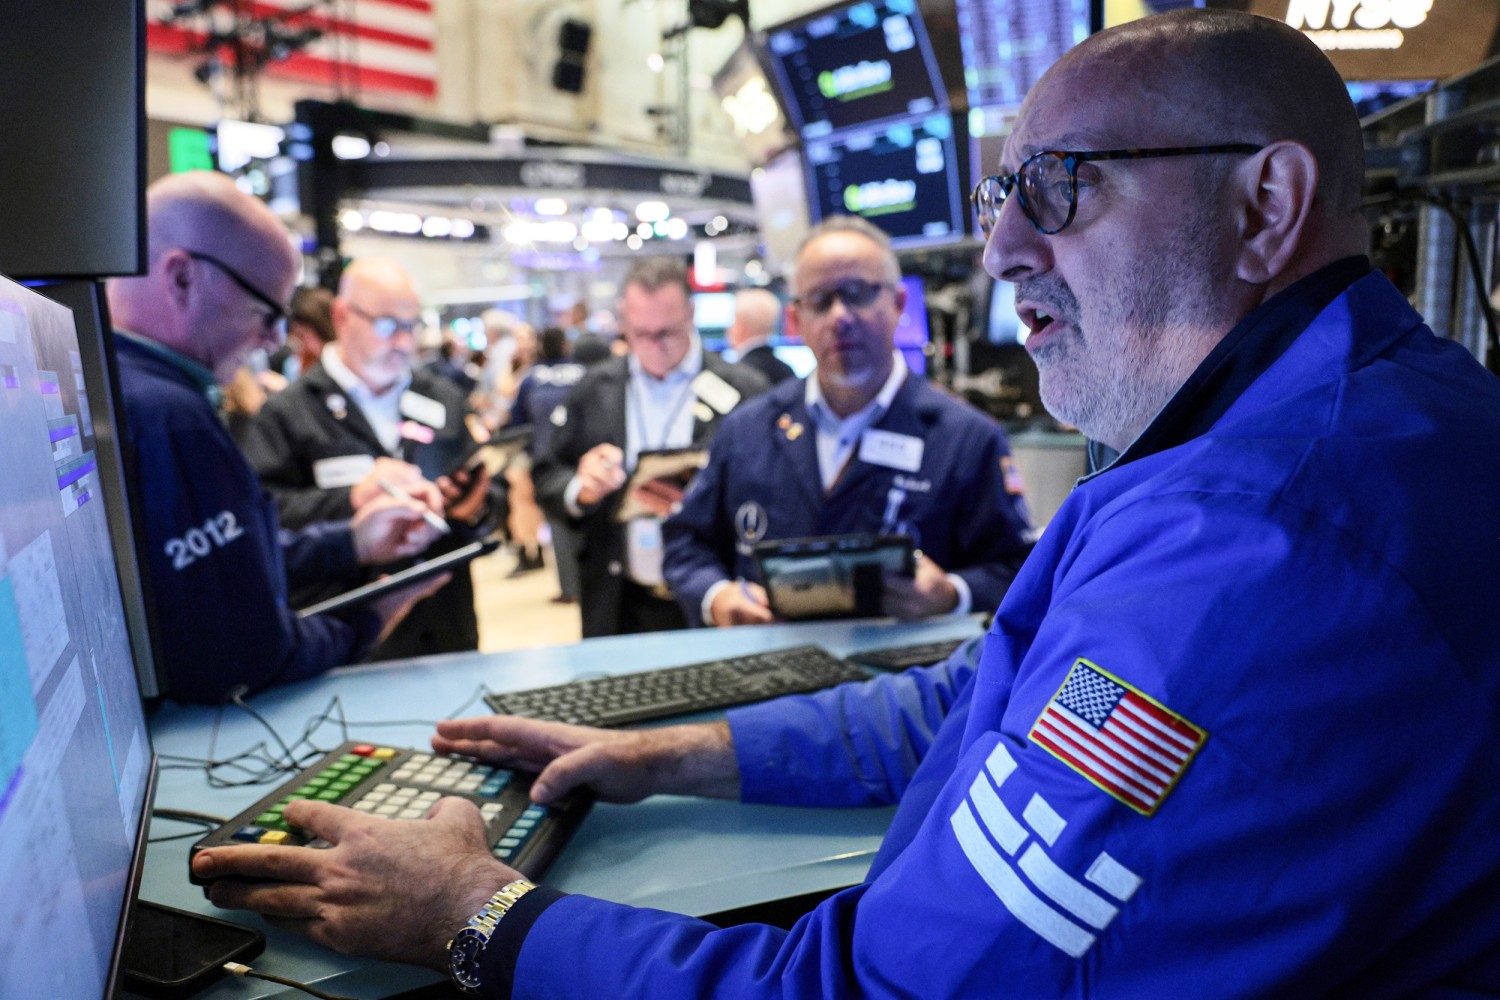
NEW YORK — The unstoppable earnings engine driving the American equity markets through consecutive quarters of record-breaking expansion is showing unmistakable signs of systemic fatigue. According to a landmark institutional strategy note released by Oppenheimer analysts, third-quarter profit momentum for the S&P 500 has decelerated significantly this week, punctured directly by a capital expenditure hangover and a synchronized cooling cycle within the bellwether technology sector. For months, Wall Street bulls have relied on hyper-growth mega-cap enterprises to mask underlying sluggishness across cyclical and consumer-facing verticals. Now, as hyperscalers face intense scrutiny over enterprise ROI and infrastructure scalability, the illusion of limitless margin expansion is evaporating.
This comprehensive investigative report examines the structural catalysts behind the Q3 earnings slowdown, analyzes the rotation of market liquidity, and evaluates the forward-looking risk mitigation strategies required for institutional asset allocators navigating an increasingly volatile macroeconomic landscape.
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Momentum Deceleration: Oppenheimer's institutional research confirms a marked cooling in S&P 500 Q3 profit momentum, driven by a normalization of technology-sector earnings growth.
- Capital Allocation Pivot: Institutional investors are aggressively reassessing capital allocation strategies as generative AI infrastructure investments face heightened pressure to prove immediate enterprise ROI.
- Valuation Compression Risk: Extended valuation multiples across the "Magnificent Seven" leave little room for error, triggering defensive portfolio rebalancing and liquidity rotation into defensive yield assets.
- Macroeconomic Crosscurrents: Sustained high interest rates, uneven consumer credit performance, and shifting regulatory compliance burdens are compounding margin compression outside of big tech.
The Anatomy of a Slowdown: From Infinite Expansion to Reality Check

To understand the gravity of Oppenheimer’s latest diagnostic, one must examine the macroeconomic trajectory that preceded this quarter. Over the past six quarters, the S&P 500 earnings trajectory defied conventional economic gravity. While traditional manufacturing, commercial real estate, and discretionary retail sectors struggled under the weight of restrictive monetary policy, a handful of dominant technology conglomerates sustained double-digit earnings growth. Cloud compute architecture expansion, digital advertising resurgences, and an unprecedented gold rush in generative artificial intelligence created an insulated ecosystem of high-margin profitability.
However, financial markets operate on the relentless calculus of marginal change. As corporations report actual results for the third quarter, the rate of earnings acceleration is visibly tapering off. Oppenheimer’s quantitative strategists point out that while absolute earnings figures remain robust on a historical basis, the year-over-year growth velocity is reverting to historical averages. This deceleration is not merely a statistical artifact; it represents a fundamental transition in how capital markets price forward-looking risk.
The core issue lies in the diminishing returns of massive upfront infrastructure investments. Throughout late 2023 and the entirety of 2024, Wall Street cheered as major technology titans committed tens of billions of dollars to data center expansion, specialized semiconductor procurement, and power grid securing. Today, corporate treasurers and chief financial officers are demanding hard evidence of enterprise ROI. When enterprise software clients and cloud consumers delay digital transformation projects or demand pricing concessions, the top-line revenue growth of hardware and platform providers inevitably feels the pinch.
Financial Metrics and Sector Performance Divergence
A granular review of current market data underscores the stark bifurcation occurring beneath the surface of the headline S&P 500 index. While the index as a whole continues to trade near historic valuation multiples—hovering at a forward price-to-earnings ratio well above the 25-year historical average—the earnings contribution from outside the technology sector reveals deep fragility.
| Market Segment / Metric | Q3 2023 Actual | Q3 2024 Estimated | YoY Growth Trajectory | Primary Valuation Driver |
|---|---|---|---|---|
| S&P 500 Aggregate EPS Growth | +4.3% | +8.1% | Decelerating from Q2 peak | Blend of Tech resilience & margin cost-cuts |
| Information Technology Sector | +18.5% | +15.2% | Noticeable compression | Hardware demand stabilization & AI ROI scrutiny |
| Communication Services | +24.1% | +12.8% | Sharp normalization | Digital ad spend maturation & streaming saturation |
| Cyclical & Industrial Sectors | -2.1% | +1.4% | Sluggish recovery | Interest rate sensitivity & supply chain stabilization |
| Forward P/E Ratio (S&P 500) | 21.4x | 22.8x | Expanded multiple risk | Liquidity concentration in mega-caps |
As illustrated in the comparative breakdown above, while technology and communication services continue to post positive year-over-year earnings growth, the rate of expansion has dropped significantly compared to previous quarters. This statistical cooling validates Oppenheimer’s thesis: the easy phase of the post-pandemic profit recovery is officially over, and companies must now fight for every basis point of margin expansion.
Industry & Market Implications: Winners, Losers, and Systemic Risk
The cooling of S&P 500 profit momentum carries profound implications for institutional portfolio construction, asset allocation models, and corporate treasury management. When dominant growth engines begin to sputter, market liquidity undergoes a violent reallocation process.
The Winners: Quality Factors, Defensive Yields, and Operational Discipline
In an environment where top-line revenue growth is harder to come by, institutional capital naturally migrates toward quality factors—specifically companies possessing strong balance sheets, pristine credit ratings, and robust free cash flow yields. Corporations that have prioritized operational efficiency, supply chain risk mitigation, and disciplined capital allocation over speculative expansion are outperforming. Furthermore, sectors traditionally viewed as defensive havens, such as healthcare, select consumer staples, and regulated utilities, are experiencing renewed institutional sponsorship as portfolio managers hedge against valuation compression in high-beta tech equities.
The Losers: Overleveraged Growth and Capital-Intensive Innovators
Conversely, businesses heavily dependent on external debt financing, continuous venture capital funding, or aggressive valuation multiples are feeling the pinch. Smaller-cap technology firms and enterprise software providers that fail to demonstrate immediate operating leverage are witnessing severe multiple contractions. For these entities, the bar for maintaining market confidence has been raised drastically; missing quarterly guidance by even a narrow margin is routinely punished with double-digit equity sell-offs.
Frequently Asked Questions (People Also Ask)
Why is Oppenheimer signaling a slowdown in S&P 500 profit momentum?
Oppenheimer’s analysis highlights a normalization of earnings growth across the technology sector, which has served as the primary engine for the broader stock market. As massive capital expenditures in artificial intelligence and cloud infrastructure face stricter scrutiny regarding enterprise ROI, the rate of profit acceleration is moderating toward historical averages.
How does a cooling tech sector impact the broader S&P 500 index?
Because the S&P 500 is market-capitalization-weighted, a small cohort of mega-cap technology companies accounts for an outsized percentage of the index's total earnings and market value. When tech earnings momentum slows, it drags down aggregate index performance, forcing a reassessment of equity valuations across all sectors.
What role do interest rates and macro factors play in current corporate earnings?
Sustained higher interest rates increase the cost of capital for corporate borrowers, pressuring profit margins, particularly for capital-intensive and cyclical businesses. Additionally, shifting consumer credit dynamics and regulatory compliance costs are constraining net income growth outside of the technology sector.
How should institutional investors adapt their risk mitigation strategies?
Institutional allocators are increasingly focusing on fundamental quality metrics, such as free cash flow generation, low debt-to-equity ratios, and proven operational efficiency. Rotating capital away from extended growth valuations and toward defensive sectors or diversified dividend-paying equities is becoming a primary risk mitigation tactic.
Future Outlook: Strategic Milestones to Watch
Looking ahead, the trajectory of the S&P 500 will depend heavily on corporate execution throughout the fourth-quarter reporting cycle and upcoming macroeconomic data releases. Key milestones for institutional monitors include:
- Hyperscaler Capital Expenditure Updates: Continued transparency from major cloud providers regarding the monetization timelines of generative AI deployments and enterprise software integration.
- Federal Reserve Monetary Policy Path: Future interest rate adjustments and their direct transmission mechanism into corporate borrowing costs and commercial lending liquidity.
- Consumer Resilience Indicators: Holiday retail sales figures and credit card delinquency trends, which will dictate revenue health for discretionary and consumer staples sectors.
- Regulatory Compliance Shifts: Anticipated changes in antitrust enforcement, data privacy laws, and international trade policies that could impact global technology supply chains.
Ultimately, Oppenheimer’s diagnostic serves as a necessary wake-up call for equity markets. While the corporate sector remains fundamentally resilient, the era of frictionless, tech-driven earnings expansion has given way to a more disciplined, selective market environment where operational execution and verified financial returns reign supreme.