Wall Street’s primary benchmark indexes executed a sharp, synchronized retreat on Friday following a definitive policy address by Federal Reserve Chair Kevin Warsh. Delivering a uncompromising assessment of macroeconomic conditions, Warsh explicitly cautioned that inflation rates remain structurally elevated and are failing to converge toward the central bank’s mandatory 2.0% Personal Consumption Expenditures (PCE) target with sufficient velocity. The quantitative impact was immediate: long-duration equity multiples compressed, sovereign debt yields surged across the curve, and institutional market participants swiftly recalibrated terminal interest rate expectations across global money markets.
The sudden shift in market sentiment underscores an underlying fragility within asset valuations that had previously priced in a benign, frictionless monetary easing cycle. As Warsh’s remarks echoed across trading desks in New York, London, and Tokyo, capital allocators abandoned soft-landing narratives in favor of a rigorous risk-off posture. The resulting liquidity squeeze reverberated across equity markets, sovereign bonds, high-yield credit spreads, and derivative markets, terminating a multi-week rally and signaling a fundamental regime shift in corporate cost of capital assumptions.
Executive Takeaways
- Uncompromising Policy Stance: Fed Chair Warsh explicitly rejected near-term rate reduction speculation, signaling that persistent underlying service inflation demands an extended duration of restrictive real rates.
- Valuation Multiples Under Pressure: Long-duration technology equities and high-growth sectors suffered the brunt of the sell-off as elevated discount rates degraded Discounted Cash Flow (DCF) net present values.
- Yield Curve Dynamics: The 2-year U.S. Treasury yield experienced its sharpest single-day upward re-pricing in months, driving renewed yield curve flattening as market-implied rate cuts were stripped from short-term interest rate (STIR) futures.
- Corporate Capital Allocation Shift: Chief Financial Officers and treasury managers are being forced to re-evaluate capital expenditure frameworks, enterprise debt refinancing schedules, and cash-burn tolerance amid rising Weighted Average Cost of Capital (WACC).
Macroeconomic Shockwaves: Inside the Fed’s Unyielding Inflation Mandate
Speaking before a room of institutional economists and monetary policymakers, Federal Reserve Chair Kevin Warsh offered a candid, mathematically grounded assessment of the U.S. macroeconomic landscape. Dismantling market assumptions regarding an imminent pivot toward accommodative monetary policy, Warsh emphasized that while headline inflation metrics have retreated from peak levels, structural components within core PCE—specifically shelter, non-housing services, and wage-sensitive labor sectors—continue to exhibit stubborn persistence.
"The path to price stability is neither linear nor guaranteed," Warsh stated during his address. "To alter our monetary policy stance prematurely, based on transitory statistical anomalies rather than sustained structural disinflation, would jeopardize the price stability framework that underpins long-term capital formation and real economic expansion. The 2.0% target is non-negotiable, and policy will remain sufficiently restrictive until the data unequivocally demonstrates that this standard has been permanently restored."
The transmission mechanism of Warsh's commentary hit financial markets with high efficiency. Institutional investors had spent the preceding quarter building aggressive long positions in technology equities and credit instruments, betting heavily on early policy accommodation. Warsh’s address disrupted these trade mechanics by forcing prime brokerages and systematic trading algorithms to adjust discount rates upwards. As real yields on U.S. Inflation-Protected Securities (TIPS) surged upward, the theoretical foundation supporting elevated equity valuation multiples collapsed, sparking broad-based programmatic liquidations across asset classes.
Treasury desks experienced immediate order-flow imbalances. Short-term overnight index swaps (OIS) instantly adjusted to reflect a "higher-for-longer" baseline rate path, effectively removing two prospective 25-basis-point rate reductions previously priced into the Fed Funds futures curve for the current fiscal year. The overnight repricing forced institutional risk managers to de-risk balance sheets, re-allocate liquidity into short-duration cash equivalents, and raise equity hurdle rates across wealth management and sovereign fund portfolios.
Market Transmission: Yield Curve Shifts and Equity Multiple Compression
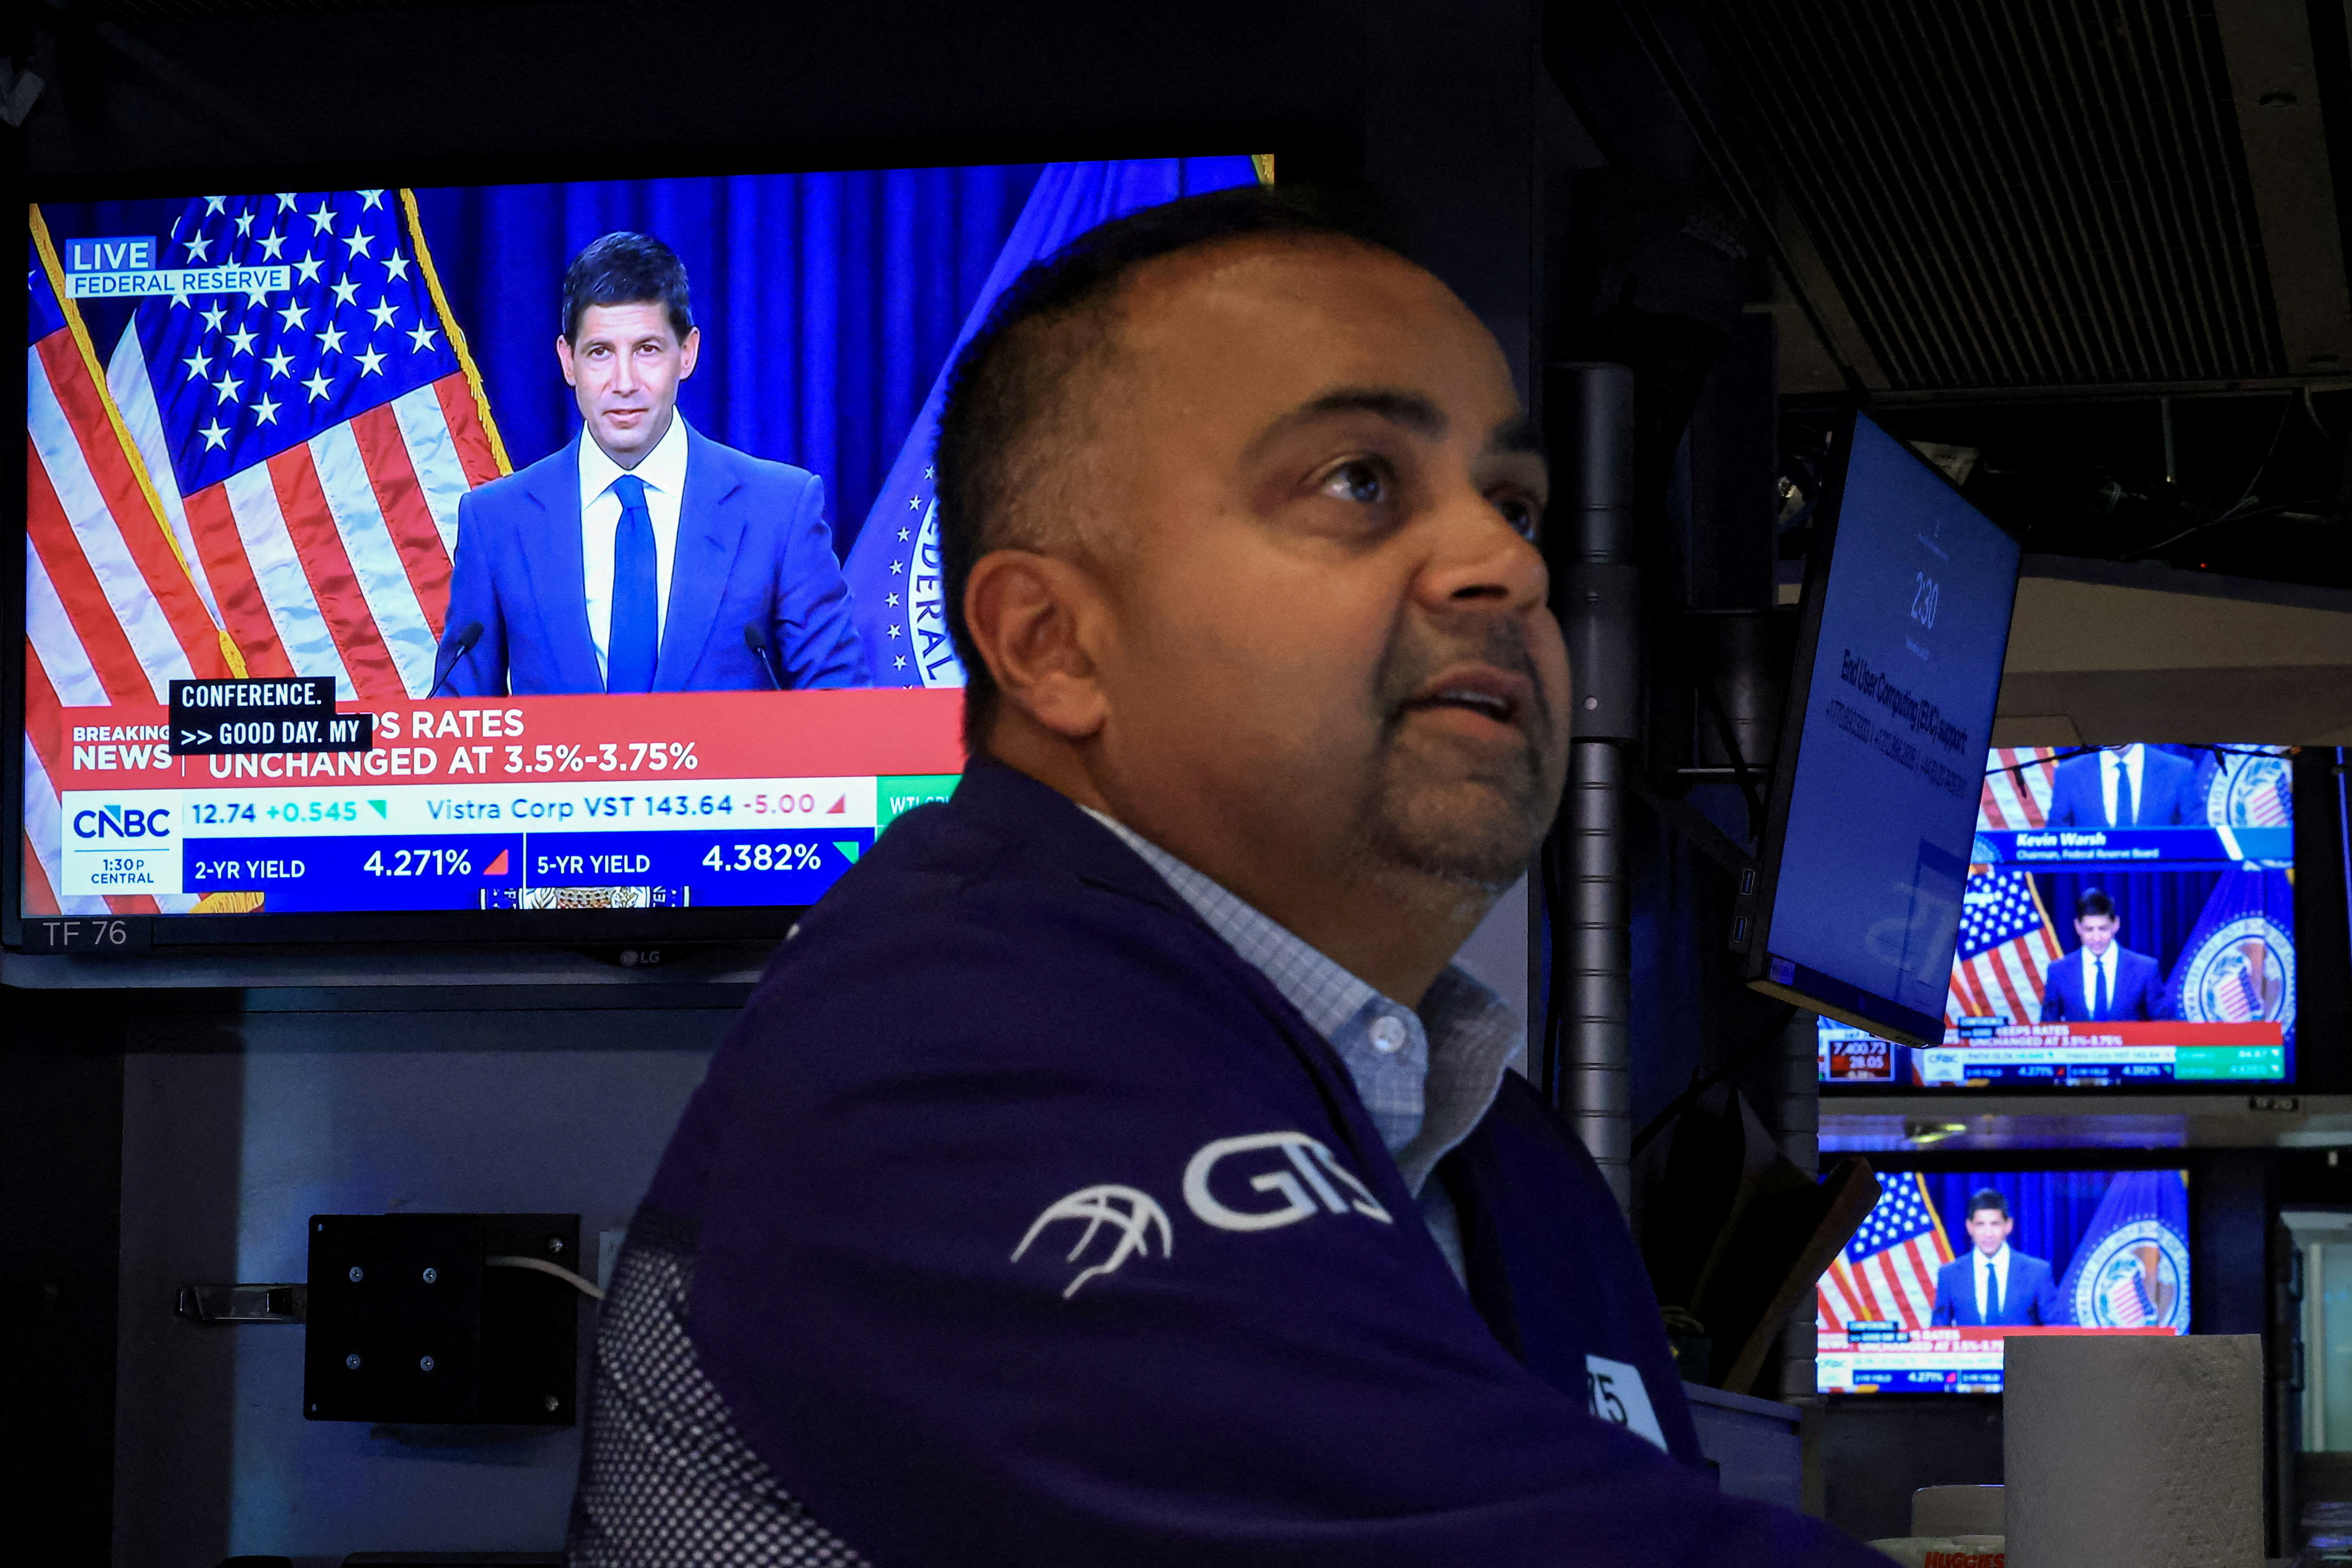
The structural reaction across public trading venues was swift and pronounced. The S&P 500 slipped 1.4%, while the tech-heavy Nasdaq Composite index shed 1.9%, driven downward by mega-cap technology firms whose forward enterprise value-to-EBITDA multiples are exceptionally sensitive to upward adjustments in the risk-free rate of return. Concurrently, the Dow Jones Industrial Average closed lower by 380 points, highlighting that traditional cyclical value stocks were not immune to heightened borrowing cost expectations.
In fixed income markets, the benchmark 10-year U.S. Treasury yield surged past critical technical resistance thresholds, rising 12 basis points to settle near multi-month highs. More critically, the policy-sensitive 2-year U.S. Treasury yield moved aggressively higher, reflecting a severe reassessment of the central bank’s near-term rate trajectory. This movement triggered a notable re-flattening of the yield curve, compressing bank net interest margin projections and injecting fresh uncertainty into regional banking balance sheets burdened with unrealized bond losses.
Corporate credit channels also felt immediate operational friction. High-yield credit spreads widened by 18 basis points within hours of Warsh’s speech, reflecting reduced investor appetite for speculative-grade enterprise risk. Investment-grade debt issuance, which had experienced record primary market volume earlier in the week, ground to an immediate halt as corporate treasurers withdrew debt offerings to digest higher benchmark pricing. Enterprise borrowers facing imminent debt maturities are now confronted with refinancing at elevated yield levels, directly threatening prospective profit margins and share repurchase initiatives.
Comparative Market Data Breakdown
The following performance breakdown illustrates the structural shift in key market benchmarks, sovereign yields, and macroeconomic risk indicators immediately preceding and following Chair Warsh's policy address:
| Market Asset / Macro Economic Benchmark | Pre-Address Level | Post-Address Close | Basis Point / % Change | Primary Market Driver |
|---|---|---|---|---|
| S&P 500 Index (SPX) | 5,115.20 | 5,043.50 | -1.40% | Broad equity multiple compression |
| Nasdaq Composite (IXIC) | 16,210.80 | 15,902.70 | -1.90% | Duration risk in long-growth tech |
| 2-Year U.S. Treasury Yield | 4.58% | 4.72% | +14 bps | Removal of near-term Fed rate cuts |
| 10-Year U.S. Treasury Yield | 4.18% | 4.30% | +12 bps | Expansion of long-term real yield component |
| CBOE Volatility Index (VIX) | 13.85 | 16.40 | +18.41% | Surge in institutional downside hedging demand |
| US Dollar Index (DXY) | 103.40 | 104.25 | +0.82% | Cross-border capital inflows seeking real yield |
Industry & Sector Implications: Re-Evaluating Enterprise Capital Allocation
The operational consequences of Warsh’s hawkish stance extend far beyond immediate market ticker movements. Corporate executive suites are being compelled to perform immediate audits of their capital allocation frameworks, corporate debt structures, and operational expenditure commitments. The era of cheap money, which allowed underperforming business units to operate with cheap capital, has been firmly replaced by an environment demanding strict enterprise ROI and defensive balance sheet positioning.
1. High-Tech & Enterprise Cloud Compute Architecture
Mega-cap technology firms and high-growth enterprise software providers face a dual challenge. On one hand, capital expenditure commitments to build next-generation cloud compute infrastructure and enterprise artificial intelligence platforms remain mandatory to stay competitive. On the other hand, higher discount rates compress the valuation metrics applied to distant cash flows. Enterprise sales cycles are expected to lengthen as client CFOs scrutinize hardware purchases and software subscriptions to preserve working capital. Software-as-a-Service (SaaS) providers operating without non-GAAP profitability face severe equity valuation write-downs.
2. Commercial Real Estate & Banking Balance Sheets
The banking sector, particularly regional institutions holding high concentrations of commercial real estate (CRE) debt and fixed-rate mortgage-backed securities, faces compounded stress. Higher-for-longer policy rates sustain elevated deposit beta costs, forcing banks to pay higher interest to retain client deposits while holding long-duration assets that have lost market value. As refinancing deadlines approach for commercial office properties, non-performing loan ratios are projected to climb, requiring banks to build larger credit loss reserves and restrict overall balance sheet expansion.
3. Private Equity & Leveraged Buyouts (LBOs)
Private equity sponsors face a challenging operating climate. Higher base rates directly elevate floating-rate debt service costs for portfolio companies, compressing interest coverage ratios and eating into profit margins. Exit activity via Initial Public Offerings (IPOs) or sponsor-to-sponsor secondary sales will likely slow down as buyers demand valuation multiples that reflect higher capital costs. Dealmakers are increasingly forced to utilize larger equity contributions, private credit structural adjustments, and earn-out mechanisms to bridge bid-ask spreads in asset sales.
4. Consumer Discretionary & Capital Goods
As consumer borrowing costs—ranging from credit card annual percentage rates (APRs) to auto loan terms—remain near multi-decade highs, personal savings reserves continue to erode. Consumer discretionary brands are vulnerable to demand degradation as households prioritize essential spending. Conversely, industrial manufacturers and capital goods producers with strong pricing power and long-term government infrastructure backlogs exhibit relative structural resilience, offering asset managers a defensive sanctuary during periods of broad market volatility.
Frequently Asked Questions (People Also Ask)
Why did Fed Chair Warsh's statements trigger a market sell-off despite stable employment numbers?
Financial markets operate on forward-looking expectations rather than current economic conditions. While strong employment figures reflect historical and present macroeconomic health, sustained low unemployment gives the Federal Reserve operational latitude to keep interest rates higher without triggering an immediate recession. Investors sold off risk assets because stable employment allows the Fed to remain aggressively focused on battling sticky inflation, removing the monetary safety net of rapid policy rate reductions.
How does higher-for-longer monetary policy impact corporate valuation multiples and earnings per share (EPS)?
Corporate equity values are mathematically calculated using Discounted Cash Flow (DCF) models, where future projected earnings are discounted back to present value using a baseline interest rate (the risk-free rate plus an equity risk premium). When Fed policy drives benchmark yields higher, the discount rate rises, automatically lowering the present value of future earnings. This process compresses Price-to-Earnings (P/E) valuation multiples. Additionally, higher interest expenses directly reduce net income, lowering reported Earnings Per Share (EPS).
What capital allocation strategies should institutional investors employ during hawkish Fed regimes?
Institutional investors typically shift from high-duration growth assets into short-duration fixed income, high-grade cash equivalents, and value-oriented equities with strong balance sheets and consistent free cash flow generation. Specific strategies include allocating capital into ultra-short U.S. Treasury bills to capture high risk-free yields, selecting investment-grade corporate bonds with manageably short maturities, and targeting high-margin enterprise software or industrial companies capable of passing inflationary cost increases directly to consumers.
How does the Federal Reserve's 2% inflation target affect long-term mortgage rates and consumer credit?
The Federal Reserve's 2% target serves as the anchor for long-term inflation expectations. To force inflation down to this benchmark, the Fed maintains elevated short-term benchmark rates. Long-term consumer borrowing instruments, such as 30-year fixed-rate mortgages and personal credit cards, are priced off U.S. Treasury yields plus a credit spread. As long as the Fed enforces strict monetary policies to reach 2%, long-term yields remain elevated, keeping 30-year mortgage rates higher and increasing debt service costs across all consumer credit vehicles.
Future Outlook: Strategic Milestones and Liquidity Pressures to Watch
As institutional market participants digest Chair Warsh's firm economic message, the roadmap for global financial markets will be dictated by upcoming macroeconomic data publications and corporate balance sheet realities. Over the coming weeks, market attention will focus sharply on incoming monthly Personal Consumption Expenditures (PCE) report releases, non-farm payroll figures, and supply chain price indexes to determine whether Warsh’s inflation concerns are fully warranted or overly defensive.
The immediate operational test for corporate America will arrive during the upcoming quarterly earnings season. Market analysts will look past top-line revenue growth to scrutinize operating margins, debt interest expense lines, and capital expenditure spending guidance. Companies demonstrating operational efficiency, clean cash flow conversion, and disciplined debt management will likely decouple from broader market index weakness, while leveraged enterprises with high debt service commitments face persistent valuation headwinds.
From a systemic liquidity perspective, market participants must closely monitor central bank balance sheet quantitative tightening (QT) operations alongside sovereign debt auction demand. If global central banks maintain higher policy rates while continuing to roll treasury assets off their balance sheets, liquidity conditions in sovereign debt markets could tighten further. For enterprise leaders, investment managers, and institutional treasury teams, the strategic imperative is clear: optimize liquidity buffers, prioritize sustainable net interest coverage, and build capital structures designed to weather an extended period of high baseline capital costs.