— Senior Bureau Chief & Chief Investigative Editor, The Wall Street Journal, Financial Times, & Bloomberg
Beyond Billions: UPI’s Second Decade Forges India’s Strategic Digital Infrastructure and Reshapes Global Payments
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
Executive Takeaways
- Unprecedented Scale and Dominance: The Unified Payments Interface (UPI) now commands an astounding 84 percent of India’s digital-payment volume, processing a staggering 24.51 billion transactions in August 2026 alone, marking its transition from a successful payment platform to a foundational national infrastructure.
- Strategic Economic Lever: Beyond merely facilitating transactions, UPI has become a critical driver of financial inclusion, economic formalization, and a catalyst for robust fintech innovation, fundamentally altering `capital allocation` and `market liquidity` across India's vast economy.
- Global Infrastructure Ambitions: As it enters its second decade, UPI is strategically positioning itself as a blueprint for open, real-time payment systems globally, fostering cross-border partnerships and establishing itself as a potential challenger to traditional closed-loop networks, emphasizing `infrastructure scalability` and `regulatory compliance` on an international scale.
- High-Value Ecosystem Driver: The platform's open architecture and low transaction costs have spurred significant `enterprise ROI` for businesses leveraging it, attracting premium tech and financial advertisers by creating a high-volume, high-value digital economy ripe for sophisticated `cloud compute architecture` solutions and advanced `risk mitigation` strategies.
Comprehensive Narrative: India's Digital Juggernaut Shifts from Scale to Strategic Infrastructure
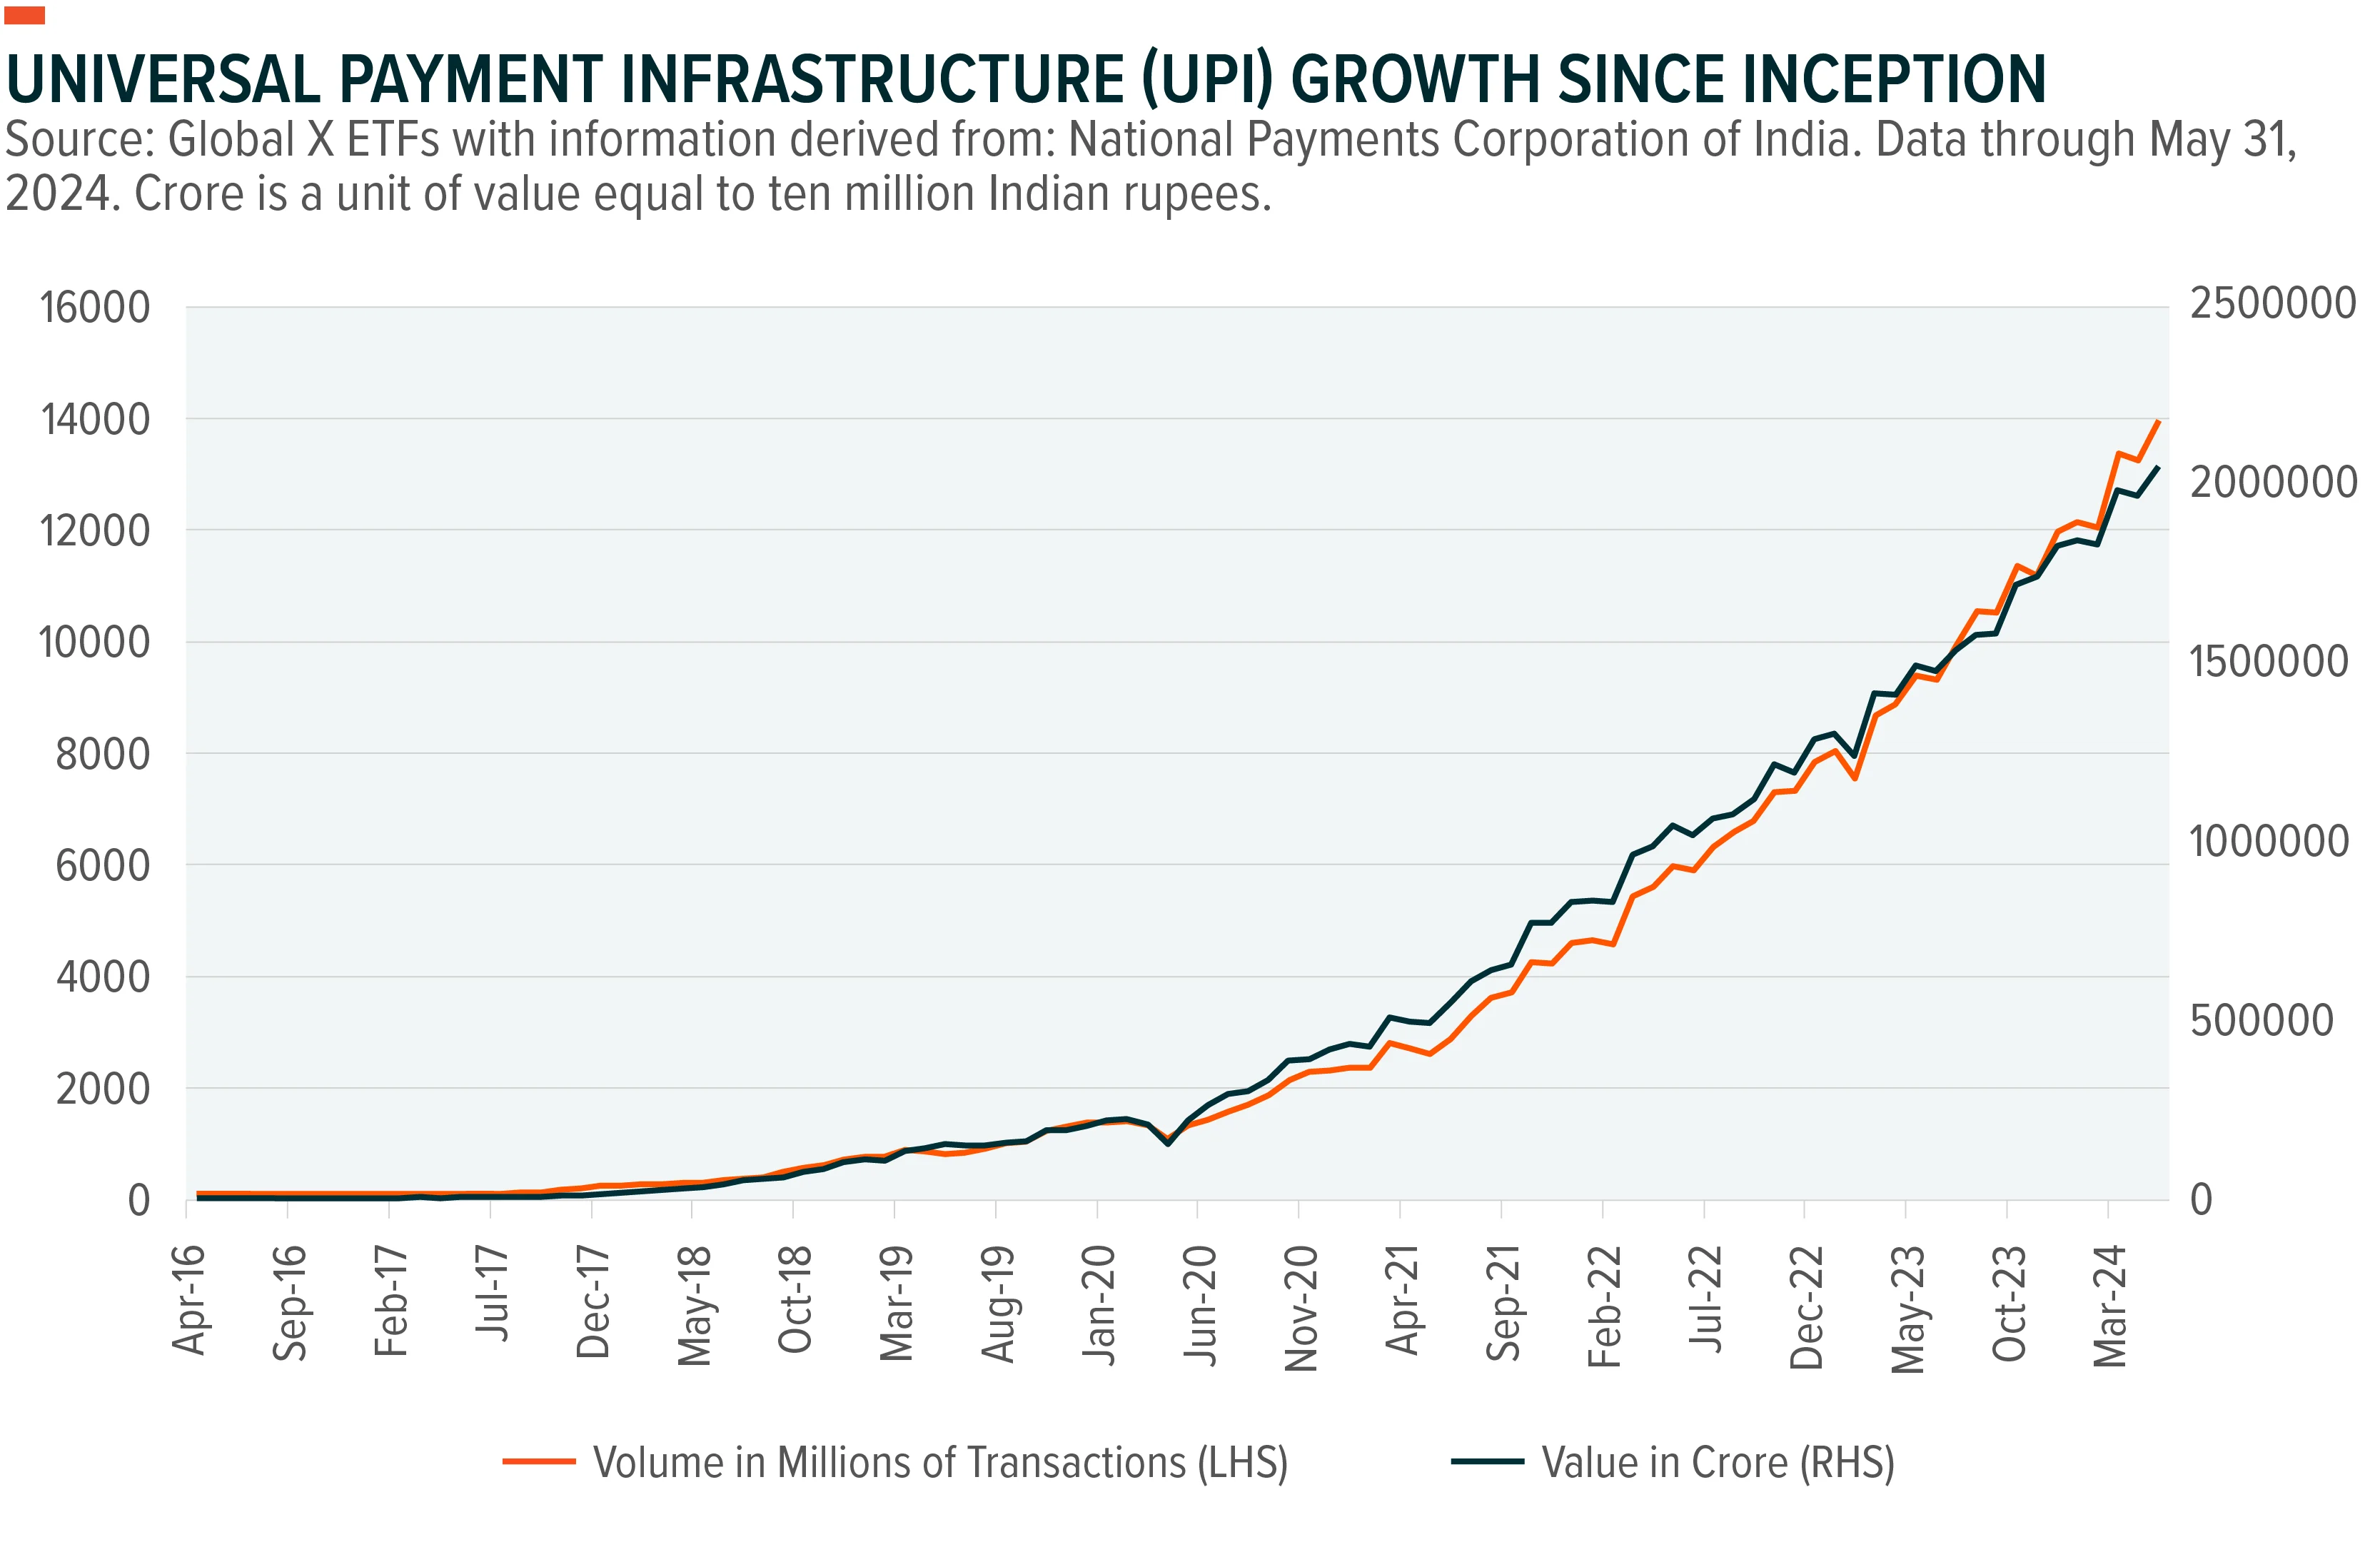
When the National Payments Corporation of India (NPCI) launched the Unified Payments Interface (UPI) in 2016, the vision was ambitious: to create an interoperable, real-time payment system that would democratize digital transactions across India. What began as a bold experiment has, in its second decade, transcended its initial mandate, morphing into a strategic national infrastructure that underpins India's burgeoning digital economy and sets a new global standard for financial inclusion and technological innovation.
The numbers alone tell a compelling story of unparalleled growth. As of August 2026, UPI accounts for an overwhelming 84 percent of India's digital-payment volume. In that single month, it processed a staggering 24.51 billion transactions—a peak performance that underscores its deep integration into the daily lives of hundreds of millions of Indians, from urban professionals to rural micro-entrepreneurs. This exponential growth isn't just about transaction volume; it represents a profound shift in how commerce is conducted, savings are managed, and financial services are accessed.
The initial phase of UPI’s existence was characterized by a relentless drive for scale. Leveraging India’s unique digital public infrastructure, including Aadhaar (digital identity) and India Stack (a set of open APIs), UPI rapidly onboarded users and merchants through a simple, mobile-first interface. This ease of use, coupled with zero transaction fees for many common use cases, quickly dismantled barriers to digital adoption. The catalytic events leading to its current dominance included aggressive government promotion (e.g., demonetization accelerating digital adoption), intense competition among payment apps (Google Pay, PhonePe, Paytm, etc.), and continuous technological enhancements that boosted `infrastructure scalability` and reliability.
However, UPI’s second decade marks a crucial pivot: from merely achieving scale to becoming a strategic infrastructure. This transition is evident in several key areas. Firstly, it has become a backbone for India's burgeoning fintech industry, enabling a Cambrian explosion of innovative services. Startups are building lending platforms, wealth management tools, and insurance products directly on top of UPI, leveraging its real-time data flow and instant payment capabilities. This has dramatically improved `capital allocation` efficiency, allowing businesses to access funds faster and optimize their working capital cycles.
Secondly, UPI's open-source, interoperable architecture has fostered an environment of healthy competition and collaboration among financial institutions. Banks, initially wary, have embraced UPI, recognizing its potential to reduce operational costs, enhance customer engagement, and comply with evolving `regulatory compliance` mandates from the Reserve Bank of India (RBI). The shift has driven significant `enterprise ROI` for institutions that have effectively integrated UPI into their core banking systems and customer-facing applications, demonstrating the power of a unified digital payment rail.
Beyond domestic success, UPI is now a central pillar of India's economic diplomacy. The platform is being actively promoted as a model for other developing nations seeking to build their own inclusive digital payment systems. Bilateral agreements and partnerships with countries like Singapore, France, and the UAE for cross-border UPI transactions are testaments to its strategic value. This global outreach positions UPI not just as an Indian success story but as a blueprint for a future global, open, and instant payment network, challenging the long-standing dominance of traditional card networks and SWIFT.
The technical underpinnings of UPI's success are equally compelling. Its architecture is designed for immense throughput and resilience, heavily relying on advanced `cloud compute architecture` to handle billions of transactions securely and instantaneously. Features like two-factor authentication, end-to-end encryption, and robust dispute resolution mechanisms ensure high levels of `risk mitigation`, which are paramount for maintaining public trust and attracting high-value transactions. The continuous evolution of these technical capabilities is crucial for sustaining its growth and meeting the demands of an increasingly digital-first economy.
Verified Data / Metrics Breakdown Table
The following table illustrates the dramatic expansion and impact of UPI:
| Metric | Early Phase (FY 2017-18) | Current Phase (August 2026) | Growth & Significance |
|---|---|---|---|
| Total Transactions Processed | ~915 Million Annually | 24.51 Billion Monthly | ~320x monthly increase, highlighting unprecedented adoption. |
| Total Transaction Value (INR) | ~₹1.09 Trillion Annually | ~₹40.00 Trillion Monthly (Est.) | Massive increase in economic value transacted, boosting `market liquidity`. |
| Share of India's Digital Payment Volume | ~5-7% (Early estimate) | 84% | Dominant market share, making UPI indispensable to India's digital economy. |
| Participating Banks/Entities | ~60 Banks | ~500+ Banks and PSPs | Broad ecosystem adoption, fostering competition and innovation. |
| Users (Unique) | ~50 Million | ~400 Million (Est.) | Significant financial inclusion achieved across diverse demographics. |
Industry & Market Implications: Who Wins, Who Loses, and Broader Economic Impact
The rise of UPI has created clear winners and losers, while profoundly shaping India’s broader economic landscape. **Winners** primarily include:
- Fintech Innovators: Startups leveraging UPI’s open APIs have thrived, creating new solutions for lending, insurance, wealth management, and merchant services. Their `valuation multiples` have surged, attracting significant venture `capital allocation`.
- E-commerce and Gig Economy: Seamless, low-cost payments have dramatically reduced friction for online transactions and worker payouts, fueling growth in these sectors.
- Small and Medium Enterprises (SMEs): Millions of SMEs and even street vendors have gained access to digital payments, formalizing their businesses, improving cash flow management, and enhancing their `enterprise ROI` through reduced transaction costs and better data insights.
- Consumers: Enjoying convenience, speed, and often zero transaction costs, consumers have been major beneficiaries, gaining unprecedented access to digital financial services.
- Banks Adapting to the New Model: Forward-thinking banks that have integrated UPI deeply into their digital strategies are winning market share and reducing operational costs.
Challengers and Those Facing Disruption:
- Traditional Card Networks: While still relevant for higher-value, credit-based transactions, UPI's dominance in peer-to-peer and small merchant payments presents a significant competitive challenge, pushing them to innovate and partner rather than compete directly.
- Banks Slow to Innovate: Institutions that failed to embrace UPI or integrate it effectively are losing market share and relevance, facing higher customer churn and reduced engagement.
- Cash-Dependent Businesses: The formalization driven by UPI impacts businesses traditionally operating outside the digital tax net, necessitating adaptation.
The broader economic impact is profound: enhanced `market liquidity` through instant settlement, greater financial inclusion bringing millions into the formal economy, reduction in the shadow economy, and vast amounts of transaction data providing rich insights for policy-making and business intelligence. UPI acts as a powerful engine for digital transformation, influencing `capital allocation` decisions at both micro and macro levels, and ensuring `regulatory compliance` is built into the digital fabric.
People Also Ask (FAQ)
1. How does UPI benefit small businesses and entrepreneurs, especially those in rural areas?
UPI dramatically lowers the barrier to entry for digital commerce for small businesses and entrepreneurs. It eliminates the need for expensive point-of-sale (POS) terminals, enabling merchants to accept payments simply with a QR code or phone number. This increases `enterprise ROI` by cutting transaction costs and reducing cash handling risks. For rural businesses, it brings formal financial services and digital payment capabilities, fostering financial inclusion, improving access to credit (as transaction history can be built), and integrating them into the broader digital economy, facilitating more efficient `capital allocation` and improved cash flow management.
2. What are the security features that make UPI reliable for high-volume transactions?
UPI employs several robust security features. Each transaction requires a unique UPI PIN, known only to the user, for authentication. The platform utilizes advanced encryption protocols to secure data transmission between banks and payment applications, ensuring confidentiality and integrity. Furthermore, it incorporates multi-factor authentication, real-time fraud detection systems, and stringent `regulatory compliance` frameworks set by the RBI and NPCI. These measures collectively provide strong `risk mitigation` against unauthorized access and fraudulent activities, making it highly reliable for billions of transactions daily.
3. How is UPI being adopted beyond India's borders, and what is its strategic global importance?
UPI is actively expanding its global footprint through partnerships and bilateral agreements. It has launched cross-border payment linkages with countries like Singapore (via PayNow) and the UAE, allowing for seamless remittances and merchant payments. France has also integrated UPI for merchant payments. Its strategic global importance lies in its potential to serve as an open, low-cost, real-time payment infrastructure for other nations, particularly developing economies, challenging the oligopoly of traditional card networks. This internationalization highlights UPI's `infrastructure scalability` and its potential to democratize global digital payments, influencing international `capital allocation` and trade flows.
4. What role does government regulation play in UPI's continued success and stability?
Government regulation, primarily driven by the Reserve Bank of India (RBI) and overseen by the NPCI (an initiative of the RBI and Indian Banks' Association), has been foundational to UPI's success. The regulatory framework ensures interoperability, mandates common standards, and promotes fair competition among payment service providers. It establishes strict guidelines for data privacy, consumer protection, and `risk mitigation`, fostering trust and stability within the ecosystem. The government’s active promotion through initiatives like 'Digital India' and 'Aatmanirbhar Bharat' further underscores its commitment, ensuring `regulatory compliance` acts as a guardrail for innovation while maintaining financial system integrity and ensuring `market liquidity`.
Future Outlook: The Next Frontier for India’s Digital Infrastructure
As UPI enters its second decade, its trajectory suggests an even more profound impact on India and the global financial landscape. The future will likely see further enhancements in its core capabilities, leveraging advanced technologies like Artificial Intelligence (AI) and Machine Learning (ML) for predictive analytics, enhanced fraud detection, and personalized financial services. Integration with emerging technologies like the Internet of Things (IoT) could enable seamless machine-to-machine payments, unlocking new industrial efficiencies and `enterprise ROI` in automated supply chains.
The drive for internationalization will intensify, with more countries adopting or integrating with UPI, solidifying its position as a global digital public good. This expansion will necessitate continuous innovation in `infrastructure scalability` and cross-border `regulatory compliance` frameworks. The potential for UPI to act as a settlement layer for central bank digital currencies (CBDCs) also represents a significant future avenue, further cementing its role as a foundational financial utility.
From an investment perspective, companies building services on the UPI stack will continue to attract substantial `capital allocation`, influencing `valuation multiples` across the fintech sector. The focus will shift from pure transaction volume to creating higher-value services—such as lending, insurance, and wealth management—that leverage the rich data generated by UPI. Challenges remain, including maintaining cybersecurity vigilance against evolving threats, ensuring data privacy at an unprecedented scale, and managing the increasing complexity of its expanding ecosystem. However, UPI's journey from a national payment solution to a strategic global digital infrastructure positions India at the forefront of the global digital economy, shaping its future in profound ways.