The AI House of Cards: How Wall Street’s $2 Trillion Tech Bet Puts the US Economy at Risk
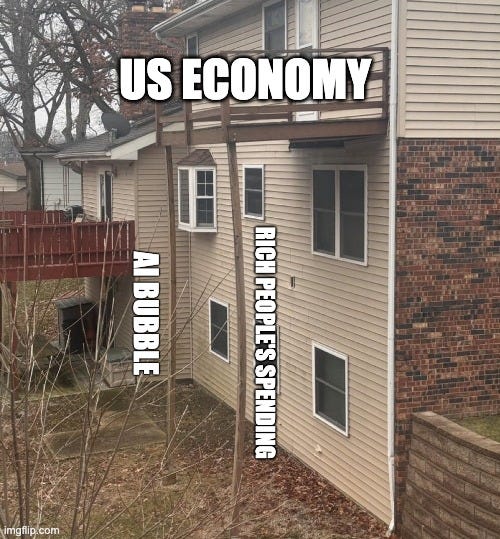
DOHA, Qatar — The euphoria that has propelled global stock markets to record highs over the last two years is facing its most critical stress test yet. At the prestigious Qatar Economic Forum, a sobering consensus emerged among sovereign wealth funds, institutional debt pioneers, and macroeconomic strategists: the global economy is dangerously over-indexed on an Artificial Intelligence (AI) boom that is beginning to look like a wobbly house of cards.
As tech giants continue to deploy hundreds of billions of dollars into AI infrastructure with highly speculative paths to profitability, the margin for error has shrunk to zero. If the massive capital expenditure (CapEx) cycle fails to yield a corresponding wave of enterprise software revenue, the fallout will not merely be confined to Silicon Valley. It threatens to trigger a profound correction in the S&P 500, freeze debt markets, and disrupt a fragile US economic expansion already grappling with structural interest rate pressures.
The Great CapEx Disconnect: Billions Spent, Millions Earned
The core of the systemic risk lies in a stark mathematical disparity. The world’s largest technology companies—including Microsoft, Alphabet, Meta, and Amazon—are on track to spend an estimated $200 billion on AI-related capital expenditures, primarily hardware like Nvidia’s Blackwell chips, fiber optic networks, and massive hyper-scale data centers.
However, the actual enterprise monetization of generative AI remains in its infancy. For every dollar spent on infrastructure, the tech ecosystem currently generates only a fraction of that in direct software-as-a-service (SaaS) or cloud-computing revenue. This gap has raised alarm bells among risk-averse institutional investors.
The AI Spending Gap: Projected 2025 CapEx vs. GenAI Revenue Run Rate
| Technology Giant | Est. 2025 AI CapEx ($ Billions) | Est. Direct GenAI Revenue ($ Billions) | CapEx-to-Revenue Disparity Ratio |
|---|---|---|---|
| Microsoft | $58.0 | $12.5 | 4.6x |
| Alphabet (Google) | $48.0 | $6.2 | 7.7x |
| Meta Platforms | $40.0 | $3.5 | 11.4x |
| Amazon (AWS) | $52.0 | $8.0 | 6.5x |
This massive imbalance suggests that if Fortune 500 enterprises slow down their adoption of costly AI subscriptions due to budget constraints or underwhelming productivity gains, tech giants will be forced to drastically write down their infrastructure investments. A sudden contraction in AI spending would immediately slam the brakes on semiconductor supply chains, drag down the broader indices, and shock consumer confidence.
Howard Marks Warns of Monetary Distortions and the Need for Central Bank Restraint
Adding a crucial layer of macroeconomic caution to the forum, Howard Marks, the legendary co-founder of Oaktree Capital Management, addressed the structural state of the markets. Known for his prescient memos on market cycles, Marks argued that the era of ultra-easy monetary policy—which originally fostered the speculative environment where unproven tech valuations could thrive—must come to a permanent end.
Speaking on the sidelines of the event, Marks emphasized that he wants to see a "less activist central bank." His thesis is clear: when central banks intervene too aggressively by slashing interest rates to near-zero and printing money, they artificially suppress the cost of capital. This leads to the misallocation of resources, driving capital into speculative assets (such as unproven AI ventures) rather than productive, cash-flowing enterprises.
"A less activist central bank allows the free market to discover the natural price of money. When interest rates are kept at healthier, historically normal levels, investors are forced to be disciplined. We desperately need that discipline back in the market today."
— Howard Marks, Co-Founder of Oaktree Capital Management
Without the safety net of a "Fed Put"—the expectation that the Federal Reserve will quickly cut rates at the first sign of market trouble—the highly leveraged AI trade looks far more vulnerable. If a correction occurs, the Fed may not rush to rescue equity valuations, leaving over-leveraged tech firms and their creditors to bear the full weight of the downside.
How an AI Correction Could Cascade Through the US Economy
The systemic danger of the AI trade is its unprecedented concentration in the major stock indices. The S&P 500’s performance has become heavily reliant on just a handful of technology companies. A sharp correction in these mega-cap names would have immediate, far-reaching consequences:
- The Wealth Effect Reverse: Tens of millions of American retail investors and pension funds are heavily exposed to tech indices. A 20% to 30% correction in tech giants would instantly erase trillions of dollars in household wealth, dampening consumer spending—the primary engine of the US economy.
- Tightening Credit Markets: Many secondary tech firms and startups rely on venture debt and corporate bond issuances. A freeze in tech valuations would lead to a broader widening of credit spreads, making debt refinancing prohibitively expensive across multiple sectors of the economy.
- Sovereign and Private Equity Pullback: Sovereign wealth funds, particularly in the Middle East, have poured billions into AI ventures. A market shakeout would force these massive institutional allocators to pivot back to defensive assets, drying up liquidity for early-stage enterprise innovation.
The Outlook: A Healthy Correction or a Systemic Crisis?
While the phrase "house of cards" evokes fears of a 2008-style financial meltdown, many seasoned analysts believe a near-term shakeout is actually a necessary prerequisite for long-term economic health. Much like the Dot-Com crash of 2000 laid the groundwork for the highly profitable, internet-driven economy of the 2010s, an AI correction could weed out speculative froth while leaving robust infrastructure intact.
The coming quarters will be decisive. Investors must closely monitor corporate earnings calls for signs of genuine enterprise software adoption. If companies cannot prove that AI is meaningfully boosting their bottom lines, the market will likely impose its own discipline—exactly as Howard Marks envisioned—by forcing a painful, but ultimately healthy, repricing of the modern digital economy.
Frequently Asked Questions (FAQ)
Why is the current AI boom compared to a "wobbly house of cards"?
The comparison stems from the massive imbalance between capital expenditure and realized revenue. Tech giants are spending hundreds of billions of dollars on AI microchips and data centers, but businesses are not yet purchasing generative AI software at a scale that justifies these unprecedented infrastructure investments. If monetization lags too long, a wave of capital write-downs could trigger a broader market collapse.
What does Howard Marks mean by a "less activist central bank," and why does it matter for AI?
Howard Marks advocates for central banks (like the Federal Reserve) to step back and let the free market determine interest rates, rather than constantly intervening with rate cuts or quantitative easing. For the AI market, a less activist central bank means there will be no cheap money rescue package if the AI bubble bursts. Investors will have to absorb their own losses, enforcing much-needed financial discipline on Wall Street.