Executive Takeaways
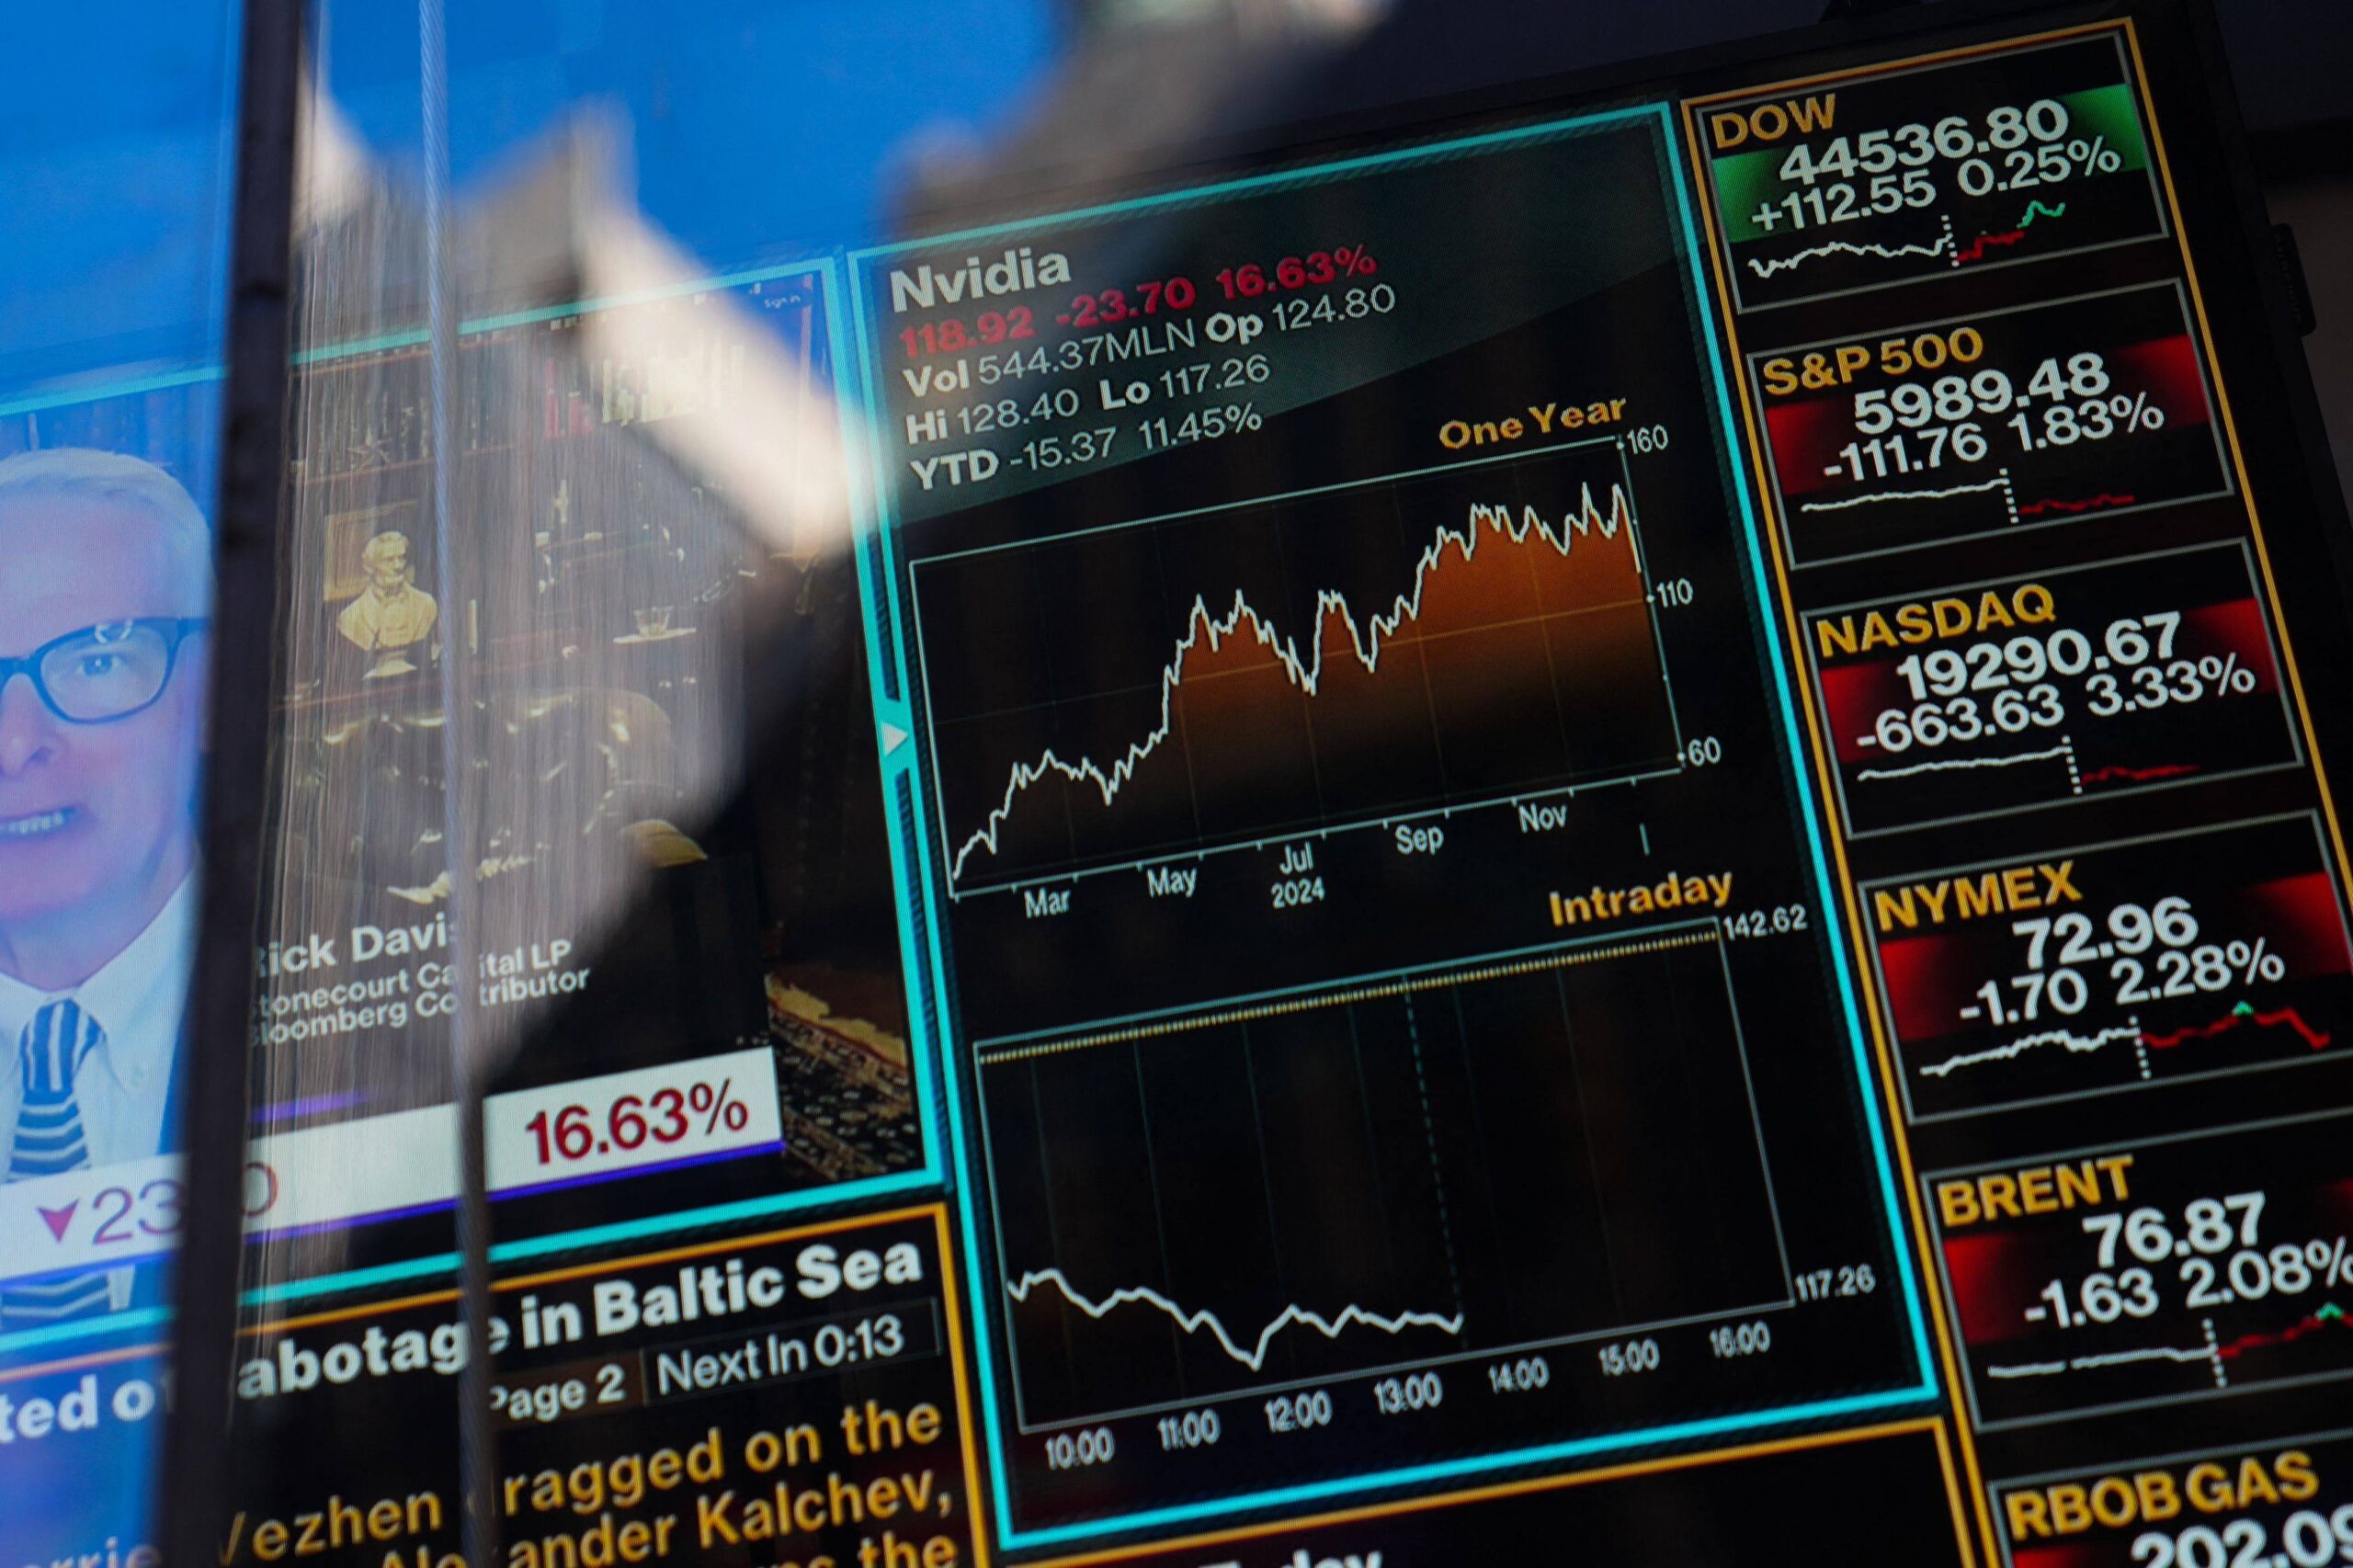
- Wall Street Contagion: Overnight losses in U.S. mega-cap technology stocks have triggered a sharp downward revision in risk appetite, directly threatening Asian indices across Tokyo, Seoul, and Taipei.
- The Valuation Reckoning: Institutional capital allocation is rapidly shifting away from high-multiple artificial intelligence plays as institutional investors demand immediate enterprise ROI rather than speculative infrastructure scalability.
- Semiconductor Supply Chain Vulnerability: Foundry giants and memory chip manufacturers face intense downward pressure as cloud compute architecture budgets encounter corporate spending scrutiny.
- Liquidity & Risk Mitigation: Portfolio managers are aggressively rebalancing portfolios, executing tactical risk mitigation strategies, and rotating capital into defensive, cash-generative asset classes.
TOKYO, SEOUL, HONG KONG — Asian equity markets are bracing for a turbulent session following a punishing sell-off on Wall Street, where a broad-based technology rout exposed deepening market anxiety regarding the commercial viability and timeline of artificial intelligence monetization. Futures contracts across major Asian exchanges point to an aggressive downward opening. The correction marks a critical psychological inflection point for global investors who have long treated the artificial intelligence secular growth narrative as immune to traditional macroeconomic gravity.
As trading desks across financial capitals digest the overnight carnage in U.S. indices, the central narrative has shifted decisively from boundless technological optimism to cold capital allocation reality. Institutional asset managers are no longer willing to reward capital expenditure outlays that lack clear, near-term pathways to profitability. This abrupt reassessment of valuation multiples is hitting the world’s most critical technology supply chains hardest, reverberating directly through the silicon fabrication hubs of Taiwan, South Korea, and Japan.
The Catalyst: Wall Street’s Tech Re-Pricing and the Death of Blind Expansion
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The immediate trigger for the Asian market pullback stems from a coordinated wave of institutional profit-taking and long liquidation on U.S. exchanges. Major cloud hyperscalers and semiconductor flagships experienced outsized losses as equity analysts began questioning whether current multi-billion-dollar infrastructure scalability investments will yield acceptable returns on invested capital (ROIC) within a reasonable horizon.
For months, the market shrugged off soaring capital expenditure figures, operating under the assumption that first-mover advantage in generative AI justified any price tag. However, rising corporate borrowing costs, persistent macroeconomic uncertainty, and a lack of blockbuster enterprise application rollouts have altered the calculus. Institutional investors are executing aggressive risk mitigation protocols, unwinding leveraged positions, and forcing a systemic re-pricing of technology sector valuation multiples.
This U.S.-led correction acts as an immediate gravitational pull on Asian equities. The region's markets are inextricably linked to global technology cycles, functioning as the physical backbone for the hardware, memory, and advanced packaging required to fuel the AI boom. When Wall Street catches a cold, Asian semiconductor foundries and contract manufacturers experience a severe operational chill.
The Semiconductor Supply Chain Under Siege
The epicenter of the impending Asian market downturn lies within the semiconductor complex. Companies that dominate global contract manufacturing, advanced lithography, and high-bandwidth memory (HBM) are seeing their order books subjected to unprecedented scrutiny by institutional equity researchers.
Capital expenditure cycles in the technology sector are notoriously cyclical. When enterprise customers delay software upgrades or temper their cloud compute architecture expansion plans, the shockwaves travel upstream with compounding velocity. Foundries operating at ultra-high utilization rates suddenly face the risk of inventory gluts if end-market demand fails to absorb the massive volume of silicon currently leaving cleanrooms.
Furthermore, regulatory compliance headwinds and geopolitical friction regarding advanced technology exports continue to overlay structural risk onto an already fragile market liquidity environment. Investors are no longer giving management teams the benefit of the doubt regarding future earnings visibility.
| Index / Region | Primary Vulnerability | Key Catalyst Driving Downside | Market Sentiment |
|---|---|---|---|
| Nikkei 225 (Japan) | Chip-testing equipment & robotics | Global tech valuation compression & USD/JPY volatility | Bearish / Defensive |
| KOSPI (South Korea) | Memory chips (DRAM & HBM) | Over-reliance on hyperscaler hardware spending | Highly Vulnerable |
| TAIEX (Taiwan) | Advanced semiconductor foundry | U.S. mega-cap tech earnings fatigue & AI ROI anxiety | Severe Sell-Off Pressure |
| Hang Seng (Hong Kong) | Chinese mega-cap tech & platforms | Macroeconomic headwinds & global risk-off contagion | Cautious / Risk-Off |
Market Implications: Winners, Losers, and Capital Rotation
As quantitative hedge funds and long-only institutional managers aggressively de-gross their portfolios, capital is fleeing high-multiple growth equities in favor of safety. Understanding the structural shift requires examining how different market segments are reacting to the current environment:
- The Losers — High-Beta Tech and Speculative Hardware: Companies trading at forward price-to-earnings multiples disconnected from historical averages are facing severe margin compression. Firms heavily reliant on debt-financed capital expenditure programs are seeing their cost of capital soar, forcing management to delay expansion initiatives.
- The Winners — Defensive Sectors and Cash-Generative Industrials: Capital exiting technology is finding a temporary home in defensive sectors such as utilities, healthcare, and consumer staples. Furthermore, well-capitalized financial institutions with strong net interest margins and robust balance sheets are outperforming speculative growth proxies.
- Macroeconomic Fallout: Currency markets are also feeling the friction. As risk-off sentiment takes hold, regional currencies face depreciation pressures against safe-haven flows, forcing central banks across emerging and developed Asia to monitor foreign exchange stability closely while balancing domestic monetary policy objectives.
Frequently Asked Questions (People Also Ask)
Why are Asian stocks falling in tandem with U.S. technology shares?
Asian equity markets, particularly in export-heavy economies like Taiwan, South Korea, and Japan, form the foundational manufacturing and supply chain backbone for global technology giants. When U.S. mega-cap tech stocks experience valuation corrections due to AI spending anxiety, institutional investors immediately reduce exposure to upstream semiconductor foundries and hardware suppliers, triggering synchronized regional sell-offs.
What is driving institutional anxiety over artificial intelligence investments?
Institutional investors are increasingly concerned about the timeline and scale of enterprise ROI. While technology companies have poured staggering sums into data center infrastructure and cloud compute architecture, the monetization timeline for enterprise applications has proven longer and more capital-intensive than initially projected, leading to a reassessment of lofty valuation multiples.
How are portfolio managers executing risk mitigation in this volatile market?
Portfolio managers are actively de-grossing portfolios by trimming high-beta growth positions, rotating capital into defensive, cash-generative sectors (such as utilities and financials), increasing cash allocations, and utilizing derivative overlay strategies to hedge against further downside volatility in technology indices.
Are semiconductor stocks facing a structural downturn or a cyclical correction?
Market analysts generally categorize the current movement as a valuation re-pricing and cyclical digestion phase rather than a permanent structural collapse. Long-term secular demand for advanced computing remains intact, but the market is abruptly purging speculative excess and demanding concrete evidence of disciplined capital allocation from industry leaders.
Future Outlook: Milestones and What to Watch Next
Looking ahead, the trajectory of Asian equities will depend heavily on upcoming corporate earnings releases from major U.S. and regional technology flagships. Institutional capital allocation decisions will be dictated by hard data regarding enterprise software adoption rates, forward-looking capital expenditure guidance, and gross margin resilience.
Key milestones for market participants to monitor include upcoming quarterly earnings reports from leading memory chip producers, statements from major cloud hyperscalers regarding their next-generation data center spending budgets, and macroeconomic indicators reflecting global liquidity conditions. Until corporate management teams can convincingly demonstrate tangible enterprise ROI from their massive artificial intelligence investments, equity markets are likely to remain hyper-sensitive, volatile, and prone to swift, sentiment-driven corrections.