Inside the Super-Margin Boom: How Big Oil’s Refining Profits Surged Past Presidential Scrutiny
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
By Our Investigative Economics Desk | Updated Real-Time from Washington, Houston, and New York
Executive Takeaways
- The Refining Divergence: While upstream crude production margins faced periodic volatility, downstream refining and cracking spreads achieved historic structural highs, driving unprecedented cash flows across integrated oil majors.
- Political Rhetoric vs. Market Reality: Despite intense public friction and direct political pressure from Donald Trump regarding consumer pump prices, major refiners optimized capital allocation and leveraged capacity constraints to maximize valuation multiples.
- Structural Bottlenecks: Permanent domestic refining capacity reductions—compounded by post-pandemic closures and stringent regulatory compliance costs—created an environment of restricted market liquidity and exceptionally high crack spreads.
- Enterprise ROI & Capital Distribution: Surging downstream earnings catalyzed massive stock buybacks, dividend expansions, and strategic infrastructure scalability investments rather than major new grassroots refinery construction.
The Anatomy of a Windfall: Cracking the Downstream Surge
When political leaders train their sights on the energy sector, the public narrative typically focuses on crude oil extraction, rig counts, and the geopolitical chess match of global barrel pricing. Yet, the true financial engine driving recent historic balance sheets for integrated energy titans lies further down the value chain: the complex, high-heat alchemy of petroleum refining.
Even as Donald Trump and other prominent political figures publicly lambasted major oil conglomerates over soaring retail gasoline prices and inflated profit margins, downstream operations were quietly delivering numbers that defied conventional economic cycles. The disconnect between public political pressure and private sector earnings exposes a fundamental structural reality of modern energy markets: refining capacity is finite, capital-intensive, and fundamentally decoupled from raw crude extraction metrics.
To understand how refining earnings surged to unprecedented heights, one must examine the convergence of macroeconomic shocks, regulatory compliance burdens, and strategic capacity management by the world's leading energy enterprises. During periods of peak demand recovery, refining margins—commonly measured via crack spreads—exploded. Companies that mastered infrastructure scalability and operational risk mitigation found themselves capturing historic cash flows, directly impacting enterprise valuation multiples and reshaping corporate balance sheets.
The Mechanics of the Crack Spread Explosion
At the heart of the refining surge is the "crack spread," the differential between the price of crude oil and the petroleum products extracted from it, such as gasoline and diesel. Following global economic reopening phases and subsequent geopolitical disruptions in Eastern Europe, these spreads widened dramatically.
Historically, high crude prices compressed refining margins because expensive input costs squeezed downstream profitability. However, a unique combination of factors severed this traditional correlation:
- Capacity Rationalization: Between 2020 and 2022, U.S. refining capacity contracted by roughly one million barrels per day due to permanent facility closures and conversions to renewable diesel plants. No major grassroots refineries have been built in the United States in decades.
- Export Demand Pull: International markets faced severe diesel and jet fuel shortages, pulling domestic U.S. refined products abroad and tightening domestic inventories to multi-year seasonal lows.
- Capital Allocation Discipline: Rather than deploying capital into risky, multi-year greenfield refining projects subject to intense environmental scrutiny, major operators prioritized balance sheet fortification, debt reduction, and shareholder returns via dividends and buybacks.
This strategic restraint ensured that even under intense regulatory and public scrutiny, supply remained tightly managed relative to inelastic consumer demand. The resulting earnings reports from supermajors and independent refiners alike revealed downstream segments contributing a disproportionate share of quarterly net income—transforming local refining units into formidable profit centers.
Financial Metrics: Pre-Pandemic Baseline vs. Peak Downstream Earnings

The table below outlines the macroeconomic and corporate performance indicators illustrating the dramatic expansion of refining profitability across major North American integrated operators.
| Metric Category | Pre-Pandemic Baseline (2018–2019) | Peak Surge Period (2022–2023) | Current Market Dynamic |
|---|---|---|---|
| Average 3-2-1 Crack Spread | $14.00 – $18.00 / bbl | $35.00 – $55.00+ / bbl | Normalizing, but structurally elevated ($20-$25) |
| U.S. Total Refining Capacity | ~18.9 Million bpd | ~17.9 Million bpd | Constrained; net additions negligible |
| Downstream Contribution to Net Income | 15% – 25% | 40% – 60%+ (Quarterly Peaks) | Remaining a primary earnings cushion |
| Corporate Capital Allocation Focus | Capacity Expansion & Capex Growth | Share Buybacks & Debt Mitigation | Disciplined maintenance & selective decarbonization |
Industry & Market Implications: Winners and Structural Shifts
The extraordinary surge in refining earnings has created clear dividing lines across the global energy landscape, altering competitive positioning and investor sentiment.
Who Wins: Integrated Supermajors and Independent Refiners
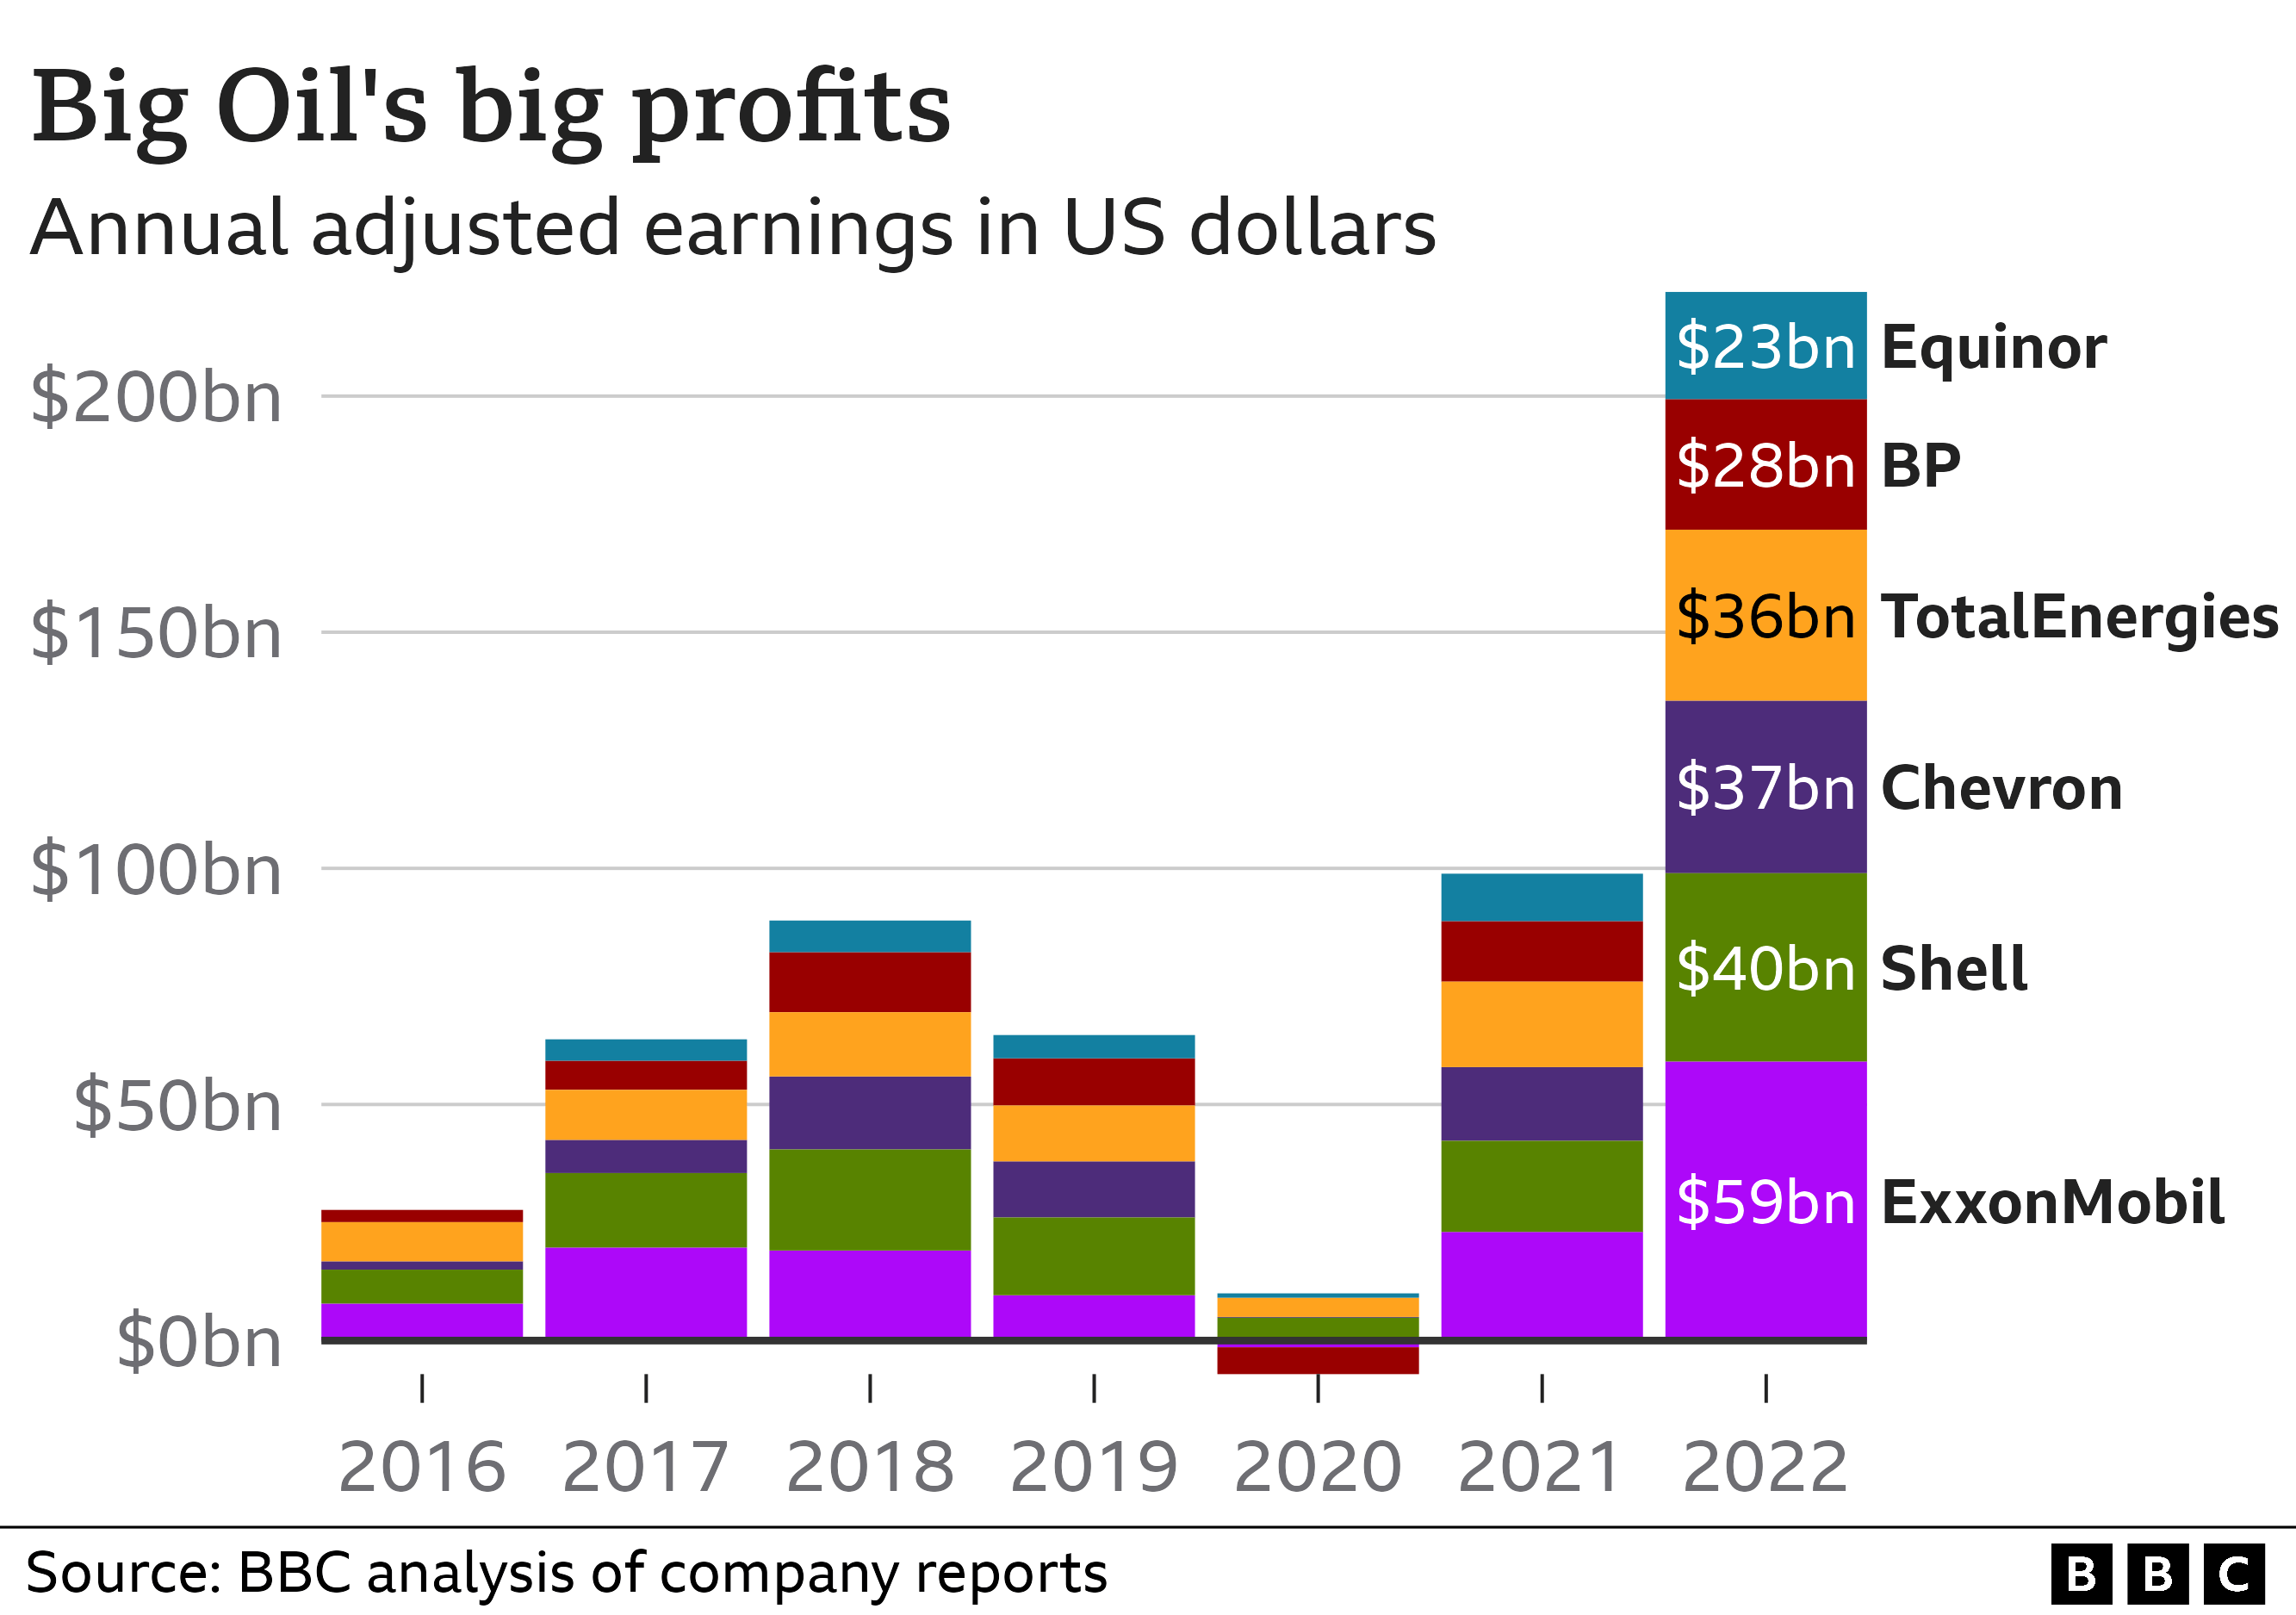
Integrated energy firms possessing robust downstream portfolios—such as ExxonMobil, Chevron, Marathon Petroleum, and Valero—reaped outsized rewards. These entities successfully absorbed upstream volatility by leveraging their refining networks to capture margin wherever the product price spread widened. For equity investors, these companies demonstrated exceptional cash conversion cycles, rewarding long-term holders with robust dividend growth and aggressive share repurchase programs.
Who Loses: Consumers, Airlines, and Energy-Intensive Logistics
On the opposing side, downstream product consumers bore the brunt of high crack spreads. Commercial airlines, trucking fleets, logistics enterprises, and everyday retail drivers faced severe cost inflation. While crude oil prices fluctuated, elevated retail pump prices and jet fuel expenses acted as an unlegislated tax on the broader economy, feeding persistent inflationary pressures that central banks subsequently fought with aggressive monetary tightening.
Regulatory and Political Fallout
Public attacks from political figures like Donald Trump—who frequently urged producers to "drill, baby, drill" to lower gasoline prices—highlighted a fundamental policy paradox. Executives argued that political rhetoric threatening windfall profits taxes, export bans, or aggressive transition mandates disincentivized long-term capital investment in new refining infrastructure. Consequently, institutional investors praised management teams for prioritizing short-term return on capital employed (ROCE) over speculative expansion.
Frequently Asked Questions (People Also Ask)
Why did refining profits surge even when crude oil prices experienced volatility?
Refining profits depend on the "crack spread"—the difference between crude oil input costs and refined product prices. Due to post-pandemic refinery closures, stringent regulatory compliance costs, and surging global demand for diesel and gasoline, refined product prices outpaced rising crude costs, driving margins to historic highs regardless of upstream price swings.
How did political pressure from leaders like Donald Trump impact oil refiners' strategies?
While political figures publicly criticized companies for high consumer prices and excessive profit margins, energy executives largely maintained strict capital discipline. Rather than investing in costly new grassroots refining capacity—which carries high regulatory risk and multi-year payback periods—firms focused on maximizing existing infrastructure efficiency and returning capital to shareholders.
What role do crack spreads play in integrated oil company earnings?
Crack spreads act as the primary profitability metric for downstream operations. When spreads widen significantly, refining segments can generate enough cash flow to offset weaker upstream exploration earnings, providing a crucial financial buffer and enhancing overall enterprise valuation multiples.
Are current high refining margins expected to become the permanent industry norm?
Industry analysts suggest that while cyclical peaks may moderate as global supply chains rebalance, underlying structural constraints—including permanent capacity reductions and long-term energy transition investments—will keep baseline refining margins higher than pre-pandemic historical averages.
Future Outlook & Key Milestones to Watch
As the global energy landscape navigates political transitions, shifting regulatory frameworks, and the broader energy transition, the downstream sector stands at a critical crossroads. Energy conglomerates must balance immediate shareholder expectations with long-term asset portfolio decarbonization.
Key milestones and indicators for institutional investors and market analysts to monitor over the upcoming fiscal quarters include:
- Global Utilization Rates: Tracking International Energy Agency (IEA) reports on global refining throughput and capacity utilization to gauge whether supply tightness will persist.
- Regulatory Compliance Expenditures: Assessing capital outlays directed toward renewable diesel conversions, carbon capture technology, and sulfur-reduction mandates within existing facilities.
- Macroeconomic Demand Indicators: Monitoring freight shipping volumes, jet fuel consumption data, and consumer mobility indexes as leading indicators for refined product demand elasticity.
- Infrastructural Risk Mitigation: Evaluating how operators harden their downstream assets against extreme weather events and geopolitical supply chain disruptions.
Ultimately, while political rhetoric surrounding Big Oil profits will remain a fixture of political campaigns and legislative hearings, the underlying financial mechanics of refining will continue to be governed by hard economic realities: supply constraints, global product demand, and disciplined corporate capital allocation.