Executive Takeaways
- The Fed's Holding Pattern: The US Federal Reserve's decision to maintain the federal funds rate at 3.75%–4% signals persistent caution against sticky domestic inflation, forcing a re-evaluation of global capital allocation models.
- Indian Equities in the Crosshairs: Dalal Street faces prolonged valuation compression and heightened volatility as Foreign Institutional Investors (FIIs) weigh the risk-adjusted returns of emerging markets against high-yielding US Treasury securities.
- Sector-Specific Divergence: While capital-intensive infrastructure and high-beta midcaps experience liquidity pressures, export-oriented IT services and specialized enterprise tech architectures find strategic leverage amid fluctuating currency valuations.
- Strategic Risk Mitigation: Institutional portfolio managers are aggressively recalibrating asset allocation, prioritizing balance sheet resilience, infrastructure scalability, and stringent regulatory compliance to weather foreign capital outflows.
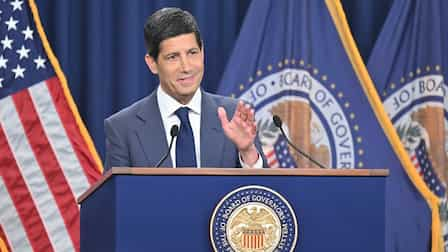
The global monetary architecture stands at a critical juncture. Following the latest policy directive from Eccles Building, the US Federal Reserve has officially opted to hold benchmark interest rates steady in the 3.75%–4% range. For executive boardrooms, institutional asset managers, and cross-border capital allocators, this decision is far more than a routine central banking pause; it is a profound macroeconomic stress test. As sticky inflation prints and resilient employment data force Federal Reserve Chairman Jerome Powell to maintain a higher-for-longer stance, the reverberations are hitting emerging markets with surgical precision—none more so than India.
For Indian financial markets, which have long feasted on abundant global liquidity and secular domestic consumption growth, the Fed’s hold introduces a complex matrix of risks and tactical opportunities. While Indian macroeconomic fundamentals remain structurally robust, the mechanics of international capital flows dictate that higher US yields siphon liquidity away from risk assets in developing economies. As equity benchmarks grapple with increased intraday volatility and foreign institutional outflows, investors are forced to re-examine valuation multiples, corporate earnings visibility, and debt-servicing costs across every major sector.
The Macroeconomic Catalyst: Decoding the Fed's Hold Strategy
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the downstream effects on the Bombay Stock Exchange (BSE) and the National Stock Exchange (NSE), one must first dissect the rationale behind Washington’s monetary posture. The decision to keep the federal funds rate anchored at 3.75%–4% stems from a complex balancing act. US core consumer price index (CPI) metrics have proven stubbornly resistant to aggressive disinflationary trends, driven by resilient wage growth and robust consumer spending.
In response, the Federal Open Market Committee (FOMC) has adopted an uncompromising risk-management framework. Premature monetary easing risks unanchoring inflation expectations, compelling central bankers to err on the side of restraint. However, this posture creates a distinct friction point for global liquidity. When risk-free US Treasury yields remain elevated, global portfolios undergo a massive compositional shift. Institutional capital allocators find short-term US sovereign debt increasingly attractive, drawing liquidity out of high-beta emerging markets.
For India—a capital-hungry economy that relies on foreign direct investment (FDI) and portfolio flows to finance its current account dynamics—this tighter global liquidity channel acts as an immediate macroeconomic constraint. The cost of external commercial borrowings (ECBs) for Indian corporations scales upward, forcing CFOs to pivot toward domestic debt markets, where local banking liquidity is already facing tightening credit-deposit ratios.
Verified Data & Metrics Breakdown

A rigorous quantitative analysis of the macroeconomic vectors currently influencing US-India monetary dynamics reveals the following comparative metrics:
| Economic Indicator | Current US Baseline | Current Indian Equivalent | Strategic Implication for Markets |
|---|---|---|---|
| Benchmark Policy Rate | 3.75% – 4.00% | 6.50% (Repo Rate) | Maintains a positive interest rate differential, though narrowing US-India spreads pressure the Rupee. |
| Headline Inflation (YoY) | ~3.1% | ~5.1% | Persistent food and commodity price shocks keep RBI on an extended defensive hold. |
| FII Flow Trajectory (YTD) | Net Inflows (Domestic) | Episodic Outflows | Foreign portfolio capital rotation drives intermittent equity volatility across large-caps. |
| 10-Year Sovereign Yield | ~4.35% | ~7.10% | Elevated US yields cap aggressive multiple expansion in Indian growth stocks. |
Industry & Market Implications: Who Wins, Who Loses
The Federal Reserve’s hawkish pause is far from a monolithic event; its impact cuts across industrial sectors with varying degrees of intensity. Market participants must look beyond headline index movements to evaluate sector-specific vulnerabilities and structural tailwinds.
The Vulnerable Sectors: Valuation Compression and Capital Constraints
- High-Beta Midcaps and Smallcaps: Retail-heavy segments that experienced speculative surges during periods of loose global monetary policy are particularly vulnerable. As institutional liquidity tightens, these stocks face severe multiple contraction.
- Capital-Intensive Infrastructure & Real Estate: Developers and infrastructure conglomerates relying on syndicated foreign loans face escalating financing costs. Project execution timelines may stretch as capital allocation prioritizes balance sheet deleveraging over aggressive expansion.
- Consumer Discretionary: Urban demand resilience is being tested by domestic inflation and higher borrowing costs. Discretionary retail sectors face compressed operating margins as input costs remain sticky.
The Resilient Beneficiaries: Enterprise Resilience and Export Leverage
- Information Technology and Enterprise Services: Indian IT majors derive a significant share of their revenue from US corporate clients. A resilient US economy—even one grappling with high rates—sustains technology spending on cloud compute architecture, digital transformation, and enterprise ROI optimization. Furthermore, currency fluctuations often provide a protective earnings buffer.
- Pharmaceuticals and Specialty Chemicals: Regulated market exporters with robust US pipelines benefit from defensive domestic positioning and steady dollar-denominated cash flows.
- Banking and Financial Services (Large-Cap): Well-capitalized private sector banks with diversified asset books and robust deposit franchises are successfully navigating the credit squeeze, leveraging strong corporate balance sheets to capture high-quality loan growth.
Frequently Asked Questions (People Also Ask)
1. Why does a US Federal Reserve rate hold directly impact Indian stock market volatility?
When the Fed holds rates at elevated levels, US Treasury yields remain attractive to global institutional investors. This triggers a reallocation of capital away from emerging markets like India into safer US dollar-denominated assets. Consequently, Foreign Institutional Investors (FIIs) pull capital out of Indian equities, causing sudden bouts of selling pressure and heightened intraday volatility on the NSE and BSE.
2. How does the Fed's monetary policy affect the USD/INR exchange rate?
An extended Fed pause preserves a tight interest rate differential in favor of the US dollar. As global capital flows toward US assets, demand for the dollar strengthens, putting depreciation pressure on the Indian Rupee (INR). A weaker rupee increases import bills for crude oil and electronics, which in turn feeds into domestic inflation and impacts corporate margins.
3. Should Indian retail and institutional investors alter their asset allocation strategies now?
Institutional portfolio managers are currently prioritizing risk mitigation over aggressive growth. Strategies involve shifting capital toward high-quality large-cap equities with fortress balance sheets, defensive sector exposure (IT, Pharma, FMCG), and high dividend yields. Investors are advised to focus on companies with strong free cash flow generation and low leverage rather than speculative high-beta growth plays.
4. What role does domestic liquidity play in cushioning Indian markets against US shocks?
Unlike previous decades, Indian markets possess a powerful domestic shock absorber: systematic investment plans (SIPs) and robust domestic institutional investor (DII) inflows. Consistent monthly domestic retail allocations into mutual funds provide structural market depth, helping absorb heavy FII sell-offs and cushioning equity benchmarks against sharp downward corrections.
Future Outlook: Strategic Milestones to Watch
As the global economy navigates this protracted monetary plateau, executive leadership teams and investment committees must maintain rigorous surveillance of key macroeconomic triggers. The trajectory of Indian markets over the next two to four quarters will depend on several critical milestones:
- US Labor Market and Inflation Prints: Future FOMC pivots hinge entirely on sustained cooling in US employment and core CPI metrics. Any unexpected resurgence in inflation will cement a higher-for-longer narrative, extending valuation pressures across emerging markets.
- RBI Monetary Policy Stance: The Reserve Bank of India’s response to domestic growth-inflation dynamics will dictate local debt market yields. Maintaining an optimal interest rate differential is essential for mitigating capital flight and stabilizing the Indian Rupee.
- Corporate Earnings Visibility: As Indian listed entities report quarterly earnings, markets will heavily penalize firms exhibiting margin compression and escalating debt-servicing costs. Conversely, enterprises demonstrating superior operational efficiency, digital infrastructure scalability, and stringent regulatory compliance will command premium valuations.
- FII Flow Reversal Triggers: Watch for inflection points in global risk sentiment, geopolitical stability, and US Treasury yield stabilization, which will signal the eventual return of aggressive foreign institutional capital to Dalal Street.
Ultimately, while the Fed's decision to hold rates at 3.75%–4% introduces undeniable near-term turbulence, it also serves as a powerful market filter. It separates structurally resilient enterprises from over-leveraged entities, reinforcing the core investment thesis that India's long-term domestic consumption story remains fundamentally intact—provided corporations and investors maintain disciplined balance sheet management in an era of tighter global liquidity.