

Fed Breaks Pivot Pivot: Central Bank Delivers Shock Rate Hike, Directing Defiance at Washington as Inflation Roars Back
WASHINGTON — In a high-stakes pivot that instantly redraws the battle lines between monetary policy and executive power, the Federal Reserve voted to raise interest rates for the first time since 2023. The decisive move breaks a prolonged period of monetary policy stasis, directly challenging vocal pressure from Donald Trump and signaling to global markets that sticky domestic inflation has forced the central bank's hand.
The FOMC's benchmark lending rate was bumped upward by 25 basis points, catching a swath of Wall Street traders off guard who had priced in continued policy patience. The announcement immediately sent ripples through Treasury yields, equity futures, and foreign exchange markets, setting up an intense political and economic showdown.
The Inflation Trigger: Why the Fed Acted Now
For months, Federal Reserve Chair Jerome Powell and regional bank presidents have emphasized a "data-dependent" approach. However, consecutive hotter-than-expected Consumer Price Index (CPI) readings and stubborn core inflation metrics finally eroded the central bank's patience. Despite aggressive historical tightening throughout 2022 and 2023, the U.S. economy has demonstrated an unexpected resilience—spurring consumer demand that continues to fuel price pressures.
"The data has spoken, and the committee has a statutory mandate to preserve price stability," noted a senior economic strategist based in New York. "Waiting any longer risked unmooring long-term inflation expectations. The Fed had to reassert its credibility."
- First Hike Since 2023: Marks the official end of the extended rate plateau.
- Direct Political Clash: Directly counters public demands from Donald Trump for immediate rate cuts to stimulate growth.
- Market Re-pricing: Wall Street is rapidly adjusting portfolios for a "higher-for-longer" macroeconomic reality.
Political Firestorm: Defying the White House and Capitol Hill
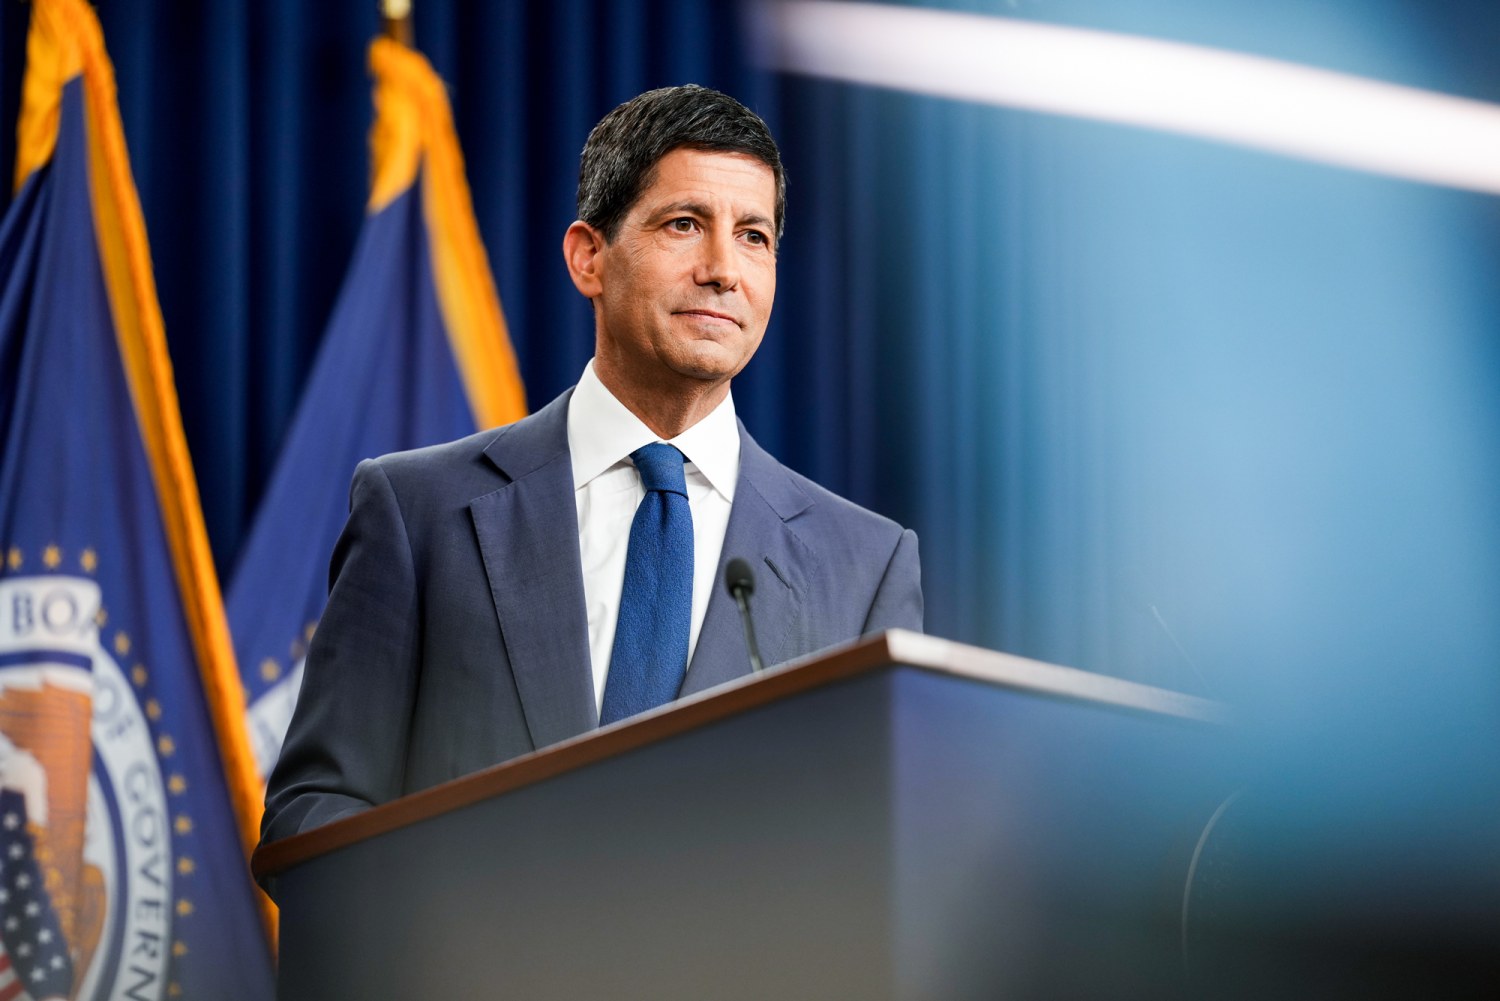
The timing and nature of the decision amplify long-standing tensions between independent monetary authorities and political leaders. Donald Trump, who has frequently criticized the Fed's leadership and advocated for aggressive monetary easing to bolster American manufacturing and real estate, is expected to launch scathing attacks on the central bank's independence.
Economists point out that raising rates during an active political cycle—and in direct contradiction to executive branch lobbying—reiterates the foundational firewall designed to protect the U.S. financial system from short-term political expediency. Yet, the friction also invites legislative scrutiny, with critics from both sides of the aisle questioning the timing and broader economic fallout of tighter credit.
Key Economic Metrics at a Glance
| Economic Indicator | Previous Status | Current Reading / Action |
|---|---|---|
| Federal Funds Rate | On hold since late 2023 | +25 bps Hike |
| Core Inflation (YoY) | Hovering above 3% target | Showing stubborn upward sticky momentum |
| Labor Market | Resilient job creation | Slight cooling, but wage growth persists |
| Market Sentiment | Optimistic for early cuts | Pivoting to risk-off positioning |
What This Means for Borrowers, Investors, and Consumers
The ripple effects of this rate hike will be felt immediately across Main Street and Wall Street alike. Consumers should prepare for higher borrowing costs across the board:
1. Credit Cards and Personal Loans
Variable-rate debt will see immediate upward adjustments. Consumers carrying revolving credit card balances will see their monthly interest charges climb, making debt consolidation a priority for household financial health.
2. Mortgages and Real Estate
While long-term mortgage rates are tied primarily to the 10-year Treasury yield rather than the direct fed funds rate, general market sentiment will likely keep borrowing costs elevated, applying further freeze conditions to the residential housing market.
3. Equities and Fixed Income
Growth stocks—particularly in tech and consumer discretionary—may face valuation compression as future cash earnings are discounted at higher rates. Conversely, short-duration fixed income assets and high-yield savings accounts continue to offer attractive, risk-free yields for conservative investors.
Looking Ahead: The Path Forward for Monetary Policy
As the dust settles on today's announcement, all eyes turn to the upcoming press conference statements and revised economic projections from Federal Reserve leadership. Will this be a singular, preemptive strike against a localized inflation flare-up, or the opening salvo of a brand-new tightening cycle? Financial markets are currently pricing in a pause at the next FOMC meeting, but traders know that data revisions can change the playbook overnight.
One thing is certain: the era of easy money is firmly in the rearview mirror, and the central bank has proven it is willing to court political controversy to achieve its 2% price stability target.
Frequently Asked Questions
Why did the Federal Reserve raise interest rates now?
The Fed acted in response to persistent, hotter-than-expected inflation data. Despite previous rate hikes, consumer demand and core price indices remained too high, forcing the central bank to tighten credit conditions to prevent long-term inflation destabilization.
How does this decision impact everyday consumers?
Consumers will experience higher borrowing costs across variable-rate products, including credit cards, home equity lines of credit (HELOCs), and personal loans. However, savers benefit from higher yields on cash equivalents like high-yield savings accounts and certificates of deposit (CDs).



