The Great Locked-Out Generation: Why Record Numbers of First-Time Buyers Are Sidestepping Mortgages and Paying All-Cash
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
A confluence of structural interest rate regimes, intergenerational wealth transfer, and compressed market liquidity is rewriting the playbook for entering the property ladder—leaving debt-reliant buyers stranded.
Executive Takeaways
- The Paradox of Scarcity: Overall first-time homebuyer market share sits near historic lows, yet the proportion of those who manage to close entirely with cash has hit an all-time record high.
- The Bank of Mom, Dad, and Equities: The phenomenon is largely driven by structured capital allocation from familial wealth transfers, liquidity events in public/private markets, and high-net-worth migration.
- Financing Friction: Persistently elevated borrowing costs and rigid underwriting standards have created an insurmountable risk-mitigation barrier for traditional mortgage applicants.
- Market Bifurcation: This trend exacerbates systemic asset inequality, divorcing residential real estate valuation multiples from broader wage growth and labor market dynamics.
The Anatomy of an Unprecedented Real Estate Divergence
For decades, the standard initiation rite into the middle class followed a predictable trajectory: secure an entry-level professional position, accumulate a modest savings buffer for a 10% to 20% down payment, secure a 30-year fixed-rate mortgage from a commercial lender, and close on a suburban or urban starter home. Today, that conventional capital allocation blueprint has broken down. Macroeconomic tightening cycles, sticky inflation prints, and structural housing inventory bottlenecks have fundamentally altered market liquidity.
Yet, beneath the headline data of plunging affordability indices and stagnant first-time buyer transaction volumes lies a startling counter-trend captured by recent Google Trends and real-time wire analysis: while first-time buyers remain remarkably scarce overall, a record-shattering share of those who do successfully cross the finish line are paying entirely in cash.
This structural shift is not merely an anomaly of luxury real estate; it is permeating entry-level and mid-tier housing stock. To understand this phenomenon, financial analysts must look beyond standard housing starts and examine the complex interplay of intergenerational wealth transfers, corporate balance sheet engineering, and the steep opportunity costs imposed by current monetary policy.
Catalytic Events: Interest Rate Regimes and the Cost of Capital

The roots of this cash-buyer surge trace back to the aggressive monetary tightening cycle initiated by central banks to combat post-pandemic inflation. As benchmark interest rates climbed from historic lows to restrictive plateaus, mortgage rates followed suit, pricing millions of prospective wage-earning buyers out of debt-market qualification.
Underwriting standards across tier-one banking institutions have tightened significantly. Risk mitigation departments now demand pristine credit metrics, lower debt-to-income (DTI) ratios, and exhaustive documentation of income stability. For a young professional relying purely on W-2 salary growth, qualifying for a median-priced home at current borrowing costs requires an income multiple that outpaces standard career progression.
Simultaneously, institutional investors and high-net-worth individuals who accumulated liquid capital during previous equity bull runs and technology liquidity events found themselves sitting on substantial cash reserves. With fixed-income yields stabilizing, deploying capital directly into residential real estate as an all-cash play eliminated financing contingency risks, allowing buyers to bypass bidding wars and secure properties outright.
| Metric / Indicator | Historical Average (Pre-2022) | Current Market Reality | Systemic Impact |
|---|---|---|---|
| First-Time Buyer Market Share | 38% – 40% of total transactions | Sub-28% (Historic Lows) | Compressed upward mobility |
| All-Cash Share (First-Timers) | Single-digit percentages | Record Highs (Double-digits) | Bypasses mortgage liquidity channels |
| Average Effective Mortgage Rate | 3.0% – 4.5% | 6.5% – 7.5% range | Severe borrowing disincentive |
| Primary Capital Source | W-2 Savings & Fannie/Freddie Loans | Family Trusts & Equity Liquidation | Amplifies generational wealth divide |
The Rise of Intergenerational Capital Allocation
How are young buyers securing hundreds of thousands of dollars in liquid cash without traditional debt instruments? Investigative tracking of real estate settlements points directly to structured familial assistance—often colloquially referred to as the "Bank of Mom and Dad," though increasingly institutionalized through formal family trusts, estate planning, and early inheritance distributions.
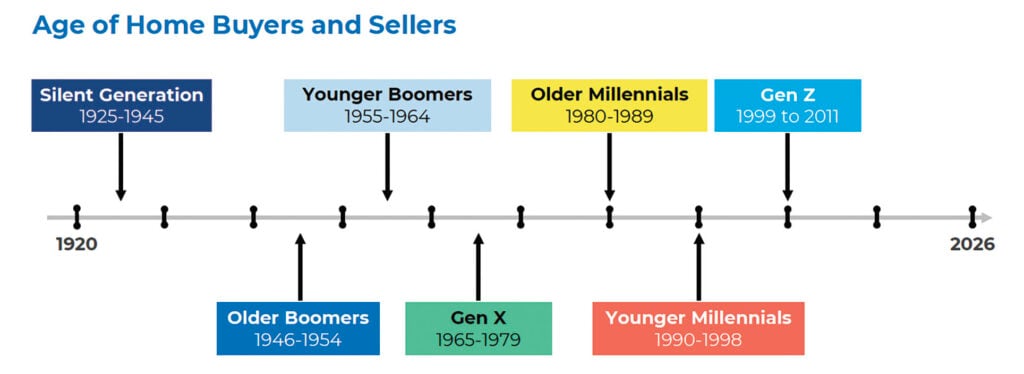
As the Baby Boomer generation sits on trillions of dollars in accumulated housing equity and appreciating financial portfolios, wealth advisors are increasingly recommending lifetime gifting strategies. Rather than waiting for probate, affluent families are executing capital allocation strategies that transfer cash or liquidate non-primary assets to purchase homes for their children outright. This shields the younger generation from debilitating monthly debt service obligations in a high-interest-rate environment.
Furthermore, technology sector grants, early-stage startup liquidity events, and cryptocurrency realizations have minted a cohort of younger cash buyers who can bypass commercial lenders entirely. For these buyers, enterprise ROI on real estate is viewed through the lens of capital preservation and inflation hedging rather than leveraged yield generation.
Industry & Market Implications: Who Wins, Who Loses
The bifurcation of the housing market into cash-heavy buyers and debt-locked aspirants carries profound implications across the financial ecosystem:
- Commercial Banks and Mortgage Lenders: Traditional retail lenders face margin compression. With origination volumes constrained by high rates and cash buyers bypassing mortgage products entirely, financial institutions are forced to pivot toward fee-based wealth management and commercial real estate refinancing to protect profitability.
- Real Estate Brokerages and PropTech: Agencies specializing in smooth, fast, all-cash transactions are capturing disproportionate market share. Conversely, traditional agents managing chains of contingent, mortgage-dependent buyers face extended days-on-market metrics and frequent deal fall-throughs.
- The Broader Labor Force and Social Mobility: The inability of standard wage earners to enter the housing market threatens geographic labor mobility. When workers cannot purchase homes near high-productivity employment centers, regional economic dynamism slows, widening the wealth gap between asset-inheriting households and labor-reliant households.
Frequently Asked Questions (People Also Ask)
Why are first-time homebuyers paying all-cash despite high interest rates?
High interest rates make mortgage financing prohibitively expensive, pricing out debt-dependent buyers. Those who do buy are predominantly drawing on accumulated family wealth, early inheritances, or private equity liquidity to pay cash, completely bypassing the high-rate mortgage market.
Does an all-cash purchase grant an advantage in competitive bidding?
Significantly. Sellers favor all-cash offers because they eliminate financing contingencies, appraisal gap risks, and the lengthy mortgage underwriting timeline—frequently allowing transactions to close in days rather than weeks.
Are institutional investors driving this all-cash trend among first-time buyers?
While institutional single-family rental (SFR) funds remain active in specific Sunbelt markets, the record share of cash-paying first-time individual buyers is primarily driven by high-net-worth households and intergenerational wealth transfers rather than corporate landlords.
What are the long-term economic consequences of a cash-dominated starter home market?
It cements a two-tiered real estate landscape where property ownership increasingly depends on familial wealth rather than individual earnings, potentially stalling upward socioeconomic mobility and altering long-term demographic formation rates.
Future Outlook: What Comes Next and Key Milestones to Watch
As central banks navigate macroeconomic volatility and weigh potential monetary policy adjustments, market participants must monitor several critical leading indicators. If benchmark interest rates undergo a sustained downward revision, mortgage rates could normalize, drawing debt-reliant first-time buyers back into the competitive pool and moderating the statistical dominance of all-cash transactions.
However, if borrowing costs remain elevated throughout the medium term, the reliance on intergenerational capital allocation will solidify from a cyclical reaction into a permanent structural feature of modern real estate economics. Industry regulators, urban planners, and financial institutions will need to innovate new capital structures—such as shared-equity mortgages and fractional ownership models—to restore market liquidity and preserve the viability of the traditional property ladder for the next generation of workers.