Executive Takeaways
- State-Driven Scale: Groundbreaking research published by the Information Technology and Innovation Foundation (ITIF) on July 29, 2024, challenges the narrative of pure market-driven Chinese tech disruption, highlighting massive direct and indirect state interventions.
- Monopolistic Supply Chains: Chinese enterprises now control nearly two-thirds of global EV production and maintain an absolute chokehold on critical raw material refining, including lithium, cobalt, and graphite.
- Valuation & Capital Allocation Realities: Western automotive incumbents face punishing valuation multiples and compressed enterprise ROI as they attempt to match Beijing’s rapid infrastructure scalability and manufacturing velocity.
- Strategic Risk Mitigation: Global trade regulators are accelerating tariff mechanisms and compliance mandates to protect domestic manufacturing bases from structural overcapacity exported out of East Asia.
LONDON, WASHINGTON, & BEIJING — For the past decade, boardrooms across Detroit, Wolfsburg, and Tokyo have grappled with an uncomfortable reality: the center of gravity for the global automotive industry has decisively shifted eastward. When the Information Technology and Innovation Foundation (ITIF) released its landmark briefing on July 29, 2024, scrutinizing the true mechanics of China’s ascendance in electric vehicles (EVs) and advanced battery architectures, it shattered long-held assumptions. The prevailing Western narrative had often framed China’s success as a triumph of agile consumer electronics thinking applied to mobility. The ITIF data, however, paints a far more complex picture—one defined by multi-decade state-directed capital allocation, strategic supply chain vertical integration, and an unrivaled velocity of engineering iteration.
As global markets navigate tightening monetary policies, shifting regulatory compliance frameworks, and volatile energy commodity prices, understanding the precise architecture of China's EV dominance is no longer an academic exercise. It is a vital imperative for corporate risk mitigation, sovereign capital planning, and long-term enterprise valuation.
The Anatomy of Industrial Dominance: Beyond Low-Cost Labor
To evaluate the true level of innovation within China’s EV and battery ecosystem, financial analysts and sector strategists must first discard outdated tropes concerning low-cost labor and intellectual property replication. While cost arbitrage played a foundational role during the nascent stages of Beijing’s "New Energy Vehicle" (NEV) push in the early 2010s, contemporary Chinese leadership in mobility is anchored in advanced process engineering, chemical formulation breakthroughs, and massive economies of scale.
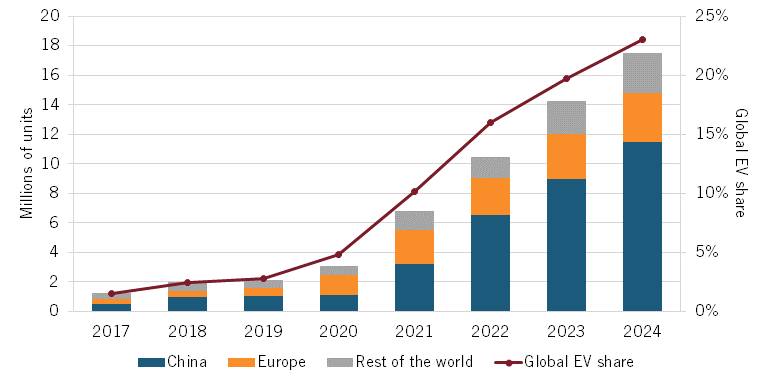
According to the July 2024 ITIF briefing, Chinese firms currently command nearly two-thirds of global electric vehicle manufacturing output. More critically, their dominance extends deep into the upstream electrochemical supply chain. Companies like Contemporary Amperex Technology Co. Limited (CATL) and BYD do not merely assemble battery packs; they control the intricate, capital-intensive pathways of precursor refining, cathode and anode production, separator manufacturing, and electrolyte synthesis. This degree of vertical integration shields domestic original equipment manufacturers (OEMs) from external supply shocks, insulating profit margins even as global lithium carbonate prices experience wild cyclical swings.
Furthermore, the velocity of R&D-to-market execution in China far outpaces legacy Western automotive paradigms. While a traditional European or American OEM often requires five to seven years from clean-sheet vehicle architecture to commercial showroom floor, leading Chinese NEV makers have compressed this cycle to under thirty-six months. This hyper-accelerated product lifecycle is powered by aggressive software-defined vehicle (SDV) integration, centralized cloud compute architecture, and deep linkages with domestic consumer electronics giants.
Deciphering the Catalyst: The State-Capital Nexus
A central thesis of the ITIF report centers on the unique nature of China’s "innovation mercantilism." Unlike market-driven economies where venture capital and private equity dictate resource allocation based on short-term enterprise ROI, China’s industrial policy operates on a multi-decade horizon backed by the full faith and credit of the state.
Beginning with targeted subsidies enacted under the 863 Program and turbocharged by municipal government equity injections—often referred to as the "Hefei Model"—local governments routinely act as venture capitalists. When NIO faced severe liquidity crunches in 2020, the municipal government of Hefei injected billions of yuan in exchange for equity and a manufacturing footprint. This symbiotic relationship between municipal balance sheets, state-owned banks, and private technological entrepreneurship creates an environment of virtually limitless liquidity for favored sectors.
This capital abundance allows Chinese battery cell and vehicle manufacturers to absorb years of operating losses while aggressively capturing market share globally. Western competitors, beholden to public shareholders demanding immediate free cash flow generation and rationalized capital expenditure, find it mathematically challenging to compete against state-underwritten industrial scaling.
Comparative Metrics: China vs. G7 EV & Battery Ecosystems
The following empirical breakdown highlights the structural divergence between Chinese industrial capacities and those of Western economies, synthesizing data from the July 2024 ITIF policy briefing and allied market intelligence sources:
| Metric / Indicator | China Ecosystem | United States & G7 Allies | Strategic Implication |
|---|---|---|---|
| Global EV Production Share | ~60% to 65% | ~20% to 25% | Massive manufacturing overcapacity exported globally. |
| Battery Cell Refining & Processing | 75% - 85% of global market | Sub-15% cumulative share | Extreme upstream dependency risk for Western automakers. |
| Average Product Development Cycle | 24 to 36 months | 60 to 84 months | Unmatched agility in responding to consumer tech trends. |
| Primary Capital Source | State-directed equity, policy banks | Private capital, public markets, debt | Insulation from short-term market downturns in China. |
Market Implications: Winners, Losers, and the Geopolitical Fracture
The implications of China’s state-channeled industrial innovation are rippling across global financial markets, forcing institutional investors to re-evaluate valuation multiples for legacy automotive assets. Traditional automakers accustomed to decades of oligopolistic pricing power are experiencing severe margin compression. As Chinese brands launch highly sophisticated, software-rich EVs priced below $15,000 domestically and push aggressive export campaigns into Europe, Latin America, and Southeast Asia, European and American incumbents are forced into difficult defensive postures.
Who Wins: Upstream chemical processors, maritime logistics providers equipped for hazardous battery transport, and Chinese Tier-1 suppliers who have successfully navigated global compliance hurdles are reaping extraordinary rewards. Furthermore, global consumers in developing markets benefit immediately from accelerated access to affordable, technologically advanced mobility options.
Who Loses: Legacy European and American original equipment manufacturers that delayed their platform transitions face existential threats. Additionally, domestic component suppliers in Germany and the U.S. Midwest—historically reliant on internal combustion engine (ICE) powertrain complexity—face rapid obsolescence as EV architectures require significantly fewer mechanical parts.
In response, Western policymakers are deploying aggressive defensive trade instruments. The European Union’s anti-subsidy investigations and provisional countervailing duties, alongside the United States' stringent Foreign Entity of Concern (FEOC) rules under the Inflation Reduction Act (IRA), represent an escalating regulatory barrier designed to protect domestic industrial bases from structural displacement.
Frequently Asked Questions (People Also Ask)
Q: What were the primary findings of the July 29, 2024 ITIF report regarding Chinese EV innovation?
A: The ITIF briefing concluded that China’s commanding position in the global electric vehicle and battery sectors is not merely the result of standard commercial competition. Instead, it is heavily underwritten by extensive, multi-decade state-directed industrial policies, massive financial subsidies, and systemic state support that distort global market pricing and create insurmountable barriers for unassisted foreign competitors.
Q: How do Chinese battery manufacturers maintain such a decisive cost advantage over Western rivals?
A: Chinese battery giants benefit from absolute vertical integration across the entire electrochemical supply chain—from raw mineral extraction and refining (lithium, cobalt, graphite) to cathode, anode, and cell manufacturing. Combined with lower domestic energy costs, massive gigafactory scale, and state-backed capital expenditure, these factors allow them to produce cells at significantly lower cost per kilowatt-hour (kWh).
Q: What regulatory mechanisms are Western governments using to counter Chinese EV market penetration?
A: Western nations are deploying a combination of tariff barriers and stringent sourcing compliance. The European Union has implemented countervailing duties following anti-subsidy probes, while the United States utilizes the Inflation Reduction Act (IRA), which disqualifies vehicles containing critical minerals or battery components sourced from "Foreign Entities of Concern" (FEOC) from receiving consumer tax credits.
Q: Are Chinese automakers genuinely innovative in software and vehicle architecture, or just manufacturing at scale?
A: Both. While manufacturing scale is foundational, Chinese NEV makers lead the world in rapid product iteration, advanced ADAS (Advanced Driver Assistance Systems) deployment, smart cockpit integration, and electrical/electronic (E/E) architecture centralization. Their ability to release new software-defined vehicle models in under 36 months far outpaces legacy Western development timelines.
Future Outlook: Strategic Milestones to Watch
As the global automotive landscape approaches the close of the decade, several critical inflection points will determine whether Western industrial policy can successfully re-shore EV supply chains or if Chinese dominance becomes permanent:
- Solid-State Battery Commercialization: Watch for industrial-scale deployment of semi-solid and solid-state batteries. Chinese firms, backed by government consortia, are aggressively racing to achieve mass production by 2027–2028, which could widen the energy-density gap further.
- Geopolitical Tariff Escalation: Monitor upcoming trade rulings in North America and the EU. Should broad secondary sanctions or absolute import bans materialize, Chinese manufacturers are expected to accelerate greenfield manufacturing investments within Mexico, Eastern Europe, and Southeast Asia to bypass trade barriers.
- Capital Market Re-ratings: Institutional investors must monitor the debt-to-equity health of secondary Chinese EV startups. While tier-one giants like BYD and CATL enjoy fortress balance sheets, smaller players reliant on municipal bailouts remain vulnerable to domestic price wars.
Ultimately, the ITIF disclosures of July 2024 serve as a definitive wake-up call. The transformation of the global automotive sector is no longer merely a technological transition toward decarbonization; it is a high-stakes geopolitical contest where industrial policy, capital allocation strategy, and supply chain sovereignty will dictate the hierarchy of global economic power for the next fifty years.