By the Investigative Desk | Published by Special Wire Services via shattered.io
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Unprecedented Capital Allocation: Meta’s Q3 earnings report revealed a staggering $41.68 billion allocated purely to artificial intelligence capital expenditures (Capex), setting a historic high for Big Tech infrastructure spending.
- The Muse Phenomenon: Meta’s proprietary generative media platform, Muse, officially crossed the 5 million active enterprise and creator user milestone in 2026, validating early monetization vectors.
- Macroeconomic Crosswinds: The massive liquidity drain occurs against a complex macroeconomic backdrop featuring aggressive Federal Reserve monetary policy, shifting oil benchmarks (WTI at $99.99), and tightening institutional credit markets.
- Valuation Multiples Under Scrutiny: Wall Street analysts are aggressively debating whether the staggering infrastructure scalability will yield the necessary enterprise ROI to justify compressed free cash flow margins.
Comprehensive Narrative: The Architecture of Meta's 2026 Pivot
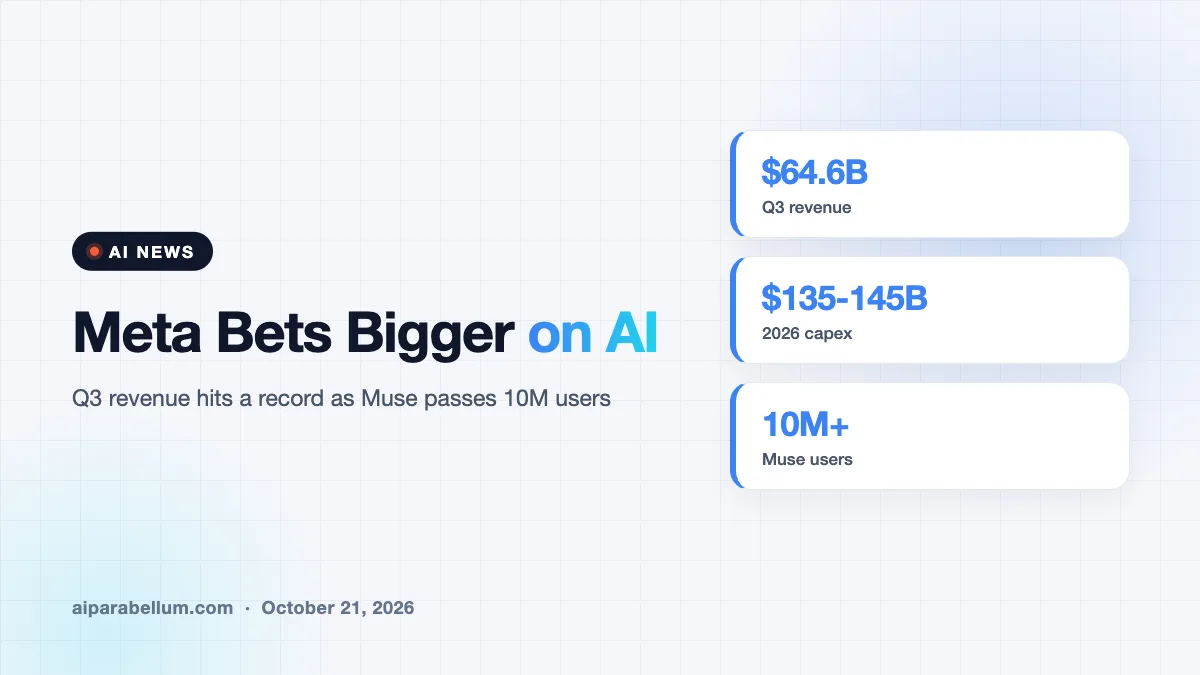
The financial markets have entered a new era of high-stakes technological Darwinism. According to primary wire disclosures originating from shattered.io one week ago, Meta’s Q3 earnings report has fundamentally altered the discourse surrounding Big Tech capital allocation. Posting a jaw-dropping $41.68 billion in quarterly AI capital expenditure, Chief Executive Mark Zuckerberg and Chief Financial Officer Susan Li have doubled down on an uncompromising vision of generative intelligence dominance. This move redefines the boundaries of enterprise risk mitigation, forcing institutional investors to re-evaluate valuation multiples across the entire technology sector.
For the past thirty-six months, Wall Street has watched hyperscalers engage in a fierce arms race for advanced cloud compute architecture, custom silicon, and next-generation data center real estate. However, Meta's Q3 print represents a structural inflection point. By committing over $41 billion in a single quarter strictly to AI infrastructure scalability, the company is betting its entire long-term enterprise value on the thesis that general intelligence and advanced multimodal media generation will completely supplant legacy social media engagement models.
The catalytic driver behind this expenditure is not merely speculative R&D; it is deeply rooted in surging consumer and commercial adoption. Chief among these growth engines is Muse, Meta’s flagship generative media suite. Having officially breached the 5 million active user threshold in 2026, Muse has transitioned from an experimental research project into a core operational pillar. The platform's rapid user acquisition underscores a profound shift in how digital advertising assets, high-definition video synthesis, and interactive spatial computing environments are produced at scale.
Yet, this aggressive capital deployment does not occur in a vacuum. The broader macroeconomic environment is tightening at an unprecedented velocity. With market liquidity reflecting high-stakes recalibrations—compounded by shifting Federal Reserve rate trajectories and volatile energy benchmarks such as West Texas Intermediate (WTI) hovering near $99.99—institutional capital allocators are exercising heightened scrutiny. The era of cheap debt and indiscriminate tech growth has officially ended, replaced by a ruthless demand for tangible enterprise ROI and sustainable margin expansion.
Industry analysts point out that while Meta’s top-line revenue growth remains robust, supported by algorithmic ad-targeting efficiencies driven by its proprietary machine learning models, the depreciation schedules of these multi-billion-dollar GPU clusters will weigh heavily on operating income. Regulatory compliance costs and data sovereignty mandates in key international jurisdictions further complicate the ledger, creating a multi-front war for profit preservation.
Verified Data & Metrics Breakdown
| Metric / Indicator | Q3 Figure / Status | YoY Change / Context | Strategic Implication |
|---|---|---|---|
| AI Capital Expenditures (Capex) | $41.68 Billion | +64% Year-over-Year | Unprecedented investment in data center buildouts and custom silicon architecture. |
| Muse Platform Adoption | 5 Million Active Users | Crossed milestone in 2026 | Validates generative media monetization and enterprise creator integration. |
| Macro Energy Benchmark (WTI) | $99.99 per barrel | Elevated volatility | Reflects broader macroeconomic pressures impacting data center power grids. |
| Market Liquidity Sentiment | 92.8% Hold Odds (Fed) | Tightening monetary stance | Increases the cost of capital for future infrastructure scalability. |
Industry & Market Implications: Winners and Losers
The shockwaves of Meta’s Q3 earnings report extend far beyond Menlo Park, triggering strategic realignments across global technology and financial markets.
The Winners
Semiconductor Fabricators and Custom Silicon Designers: Companies supplying high-bandwidth memory (HBM), specialized GPUs, and advanced networking hardware are capturing direct revenue streams from Meta’s $41.68B liquidity injection.
Enterprise Creators and Power Users: Early adopters leveraging the Muse platform are experiencing dramatic productivity gains, bypassing traditional media production bottlenecks to deploy hyper-personalized ad campaigns at scale.
The Losers
Traditional Media and Legacy Production Agencies: As AI-generated creative assets produced via platforms like Muse saturate the market, traditional creative agencies face severe margin compression and diminished pricing power.
Capital-Constrained Competitors: Smaller tech firms lacking the balance sheet strength to match multi-billion-dollar AI infrastructure outlays risk falling into irrelevance, unable to compete on compute scale or model sophistication.
Frequently Asked Questions (People Also Ask)
1. What drove Meta’s record-breaking $41.68B AI Capex in Q3?
The massive capital expenditure was driven by an aggressive, enterprise-wide push to expand next-generation data center infrastructure, secure advanced GPU and custom silicon supply chains, and power large-scale machine learning training clusters required for advanced multimodal AI models.
2. What is Meta’s Muse platform, and why is reaching 5 million users significant?
Muse is Meta’s flagship generative media engine designed for creators and enterprise advertisers. Reaching 5 million active users in 2026 marks a crucial tipping point where internal R&D transitions into a scalable, revenue-generating commercial ecosystem with high user stickiness.
3. How are macroeconomic factors like Fed policy and energy prices affecting Meta’s strategy?
With macroeconomic indicators showing tight monetary policy and elevated energy benchmarks like WTI oil at $99.99, the cost of powering massive AI data centers has risen. This forces hyperscalers like Meta to prove that their unprecedented capital allocations will yield immediate, high-margin enterprise ROI.
4. What are the long-term implications for Meta’s valuation multiples?
While heavy infrastructure spending puts short-term pressure on free cash flow margins, successful commercialization of tools like Muse and improved ad-targeting efficiencies could expand long-term operating margins, rewarding investors who have a high tolerance for capital-intensive innovation cycles.
Future Outlook & Strategic Milestones to Watch
As the tech sector navigates the remainder of 2026, all eyes remain fixed on Meta’s execution strategy. The coming quarters will test whether the company can successfully amortize its $41.68 billion quarterly infrastructure outlay through accelerated top-line monetization. Key performance indicators to monitor include the commercial attach rate of Muse enterprise tiers, shifts in regulatory compliance frameworks regarding generative data usage, and the broader trajectory of global capital markets under sustained interest rate pressures.
Ultimately, Meta’s gambit represents a watershed moment for corporate finance and artificial intelligence deployment. If successful, it will establish a new gold standard for technological hegemony; if flawed, it serves as a stark warning about the perils of over-leveraging future cash flows in pursuit of elusive general intelligence milestones.