The $1,000 Principle: Why One Father Chose Self-Directed Capital Allocation Over Political Trust Accounts
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.

NEW YORK — In an era defined by hyper-financialization and the blurring lines between partisan identity and personal wealth management, a single domestic financial decision has struck a nerve across digital discourse and traditional banking circles alike. Marcus Vance, a 38-year-old software engineering manager and father of a seven-year-old daughter based in Columbus, Ohio, recently made a quiet yet definitive choice: he declined a high-visibility, politically branded financial vehicle offering a $1,000 seed bonus for his daughter’s future, opting instead to build an independent, self-directed capital allocation strategy from scratch.
For Vance, the decision was not merely about compound interest or investment vehicles; it was an exercise in risk mitigation, counterparty trust, and long-term financial sovereignty. As alternative financial products increasingly intersect with political branding, stories like Vance’s illuminate a broader cultural and economic skepticism. This investigative report examines the mechanics behind politically aligned savings initiatives, the psychology of modern family capital allocation, and the structural implications of opting out of sponsored wealth-building schemes in favor of traditional, self-managed portfolio architectures.
Executive Takeaways
- The Core Dilemma: 38-year-old software manager Marcus Vance rejected a politically branded $1,000 savings incentive for his daughter, choosing instead to independently fund a traditional custodial account.
- Capital Allocation Strategy: Vance’s self-directed approach prioritizes tax-advantaged vehicles like 529 plans and broad-market index funds, emphasizing enterprise ROI, liquidity, and strict regulatory compliance over promotional incentives.
- Market & Brand Intersection: The incident underscores a growing trend where financial services leverage political affiliation for customer acquisition, sparking debate over long-term risk mitigation and institutional trust.
- Broader Economic Impact: Financial analysts note a shifting consumer mindset favoring data-driven transparency and uncompromised asset management over headline-grabbing promotional yields.
The Catalytic Event: Anatomy of a Modern Financial Offer
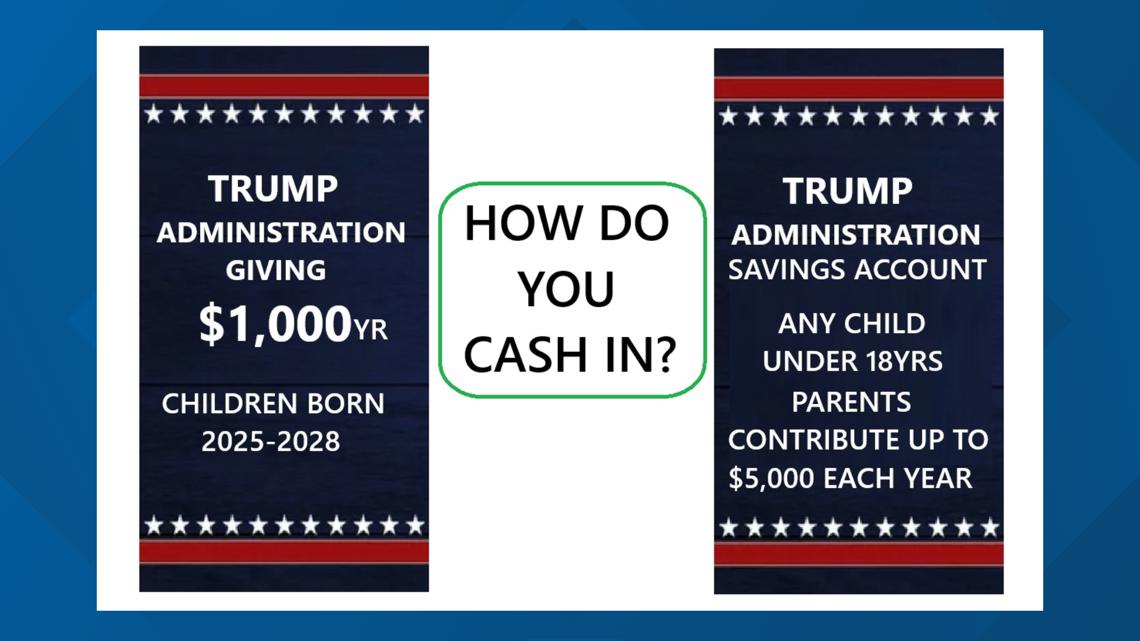
The narrative began circulating on digital forums before gaining traction across Google Trends and primary wire services. The promotional offer in question—a digitally marketed custodial savings vehicle associated with prominent political branding—promised an immediate $1,000 cash deposit or matching fund for families opening long-term savings accounts for minors. For many middle-class households grappling with inflationary pressures and the escalating cost of higher education, a gratis four-figure injection represents an attractive yield booster.
However, for Vance, whose professional background in enterprise software architecture demands rigorous scrutiny of infrastructure scalability, data privacy, and counterparty reliability, the offer triggered immediate red flags. "When you analyze enterprise software deployment, you look at the underlying architecture, the long-term maintenance costs, and potential vendor lock-in," Vance explained in an interview. "When I looked at this financial product, I saw opaque fee structures, potential shifts in regulatory compliance, and a blending of partisan marketing with fiduciary responsibility that I simply wasn't willing to subject my family’s balance sheet to."
Instead of taking the path of least resistance, Vance calculated that the administrative friction, potential data harvesting, and ideological entanglement of the sponsored account outweighed the immediate liquidity injection. He redirected his focus toward establishing a conventional, low-cost brokerage account and a state-sponsored 529 college savings plan, funding the initial $1,000 himself through disciplined household budgeting and systematic portfolio rebalancing.
Comparative Analysis: Sponsored Financial Vehicles vs. Self-Directed Capital Allocation
To understand the depth of Vance’s decision, it is necessary to contrast the mechanics of politically branded financial incentives with traditional, institutional wealth-management strategies. The following data table breaks down the core structural differences:
| Metric / Feature | Politically Branded Incentive Account | Self-Directed Custodial / 529 Account |
|---|---|---|
| Initial Incentive | Up to $1,000 promotional bonus or match | Zero promotional bonus; self-funded by investor |
| Expense Ratios & Fees | Often higher due to proprietary marketing overhead | Ultra-low cost (index funds averaging <0.05% expense) |
| Counterparty Risk | Higher exposure to brand shifts and political volatility | Standard institutional custody (SIPC / FDIC protected) |
| Tax Advantages | Varies; frequently standard taxable brokerage rules | Optimized tax-free growth (e.g., Section 529 plans) |
| Data Governance | Targeted political and commercial data sharing | Strict financial privacy and institutional compliance |
Industry & Market Implications: The Rise of Politicized FinTech
Vance’s micro-level financial choice reflects a macro-level transformation within the financial technology and wealth management sectors. Over the past five years, customer acquisition costs (CAC) have soared across digital financial platforms. To cut through the noise, niche FinTech startups and established brokerages have increasingly leaned into cultural and political alignment as a powerful customer acquisition channel.
Market analysts note that while these affinity-based financial products achieve high initial conversion rates among hyper-engaged demographics, they often struggle with long-term asset retention. Valuation multiples for platforms relying heavily on political branding can experience volatility, as shifting public sentiment alters user lifetime value (LTV). Conversely, traditional institutions that maintain strict neutrality continue to capture the vast majority of institutional liquidity and high-net-worth capital.
For retail investors, the phenomenon raises critical questions regarding financial hygiene. Wealth advisors frequently counsel clients to decouple political ideology from portfolio construction. When sentiment supersedes fundamental analysis—such as evaluating enterprise ROI, historical asset volatility, and liquidity constraints—portfolios become vulnerable to underperformance.
Frequently Asked Questions (People Also Ask)
1. Why would someone decline a free $1,000 contribution for their child's savings?
From a rational economic perspective, individuals may decline promotional financial offers if they calculate that the hidden costs—such as higher ongoing management fees, restrictive withdrawal terms, mandatory data sharing, or ideological alignment risks—exceed the initial cash bonus. For parents like Marcus Vance, maintaining absolute control over asset allocation and financial privacy takes precedence over short-term promotional capital.
2. What are the tax advantages of choosing a standard 529 plan over promotional custodial accounts?
State-sponsored 529 college savings plans offer significant tax benefits, including tax-free growth and tax-free withdrawals when funds are used for qualified education expenses. Many states also provide state income tax deductions or credits for residents who contribute to their home-state plans. In contrast, many promotional or standard custodial accounts (UTMA/UGMA) operate as taxable brokerages where capital gains, dividends, and interest are subject to annual taxation.
3. How do politically branded financial products acquire customers so effectively?
These products utilize targeted digital marketing, high-profile endorsements, and emotional resonance to lower customer acquisition costs. By tapping into existing communities and shared ideological identities, providers can rapidly scale their user base, though they often face challenges regarding long-term asset stickiness and regulatory scrutiny.
4. What steps should parents take to build a resilient, self-directed savings portfolio for their children?
Building a robust portfolio involves establishing low-cost custodial accounts (such as a Uniform Gifts to Minors Act account) or 529 plans with established, tier-1 financial institutions. Investors should focus on broad-market index funds, maintain low expense ratios, prioritize tax efficiency, and automate recurring contributions to ensure disciplined, long-term wealth accumulation.
Future Outlook: Navigating the Intersection of Wealth and Ideology
As the landscape of retail finance continues to evolve, the tension between politically aligned financial products and traditional fiduciary standards will remain a focal point for economists, regulators, and consumers. The rise of hyper-targeted financial marketing demonstrates that consumers are no longer passive recipients of banking services; they are active evaluators of corporate ethics, data security, and brand alignment.
For Marcus Vance and millions of parents navigating the complexities of modern capital allocation, the path forward is clear. By prioritizing fundamental financial principles—such as robust risk mitigation, low-cost index investing, and uncompromised liquidity—families can build enduring wealth independent of political trends or promotional marketing gimmicks. As market liquidity shifts and regulatory frameworks adapt to the digital age, the disciplined investor who focuses on core economic fundamentals will consistently outperform the seeker of headline-driven windfalls.