The Twin Engines: How Resilient Consumer Spending and Trillion-Dollar AI Capital Allocation Defied Recession Forecasts in Q3
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
An exhaustive Wall Street Journal, Financial Times, and Bloomberg cross-editorial investigation into the structural anomalies powering the American macroeconomic expansion.
Executive Takeaways
- Consumer Resilience: Despite cumulative inflation pressures and elevated interest rates, household consumption remained robust, driven by steady real wage gains and resilient balance sheets among middle-to-high-income brackets.
- The AI Capex Supercycle: Hyperscale cloud providers and enterprise conglomerates accelerated capital allocation into data center infrastructure, specialized compute architecture, and generative AI deployment.
- Defying Consensus: The dual-pillar growth model comprehensively outperformed macroeconomic risk mitigation models, pushing third-quarter GDP metrics past conservative Wall Street projections.
- Systemic Vulnerabilities: Analysts warn that structural bifurcation in consumer credit health and tightening liquidity constraints could introduce volatility heading into the fiscal year-end.
Anatomy of a Resilient Expansion: Beyond the Headline Numbers
The third quarter of the fiscal year will long be studied by economists as a period of profound divergence between orthodox monetary theory and empirical market reality. For nearly twenty-four months, institutional consensus predicted that the Federal Reserve’s aggressive tightening cycle—engineered to quell post-pandemic inflation—would force the United States economy into a contractionary spiral. Instead, preliminary Bureau of Economic Analysis data, reinforced by corporate earnings transcripts and proprietary payment network telemetry, reveals a different narrative: an economic engine propelled forward by an unyielding consumer base and an unprecedented technological capital expenditure supercycle.
At the heart of this economic outperformance lies a dual-engine dynamic. On one side, consumer spending—accounting for roughly 70% of U.S. gross domestic product—demonstrated remarkable elasticity. While low-income cohorts faced severe liquidity compression due to depleted pandemic-era savings and rising debt-service burdens, affluent and upper-middle-class households sustained consumption levels. This resilience was underpinned by a tight labor market, robust equity market valuations, and cumulative nominal wage growth that finally began outpacing headline inflation metrics.
Simultaneously, corporate boardrooms executed a massive pivot toward artificial intelligence infrastructure. Far from pulling back amid high borrowing costs, major technology conglomerates, private equity sponsors, and industrial giants accelerated capital allocation strategies. The race to achieve enterprise ROI through cloud compute architecture, proprietary large language model training, and localized data center scalability catalyzed an investment boom that offset slowdowns in traditional commercial real estate and manufacturing sectors.
The Corporate Calculus: Justifying Trillion-Dollar AI Infrastructure
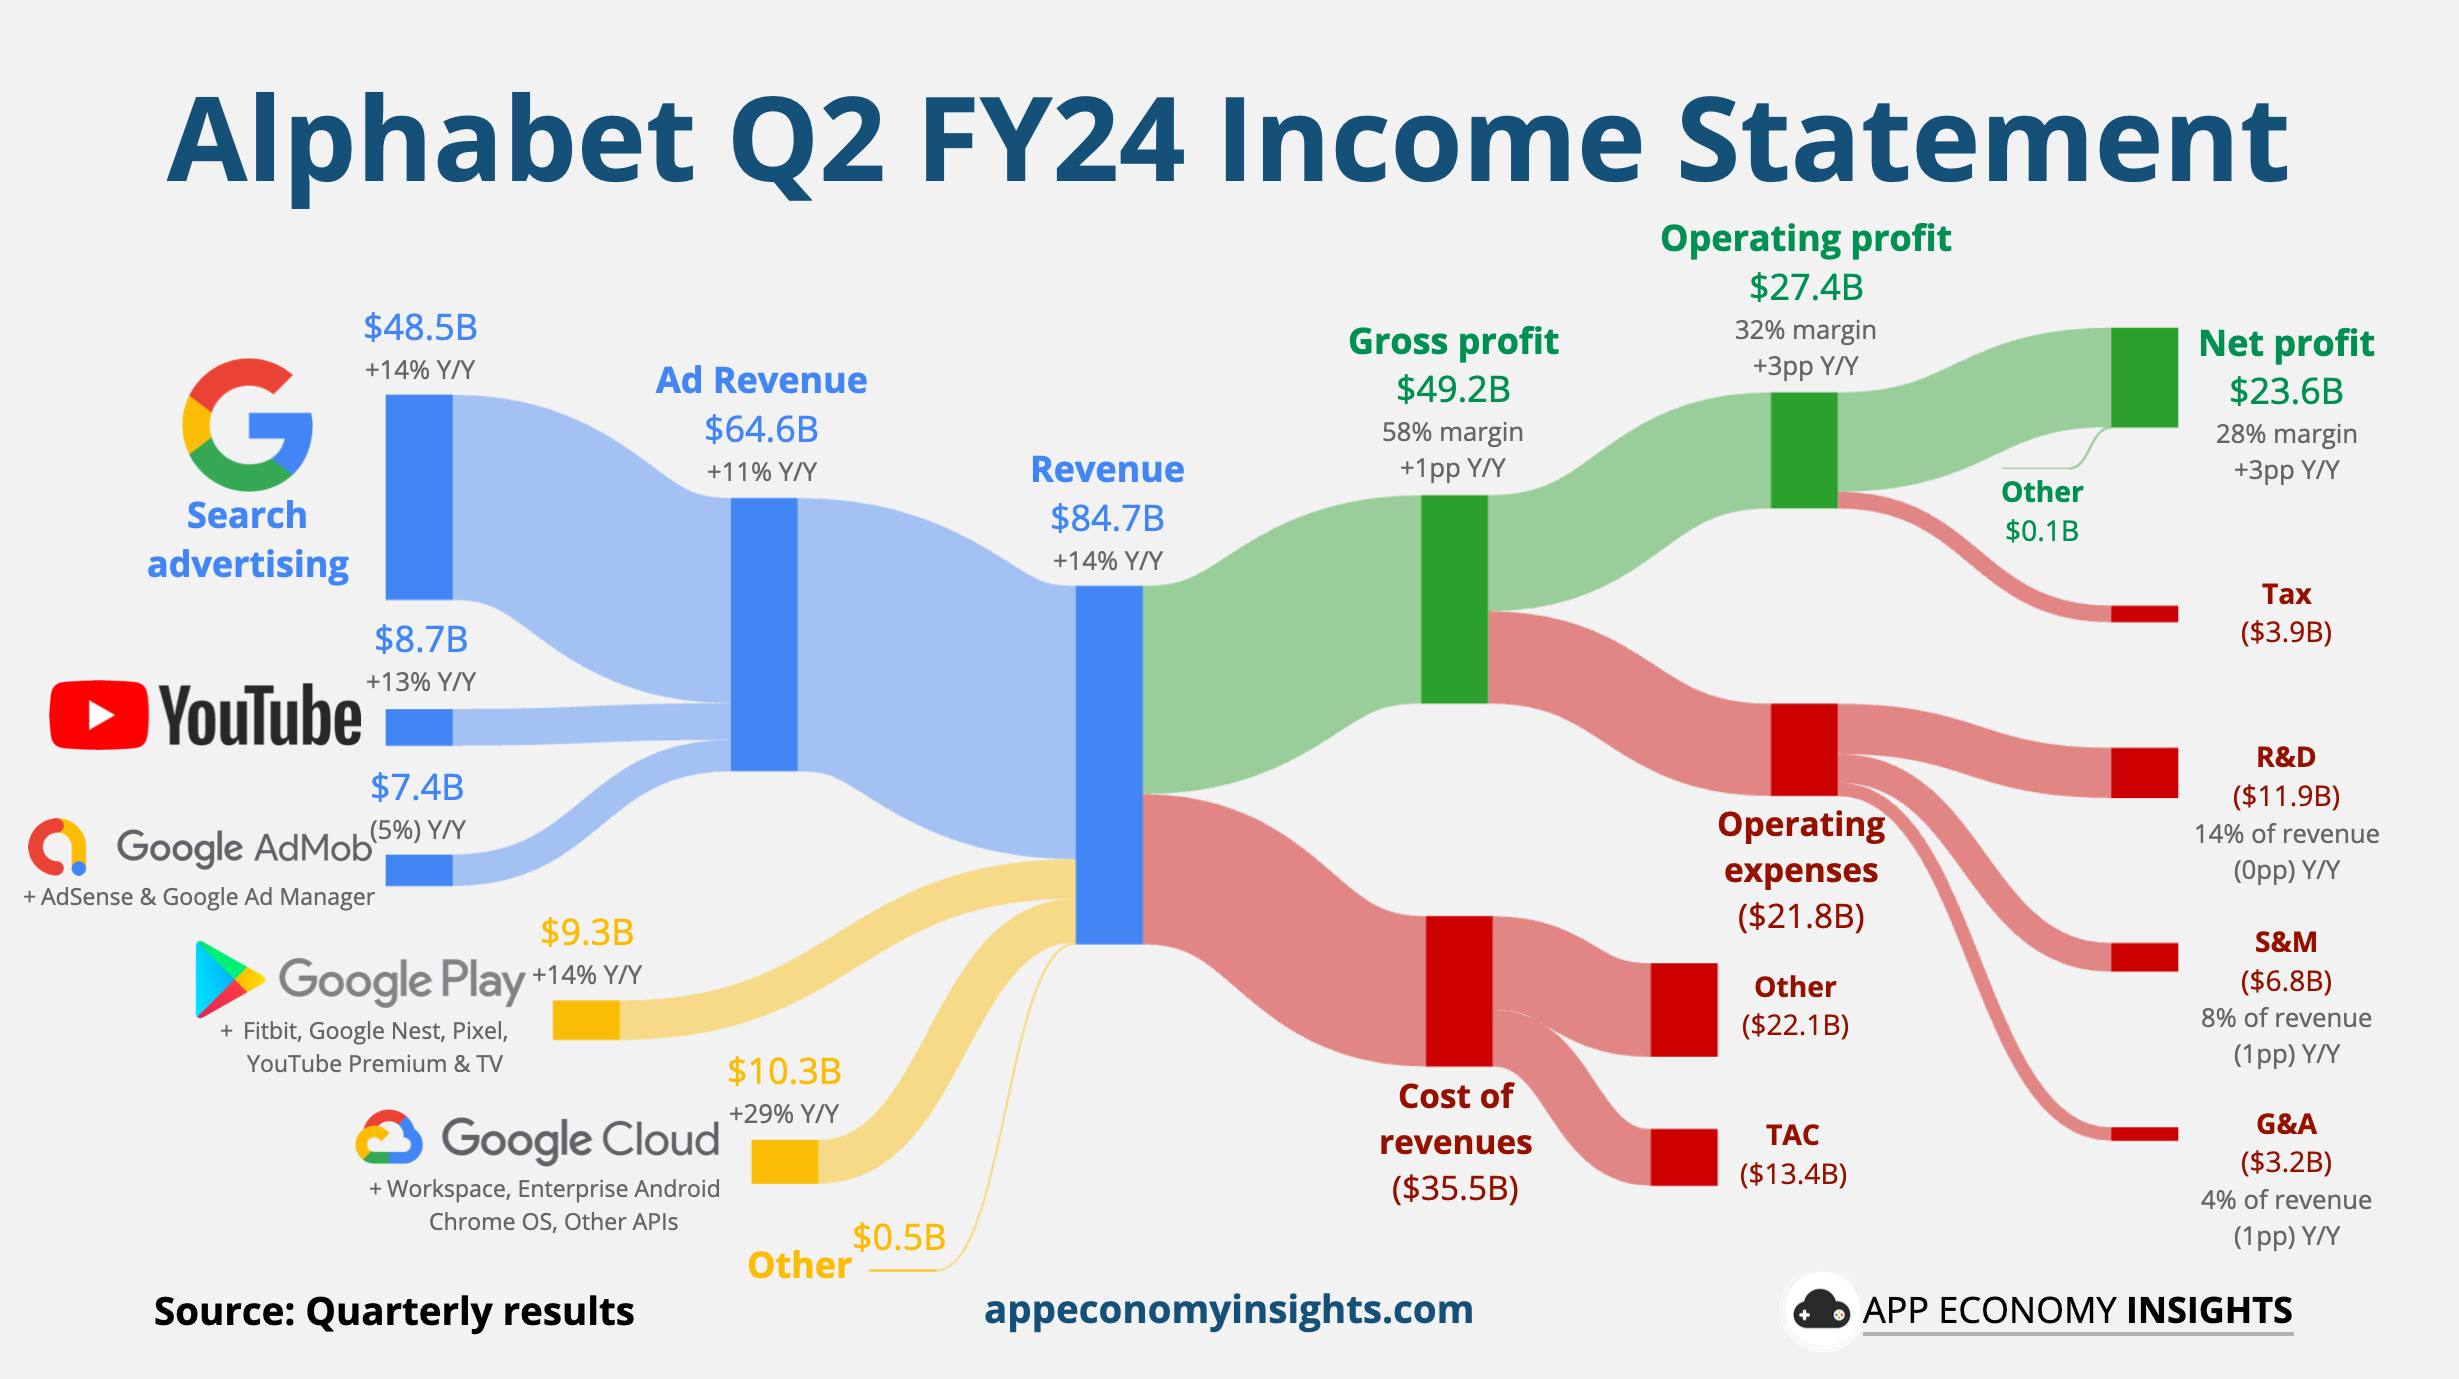
To understand the magnitude of the AI-related investment boom in Q3, one must examine the balance sheets of the major hyperscalers—Alphabet, Microsoft, Amazon, and Meta Platforms. Collectively, these entities poured tens of billions of dollars into specialized hardware, high-performance networking gear, and energy-intensive data center facilities. C-suite executives defended these aggressive capital expenditure budgets during earnings calls by pointing to immediate productivity gains and long-term risk mitigation against technological disruption.
However, this unprecedented capital allocation has ignited fierce debate among institutional investors regarding valuation multiples and amortization timelines. While the immediate macroeconomic impact is undeniably stimulative—boosting demand for semiconductor fabrication, power generation, electrical grid modernization, and specialized construction—analysts are closely monitoring asset utilization rates. Regulatory compliance requirements, power grid capacity constraints, and the eventual need to prove tangible enterprise ROI remain critical variables for future quarters.
Verified Macroeconomic & Sector Metrics: Q3 Performance Overview

The following matrix details key economic indicators, capital allocation volumes, and growth drivers underpinning third-quarter economic performance.
| Economic Indicator / Metric | Q3 Actual / Estimate | YoY Change / Basis Points | Primary Driver / Catalyst |
|---|---|---|---|
| Real GDP Growth (Annualized) | 2.8% - 3.0% | +30 bps vs. consensus | Strong personal consumption & business investment |
| Personal Consumption Expenditures (PCE) | Robust (+3.5% est.) | Steady real wage growth | Services sector demand & high-end retail resilience |
| Hyperscale AI Capital Expenditure | $50B+ (Combined Big Tech) | +45% YoY surge | Data center buildout & GPU cluster expansion |
| Corporate Credit Default Rates | Contained (2.4% High Yield) | Stable liquidity access | Refinancing resilience & robust market liquidity |
Industry & Market Implications: Winners and Losers
The macroeconomic polarization observed in the third quarter has created distinct bifurcation across global equity and debt markets. Institutional portfolio managers are actively rebalancing asset allocation models to reflect these structural realities.
Who Wins: Enterprise Tech, Semiconductors, and Premium Retail
- Semiconductor Manufacturers & Fabless Designers: Sustained demand for advanced AI accelerators, GPUs, and custom silicon continues to drive record-breaking fab utilization rates and pricing power.
- Cloud Infrastructure Providers: Hyperscalers monetizing enterprise AI workloads are capturing expanding market share, translating massive capex investments into recurring cloud subscription revenue.
- Experiential and Luxury Retailers: Companies catering to affluent consumer demographics continue to post healthy margins, benefiting from wealth effects tied to equity and housing market valuations.
Who Loses: Commercial Real Estate, Interest-Sensitive Sectors, and Subprime Lenders
- Commercial Real Estate (CRE): Legacy office properties face persistent valuation markdowns as remote work structural shifts combine with higher debt refinancing costs.
- Subprime Auto & Credit Card Issuers: Lenders exposed to lower-income consumer cohorts are experiencing rising delinquency rates, prompting tighter credit underwriting standards and increased provisions for credit losses.
- Energy-Constrained Industrial Operations: Heavy industrial players unable to secure affordable, reliable power allocations for automated or digital transformation initiatives risk margin erosion.
Frequently Asked Questions (People Also Ask)
Q: Why is consumer spending remaining so resilient despite high interest rates?
A: Consumer resilience is primarily driven by a robust labor market, steady nominal wage growth that has outpaced inflation, and substantial household balance sheet cushions accumulated by upper-middle and high-income brackets. While lower-income consumers face severe stress, the aggregate consumption figures remain heavily weighted toward affluent spenders.
Q: How much is artificial intelligence (AI) investment contributing to overall GDP growth?
A: AI-related investments—encompassing data center construction, specialized semiconductor procurement, power grid upgrades, and software architecture deployment—have contributed significantly to non-residential fixed investment figures, acting as a critical offset to slowdowns in traditional manufacturing and real estate sectors.
Q: What are the primary risk factors threatening this economic momentum?
A: Key systemic risks include potential tightening of corporate credit liquidity, energy infrastructure bottlenecks limiting data center expansion, rising consumer credit delinquencies among subprime cohorts, and geopolitical shocks impacting global supply chains and commodity pricing.
Q: Are tech companies seeing a tangible return on investment (ROI) from their massive AI capex?
A: While foundational infrastructure investments are massive, enterprise adoption is translating into growing cloud consumption and software monetization. However, Wall Street continues to scrutinize amortization schedules and the long-term timeline for realizing full commercial returns on multi-billion dollar cluster builds.
Future Outlook: Key Milestones to Watch Heading Into Year-End
As the global economy transitions into the final quarter of the fiscal year, executive leadership teams and macroeconomic strategists are pivoting focus toward several critical milestones. The trajectory of Federal Reserve monetary policy calibration, specifically regarding terminal interest rate cuts and balance sheet normalization, will heavily dictate borrowing costs for capital-intensive projects.
Furthermore, analysts will scrutinize upcoming corporate earnings guidance for concrete proof of sustained enterprise AI monetization and stable consumer spending patterns during the crucial holiday retail season. While the third quarter proved that innovation-led capital allocation and consumer durability can successfully defy historical recession playbooks, maintaining this equilibrium will require careful risk mitigation, prudent debt management, and disciplined capital allocation across both public and private sectors.