Semicon India 2026: Inside Micron, Tata, and Infineon’s Multi-Billion-Dollar Silicon Blitz
Executive Takeaways
- Capital Allocation & Mega-Investments: Global chipmakers like Micron, Infineon, and India's Tata Group have locked in aggressive timelines for expanding domestic semiconductor assembly, testing, and fabrication capabilities.
- Geopolitical & Supply Chain Risk Mitigation: Driven by enterprise demands for resilient supply chain diversification, India is rapidly transforming from a downstream consumer market into a foundational pillar of the global hardware stack.
- Infrastructure Scalability: State-level incentives, massive power and water allocations, and specialized talent pipelines are easing historical friction points in enterprise ROI for foreign fabless and IDM players.
- In-depth analysis by our Senior Bureau Chief examines valuation multiples, market liquidity, and the structural transformation of the South Asian semiconductor ecosystem.
The New Geopolitical Silicon Corridor: Setting the Stage for Semicon India 2026
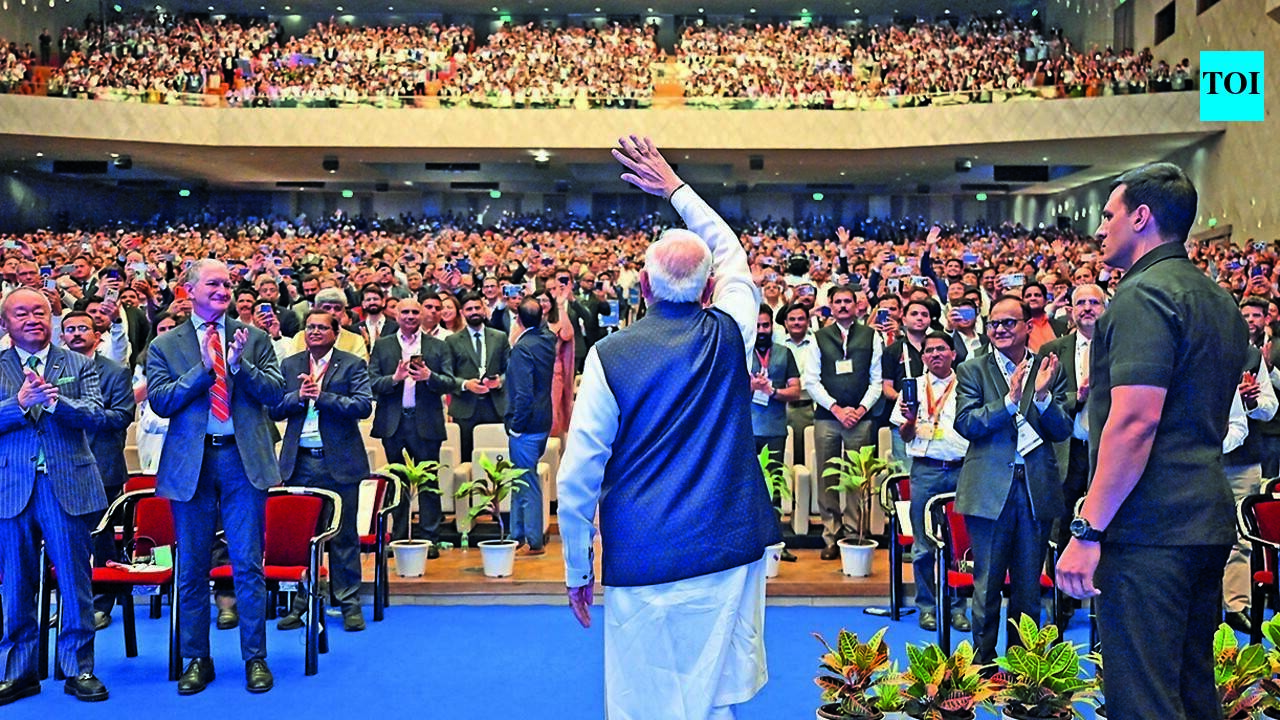
As corporate treasuries and venture capital syndicates recalibrate their exposure to single-jurisdiction manufacturing risks, the global semiconductor paradigm is undergoing a structural realignment. At the center of this capital expenditure super-cycle stands the Indian subcontinent. Emerging from decades of policy hesitation and infrastructure bottlenecks, the nation has aggressively deployed state-backed fiscal incentives to attract upstream and downstream semiconductor infrastructure. At the recent gathering leading up to Semicon India 2026, enterprise executives, sovereign wealth managers, and chief technology officers from Micron Technology, Tata Electronics, and Infineon Technologies outlined their next-generation roadmap for local expansion.
This unfolding narrative is no longer defined by exploratory memoranda of understanding or tentative pilot programs. Instead, it is characterized by deep capital allocation, long-term offtake agreements, and hard infrastructure deployment. For institutional investors evaluating valuation multiples in the semiconductor equipment, materials, and outsourced semiconductor assembly and test (OSAT) sectors, India represents a vital, high-growth frontier. The strategic imperative is clear: build regional manufacturing redundancy before macroeconomic shocks or regulatory friction forces a reactive pivot.
Micron, Tata, and Infineon: The Playbook for Localized Expansion

The operational blueprints presented by industry heavyweights at Semicon India 2026 reveal distinct strategic priorities, unified by a common goal: integrating South Asia into the high-margin global electronics supply chain.
1. Micron Technology: Scaling Up Advanced Packaging and Memory Production
Micron���s aggressive footprint expansion in Gujarat serves as the anchor project for India’s modern semiconductor ambitions. Following its initial announcements, the memory giant is moving rapidly past the ground-breaking phase into structural construction and equipment move-in schedules. For cloud compute architecture providers and enterprise server original equipment manufacturers (OEMs), Micron’s domestic production of DRAM and NAND products drastically reduces lead times.
By leveraging local fiscal subsidies and federal production-linked incentives (PLI), Micron is optimizing its capital expenditure model while securing long-term supply agreements with domestic mobile and automotive manufacturers. The technical complexities of operating an advanced assembly and test facility require robust regulatory compliance and localized talent acquisition—hurdles that Micron, in partnership with state and central authorities, is systematically clearing.
2. Tata Group: Crafting an End-to-End Silicon Ecosystem
No entity epitomizes India’s domestic industrial push quite like the Tata Group. Through Tata Electronics and strategic international partnerships, the conglomerate is executing a multi-pronged approach that spans greenfield OSAT facilities in Morigaon, Assam, and a full-scale semiconductor fabrication plant in Dholera, Gujarat, in collaboration with Taiwan's Powerchip Semiconductor Manufacturing Corp (PSMC).
Tata’s roadmap addresses historical market gaps by building a cohesive local ecosystem. From precision chemical supply chains to specialized engineering labor pools, Tata is mitigating supply chain vulnerabilities for global consumer electronics and automotive giants. Analysts tracking enterprise ROI note that Tata’s aggressive valuation strategy and balance sheet strength uniquely position it to absorb initial capital expenditure friction while long-term market liquidity matures.
3. Infineon Technologies: Powering Automotive and Industrial Transitions
As the global automotive industry accelerates its transition toward electric vehicles (EVs) and high-density power management systems, Infineon Technologies is doubling down on localized partnerships and design ecosystems within India. While Infineon’s primary capital-intensive wafer fabs remain anchored in Europe and Asia-Pacific, the company’s expansion at Semicon India 2026 centers on deepening collaborative engineering, software architecture, and power semiconductor module packaging.
Infineon’s strategy targets the burgeoning domestic EV market, renewable energy infrastructure, and industrial automation sectors. By embedding its semiconductor solutions directly into India’s industrial manufacturing core, Infineon secures a dominant market share in one of the world's fastest-growing middle-income consumer bases.
Verified Data & Metrics Breakdown: Semiconductor Expansion Milestones
To contextualize the velocity of capital deployment and industrial output projected for the 2026 horizon, the following matrix compares key operational metrics across the primary ecosystem stakeholders:
| Company | Primary Facility Location | Core Technology / Focus | Target Operational Timeline | Strategic Impact |
|---|---|---|---|---|
| Micron Technology | Sanand, Gujarat | DRAM/NAND Assembly & Test (OSAT) | Late 2024 – 2026 Full Ramp | Secures domestic memory supply for mobile & server OEMs. |
| Tata Electronics (with PSMC) | Dholera (Fab) & Morigaon (OSAT) | Mature nodes (28nm-nanometer) & Advanced Packaging | 2026–2028 Commercial Production | Establishes end-to-end domestic foundry sovereignty. |
| Infineon Technologies | Bengaluru / Regional Hubs | Power Semiconductors, Automotive Modules, R&D | Continuous Expansion through 2026 | Captures high-growth EV and renewable energy markets. |
Industry & Market Implications: Winners, Losers, and Economic Shifts
The institutional momentum displayed at Semicon India 2026 reverberates across global financial markets, altering competitive dynamics for established hubs while posing critical questions for legacy supply chains.
The Winners: Equipment Makers, Local Infrastructure, and Enterprise Buyers
Global semiconductor equipment manufacturers—specializing in lithography, etching, chemical vapor deposition (CVD), and automated test equipment—stand to capture substantial revenue upside as greenfield fabs break ground. Concurrently, Indian engineering, procurement, and construction (EPC) firms, along with specialized utility providers delivering ultra-pure water and uninterrupted power grids, are experiencing unprecedented valuation expansion.
For enterprise buyers, geographic diversification reduces existential supply chain tail risks. Procuring chips produced within a stable, politically aligned democracy shields multinational corporations from localized geopolitical flashpoints in traditional East Asian corridors.
The Losers: High-Cost Legacy Hubs Facing Margin Compression
Traditional manufacturing hubs that fail to modernize their fiscal incentive structures or streamline regulatory compliance risk facing margin compression. As global capital reallocates toward aggressive subsidy regimes in India, the US, and Europe, second-tier facilities in older jurisdictions must pivot toward ultra-specialized nodes or risk obsolescence. Furthermore, specialized talent scarcity remains a zero-sum game; engineering talent migrating toward newly established Indian design and manufacturing centers creates immediate operational headcounts deficits for overseas competitors.
Frequently Asked Questions (People Also Ask)
What is the primary objective of Semicon India 2026?
Semicon India serves as the premier annual nexus for policymakers, global chipmakers, and enterprise investors to review manufacturing roadmaps, finalize public-private partnerships, and accelerate the deployment of India’s multi-billion-dollar semiconductor infrastructure. The 2026 focus centers on transitioning from initial project announcements to active commercial production, technology transfer, and supply chain integration.
How are companies like Micron and Tata mitigating water and power infrastructure challenges?
Recognizing the intensive resource requirements of semiconductor fabrication—particularly ultra-pure water and zero-interruption power grids—state governments in Gujarat and Assam are coordinating directly with industrial conglomerates. Massive investments in dedicated desalination plants, wastewater recycling loops, and high-capacity dedicated transmission lines are being embedded directly into the foundational master plans of sites like Dholera and Sanand.
What manufacturing nodes are being prioritized in India’s initial fab wave?
While cutting-edge sub-3nm nodes remain concentrated in select global foundries, India's initial manufacturing wave heavily prioritizes mature and legacy nodes ranging from 28nm to 90nm, alongside advanced packaging and OSAT operations. These nodes form the foundational bedrock for automotive electronics, consumer appliances, power management ICs, and telecommunications infrastructure.
How does this impact global semiconductor equity valuations and market liquidity?
The influx of sovereign capital and multinational foreign direct investment (FDI) is expanding the total addressable market (TAM) for semiconductor equipment vendors and material suppliers. This capital expenditure boom supports resilient valuation multiples across participating conglomerates while opening new avenues for corporate debt issuance and equity market liquidity in South Asia.
Future Outlook: Milestones to Watch on the Road to 2030
As the dust settles on the announcements made at Semicon India 2026, the litmus test for the industry shifts from strategic rhetoric to execution excellence. Institutional investors, equity analysts, and macroeconomic strategists will monitor three critical milestones over the next 24 to 36 months:
- Equipment Move-In Dates: Adherence to construction timelines will dictate whether Micron and Tata can achieve volume commercial shipments on schedule. Delays in cleanroom certification or tool installation will serve as early warning indicators of operational friction.
- Ecosystem Localization Ratios: Tracking the percentage of raw materials, specialty gases, and chemical precursors sourced domestically versus imported will determine the true structural resilience of the Indian silicon corridor.
- Workforce Scale and Retention: The successful scaling of specialized university-industry curricula designed to churn out thousands of qualified semiconductor process engineers and technicians will make or break long-term operational profitability.
The transformation of India into an indispensable pillar of the global semiconductor architecture is no longer a theoretical projection—it is a heavily financed reality reshaping enterprise risk management, capital allocation, and international trade dynamics for the next decade.