Executive Takeaways
- Systemic Liquidity Shock: The BSE Sensex cratered 1,045.20 points to settle at 71,428.40, while the broader NSE Nifty 50 breached critical support to hit a fresh 52-week low at 21,579.15, wiping out over ₹4.2 trillion in investor market capitalization within a single trading session.
- Sustained Institutional Exodus: Foreign Institutional Investors (FIIs) offloaded a net ₹4,350 crore in cash equities, accelerating a multi-week capital rotation strategy away from elevated Indian valuation multiples into higher-yielding US Treasuries and discounted East Asian equities.
- Hawkish Monetary Squeeze: The Reserve Bank of India’s (RBI) prolonged stance on liquidity withdrawal—compounded by targeted macroprudential curbs on unsecured lending and strict bank loan-to-deposit ratio (LDR) compliance—has ignited an acute asset-liability repricing wave across private lenders and non-banking financial companies (NBFCs).
- Valuation Multiples Under Pressure: Midcap and smallcap segments suffered outsized drawdowns, reflecting institutional de-grossing and systemic margin calls as the aggregate price-to-earnings (P/E) premium of Indian equities faces severe recalibration against elevated debt yields.
Anatomy of the Crash: Dalal Street’s Structural Breakdown
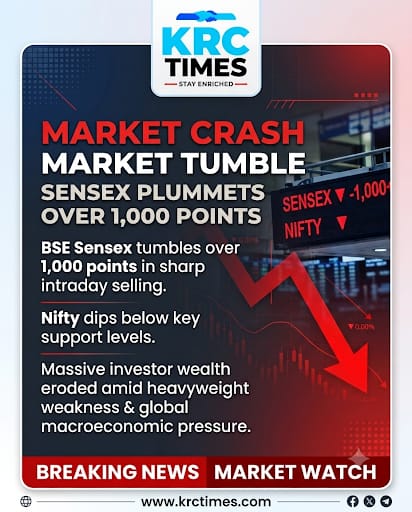
Trading floors across Mumbai, Singapore, and London witnessed aggressive institutional de-risking as opening bell optimism rapidly dissolved into systemic selling pressure. The benchmark BSE Sensex collapsed by 1,045 points, characterized by heavy automated algorithmic liquidation as key quantitative support levels were breached sequentially. The benchmark NSE Nifty 50, long considered the bastion of emerging market resilience, cracked below its 200-day moving average to log a fresh 52-week low, igniting automated stops across institutional prime brokerages.
The market breadth deteriorated to alarming levels, with the advance-decline ratio tilting drastically to 1:4. Over 2,600 stocks listed on the Bombay Stock Exchange closed deep in the red. This capitulation was not an isolated sentiment shock; it marks the culmination of structural cross-asset headwinds. High-beta financial heavyweights, which maintain the highest index weighting across Dalal Street, served as the primary epicenter of the downturn. When tier-one banking conduits fail to find institutional bids, the cascading impact on cash equity indices is both immediate and structurally damaging.
The institutional order book revealed that domestic institutional investors (DIIs), who have historically deployed domestic mutual fund systematic investment plan (SIP) inflows to cushion foreign outflows, failed to absorb the sheer velocity of the selling. As domestic fund managers stepped back to recalibrate their cash deployment strategies, bid-ask spreads widened substantially, leaving liquidity-sensitive equities exposed to aggressive algorithmic markdowns.
The Double-Barrel Catalyst: Unrelenting FII Flight and RBI Hawkishness
Two primary macroeconomic engines fueled the market's descent: the relentless exit velocity of Foreign Institutional Investors (FIIs) and the uncompromising regulatory and monetary stance orchestrated by the Reserve Bank of India.
1. Institutional Capital Allocation & Cross-Border Arbitrage
The macroeconomic thesis that supported record-setting Indian equity valuations throughout the prior fiscal year has encountered significant friction. With the US 10-year Treasury yield consolidating near 4.30% and real yields in the United States offering historically safe returns, global asset allocators are reassessing their emerging market equity risk premiums. The valuation spread between the Nifty 50—trading at an expensive 21.5 times forward earnings prior to this correction—and undervalued alternatives like the Hang Seng (trading sub-9x forward earnings) has widened beyond historical standard deviations.
Foreign portfolio managers are executing a tactical asset allocation pivot: monetizing extended gains in Mumbai to fund long positions in cheaper, mean-reverting geographies, or parking liquidity directly in dollar-denominated short-duration paper. In parallel, the continuous depreciation pressure on the Indian Rupee (INR), which hovered near all-time lows against the greenback, has eroded unhedged foreign returns, compelling global macro hedge funds to systematically trim their emerging market equity exposure.
2. The Domestic Squeeze: Quantitative Tightening and LDR Scrutiny
Simultaneously, the domestic banking architecture is confronting the consequences of the Reserve Bank of India’s aggressive liquidity absorption framework. RBI Governor Shaktikanta Das has maintained an unyielding hawkish posture regarding persistent headline inflation and elevated systemic liquidity. Through active variable rate reverse repo (VRRR) auctions and rigorous currency market interventions, the central bank has engineered a structurally tight domestic liquidity environment.
More critically, the RBI’s macroprudential intervention targeting bank loan-to-deposit ratios (LDRs) and elevated risk weights on unsecured retail loans has fundamentally altered banking sector balance sheets. With top-tier private sector banks operating at LDRs hovering near historical peaks of 85% to 90%, banks are facing severe structural deposit constraints. To fund credit growth, institutions are being forced to aggressively bid for retail deposits, compressing Net Interest Margins (NIMs) and triggering broad earnings downgrades across the financial sector.
Comparative Market Metrics: The Pre-Crash vs. Liquidation Reality
| Financial Metric / Market Indicator | Pre-Correction Level (Trailing Month) | Liquidation Day Value | Delta / Basis Point Impact |
|---|---|---|---|
| BSE Sensex Benchmark | 72,473.60 | 71,428.40 | -1,045.20 pts (-1.44%) |
| NSE Nifty 50 Benchmark | 21,950.00 | 21,579.15 (52-Week Low) | -370.85 pts (-1.69%) |
| India VIX (Volatility Index) | 13.25 | 15.80 | +19.25% (Volatility Spike) |
| FII Net Daily Cash Position (INR) | -₹1,200 Crore (Avg. Run-Rate) | -₹4,350 Crore | -₹3,150 Crore Outflow Surge |
| Nifty 50 Forward Price-to-Earnings (P/E) | 21.8x | 20.4x | -140 bps (Multiple Compression) |
| Indian 10-Year Benchmark Bond Yield | 7.05% | 7.12% | +7 bps (Cost of Capital Increase) |
| USD/INR Spot Rate | 82.95 | 83.38 | +43 bps (Depreciation Pressure) |
Sectoral Carnage: Where Enterprise Value Dissolved
The single-session rout revealed deep-seated structural fault lines across multiple sectors, moving far beyond mere surface-level equity corrections.
Banking and Non-Banking Financial Companies (NBFCs)
The Bank Nifty index absorbed the most violent blow, declining over 2.1%. Leading private sector behemoths suffered heavy capitalization losses. Market participants have swiftly marked down future credit growth forecasts as the cost of institutional funds climbs. NBFCs, particularly those relying heavily on bank borrowings to underwrite microfinance, consumer durables, and personal credit lines, were heavily punished. Elevated risk-weighted asset requirements set by the central bank are now biting directly into return on equity (RoE) projections.
Information Technology: Caught in Cross-Currents
India’s IT services sector, historically positioned as a defensive safe haven during currency depreciations, failed to decouple from the broader market slide. Persistent delays in enterprise cloud compute architecture spending across Fortune 500 clients, coupled with margin compression and cautious guidance on discretionary tech expenditure, have neutralized the standard tailwinds provided by a weakening rupee. The Nifty IT index shed 1.6%, as foreign funds divested holdings to free up liquid dollar capital.
The Midcap and Smallcap Liquidity Trap
While headline indices reflected severe pressure, the real carnage played out across broader market portfolios. Midcap and smallcap multiples had swelled to unprecedented premiums over historical averages, driven by heavy retail inflows. As large-cap institutions triggered stop-losses, the broader market experienced an acute liquidity crunch. Retail and high-net-worth investors, faced with intraday margin maintenance calls, were forced into automated asset sales, triggering a cascade of lower circuit breakers across highly speculative smallcap equities.
Macroeconomic and Enterprise Repercussions
The implications of this market dislocation extend beyond secondary equity market trading screens; they strike directly at corporate enterprise balance sheets, capital formation, and sovereign fiscal dynamics:
- Chilling of the Primary Equity (IPO) Pipeline: Multiple late-stage growth enterprises and private-equity-backed firms seeking domestic public listings are being forced to delay their Draft Red Herring Prospectus (DRHP) filings. Depressed valuation multiples make secondary share sales unattractive for existing investors and make primary capital raises significantly more dilutive.
- Escalating Corporate Cost of Capital: With sovereign yields ticking upward to 7.12% and liquidity tightening, the corporate bond market is pricing in wider credit spreads. Chief Financial Officers (CFOs) face higher weighted-average costs of capital (WACC), which threatens to slow the anticipated private-sector capital expenditure (CapEx) cycle.
- Asset-Liability Management (ALM) Friction: Commercial banks are now in a direct price war for term deposits. This structural dynamic leaves treasury desks with mark-to-market bond portfolio hits while simultaneously squeezing enterprise loan spreads.
Market Winners and Losers
The Losers
- Leveraged Financials & FinTech Lenders: Institutions dependent on high-volume unsecured credit expansion and short-term debt paper face acute margin compression and regulatory friction.
- Capital-Intensive Cyclicals: Infrastructure and capital goods companies that require cheap, continuous debt financing are witnessing an immediate rise in projected financing costs.
- Retail Margin Traders: Highly leveraged domestic retail participants holding long derivative positions across index and single-stock futures absorbed catastrophic capital losses due to gap-down liquidations.
The Strategic Winners
- Cash-Rich Global Multinationals: Conglomerates holding significant cash reserves on their balance sheets are positioned to negotiate superior vendor pricing, acquire distressed niche assets, and earn elevated yields on short-term liquid treasury investments.
- Defensive Export Plays (Select Pharma): Export-oriented pharmaceutical companies with negligible domestic debt exposures and high dollar receivables served as the few green spots on trading terminals, providing classical defensive insulation.
- Fixed-Income Arbitrage and Systematic Short Desks: Quantitative macro hedge funds that initiated directional short positions against high-multiple midcaps captured substantial intraday risk-adjusted returns.
Frequently Asked Questions (People Also Ask)
Why did the Sensex fall over 1,000 points in a single session?
The acute crash was driven by a combination of aggressive foreign institutional investor (FII) capital flight, the RBI’s ongoing liquidity withdrawal framework, and a sharp spike in US Treasury yields. When the Nifty and Sensex breached technical support, algorithmic stop-losses and automated retail margin liquidations compounded the initial selling wave, turning a standard macro rotation into an outright rout.
How does RBI monetary policy tightening directly impact equity valuation multiples?
When the Reserve Bank of India tightens liquidity—via elevated repo rates, VRRR auctions, and increased risk weights on unsecured lending—the cost of domestic capital rises. In modern discounted cash flow (DCF) models, higher discount rates inherently lower the present enterprise value of future corporate earnings. Furthermore, tight liquidity compels banks to hike deposit rates, which compresses corporate margins and prompts institutional investors to shift capital away from equities into risk-free fixed-income instruments.
Will Foreign Institutional Investors (FIIs) continue their selling spree in Indian equities?
FII activity remains dictated by global interest rate differentials and relative regional valuations. As long as US 10-year yields remain elevated and Indian equities trade at premium historical multiples relative to emerging market peers, foreign asset allocators are likely to maintain a defensive posture. Significant institutional inflows will likely require an explicit dovish turn from global central banks or a substantial valuation correction in Indian blue-chip stocks.
What key support levels should market participants watch for a Nifty stabilization?
Technical and quantitative institutional desks are tracking the 21,300 to 21,450 zone as the immediate defensive base for the Nifty 50. A failure to consolidate within this pocket could expose the index to a deeper structural test down to the 20,800 psychological threshold, where valuation multiples align more closely with historical five-year averages.
Future Outlook: Strategic Milestones to Monitor
The roadmap for Indian financial markets over the coming quarters hinges on several distinct macroeconomic catalysts. Institutional trading desks are heavily focused on the minutes of the upcoming RBI Monetary Policy Committee (MPC) meeting to gauge whether the central bank will introduce liquidity-easing measures or maintain its restrictive stance to suppress food and headline inflation.
Concurrently, the trajectory of US Federal Reserve policy and the subsequent behavior of the US Dollar Index (DXY) will dictate foreign institutional flows. If dollar yields consolidate, Dalal Street may construct a durable valuation floor. However, should geopolitical friction or persistent domestic liquidity deficits continue to widen the credit-to-deposit gap, the current 52-week lows in the Nifty may not represent a structural bottom, but rather the opening chapter of a broader corporate earnings and equity multiple reset.