Executive Takeaways
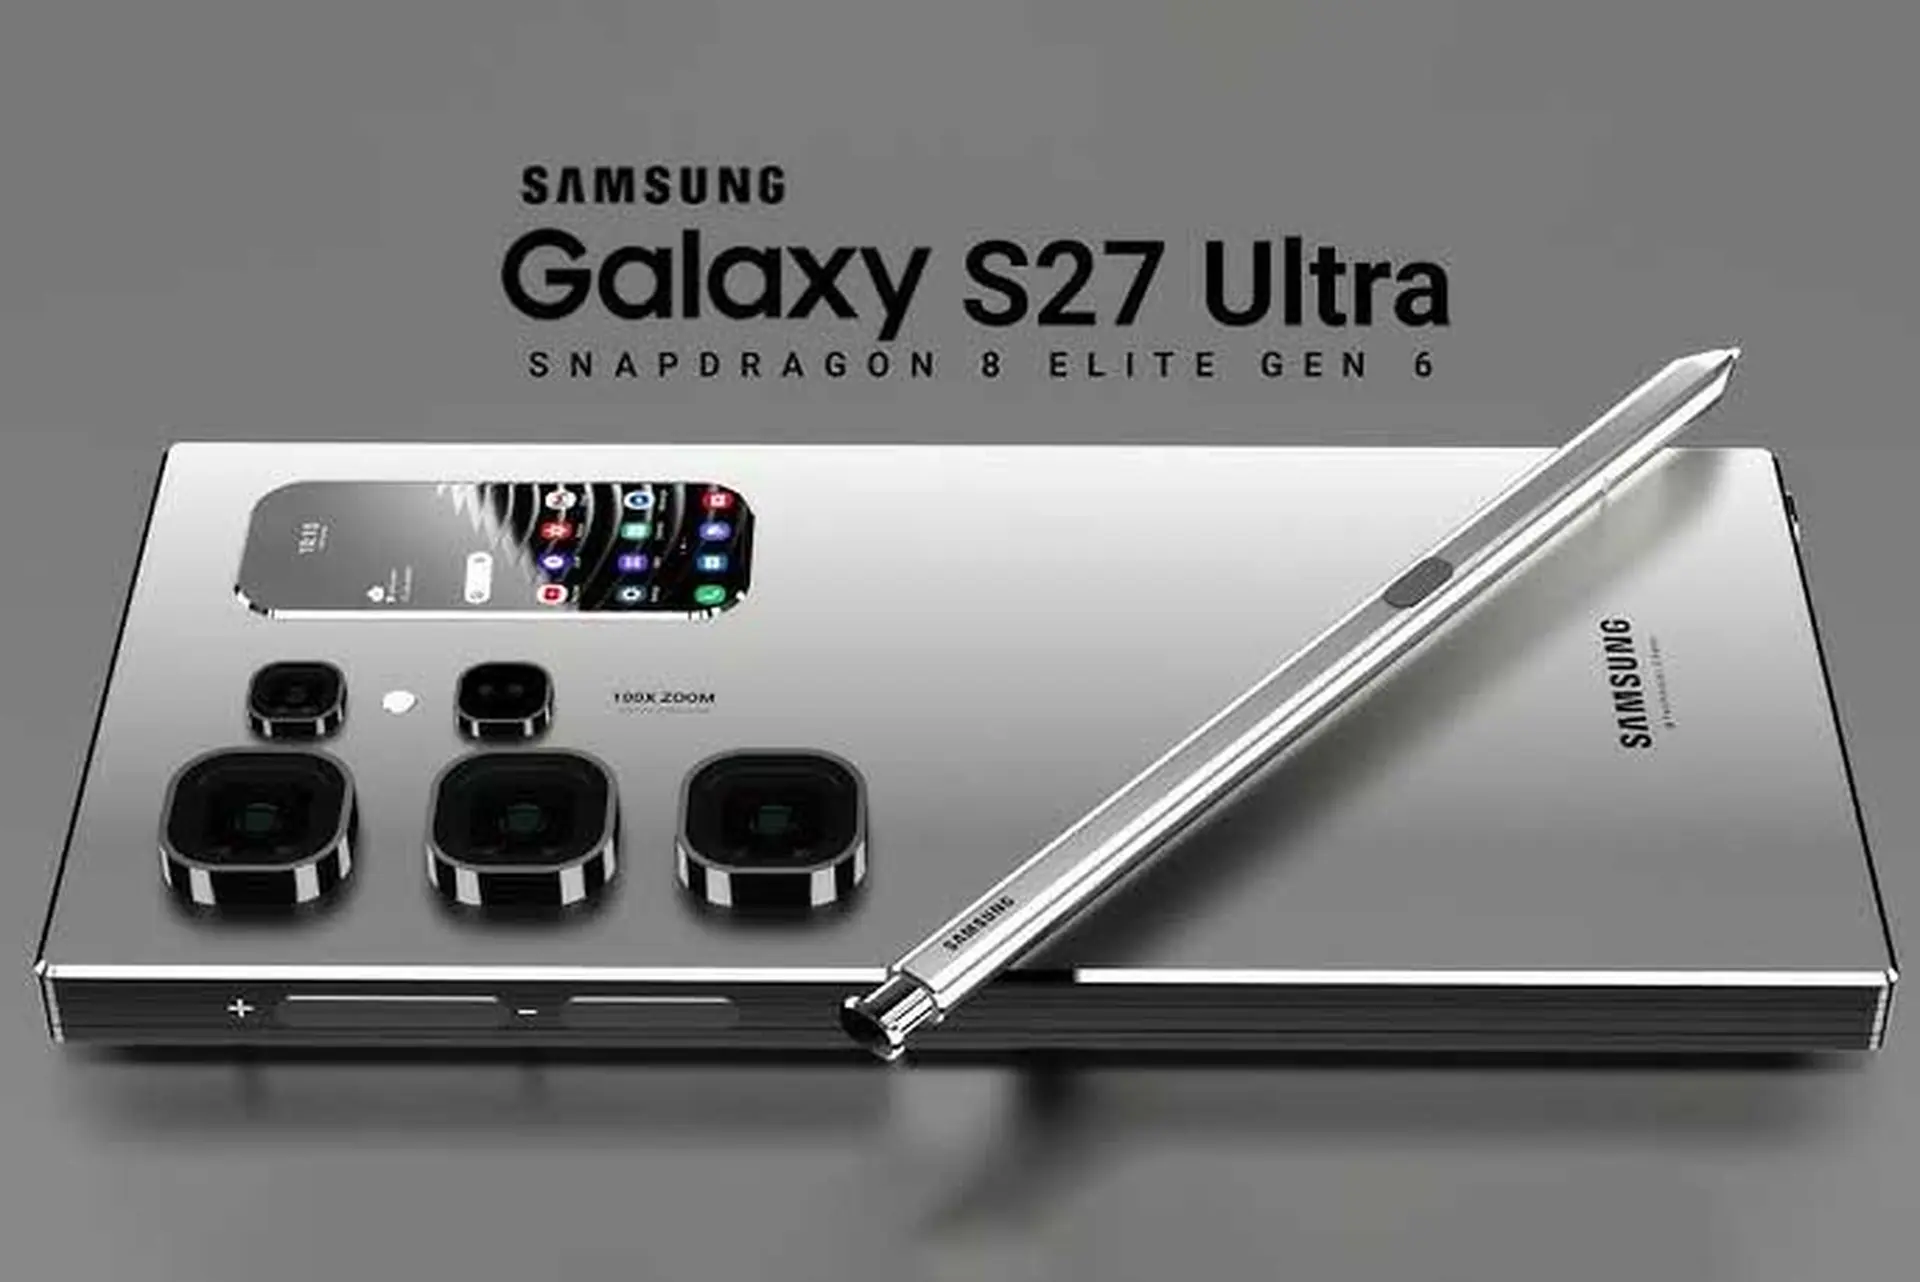
- Silicon Diversification Strategy: Samsung is aggressively pivoting its foundry and procurement roadmaps for the upcoming Galaxy S27 Ultra, balancing supply chain resilience with aggressive cost optimization.
- Valuation and Margin Impact: Component bifurcation directly affects capital allocation, bill-of-materials (BOM) costs, and operating margins across Samsung's Mobile eXperience (MX) division.
- Foundry Competitiveness: The internal battle between Samsung Foundry’s 2nm gate-all-around (GAA) nodes and external foundry partners like TSMC dictates flagship performance parity.
- Enterprise ROI & Market Liquidity: High-end smartphone pricing power and enterprise upgrade cycles depend heavily on thermal efficiency, NPU throughput, and sustained compute performance.
The global semiconductor ecosystem is once again holding its breath as fresh developments emerge from Seoul and Taipei regarding Samsung’s flagship hardware roadmap. The ongoing saga surrounding the processing architecture of the future Galaxy S27 Ultra has taken yet another dramatic turn, transforming what is typically a standard component sourcing cycle into a high-stakes chess match of corporate finance, geopolitical supply chain maneuvering, and advanced foundry engineering.
As institutional investors, supply chain analysts, and enterprise technology leaders scrutinize every leak and regulatory filing, the core question remains: Will Samsung double down on in-house silicon manufacturing via its proprietary Exynos architecture, or will it capitulate to market demands for universal Qualcomm Snapdragon integration? The latest twist reported across industry wires underscores the volatile economics of mobile computing, where a single architectural choice can swing billions of dollars in valuation multiples, capital expenditure returns, and market share across key geographic territories.
Background and Catalytic Events: The Anatomy of a Sourcing Crisis
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the gravity of the current Galaxy S27 Ultra chipset saga, one must examine the historical precedent set by Samsung’s dual-sourcing strategy. For years, the conglomerate has walked a tightrope between its System LSI division—responsible for designing Exynos processors—and its reliance on external partners such as Qualcomm and Taiwan Semiconductor Manufacturing Company (TSMC). This strategy of regional bifurcation, where certain markets receive Snapdragon-powered units while others receive Exynos variants, has historically been deployed as a risk-mitigation tool against supply shocks and margin compression.
However, consumer sentiment and enterprise benchmarks have increasingly penalized performance disparities between these two distinct silicon families. When thermal throttling or graphics processing unit (GPU) discrepancies surface between regional variants, the resulting backlash directly impacts flagship sales velocity and brand equity. Consequently, when initial rumors suggested that Samsung might completely abandon its in-house foundry efforts for the ultra-premium tier, tech markets reacted with bullish optimism regarding potential yield stability and enterprise ROI.
The latest twist, however, upends those assumptions. Industry insiders reveal that Samsung's executive board has refused to abandon its next-generation proprietary node development, choosing instead to bankroll a high-risk, high-reward integration of its advanced 2nm gate-all-around (GAA) manufacturing process. This decision has sent ripples through the capital markets, forcing analysts to re-evaluate Samsung Foundry’s cash burn rate, technological viability, and long-term viability as a tier-1 merchant foundry competitor to TSMC.
Deep-Dive Breakdown: Engineering, Economics, and Architecture
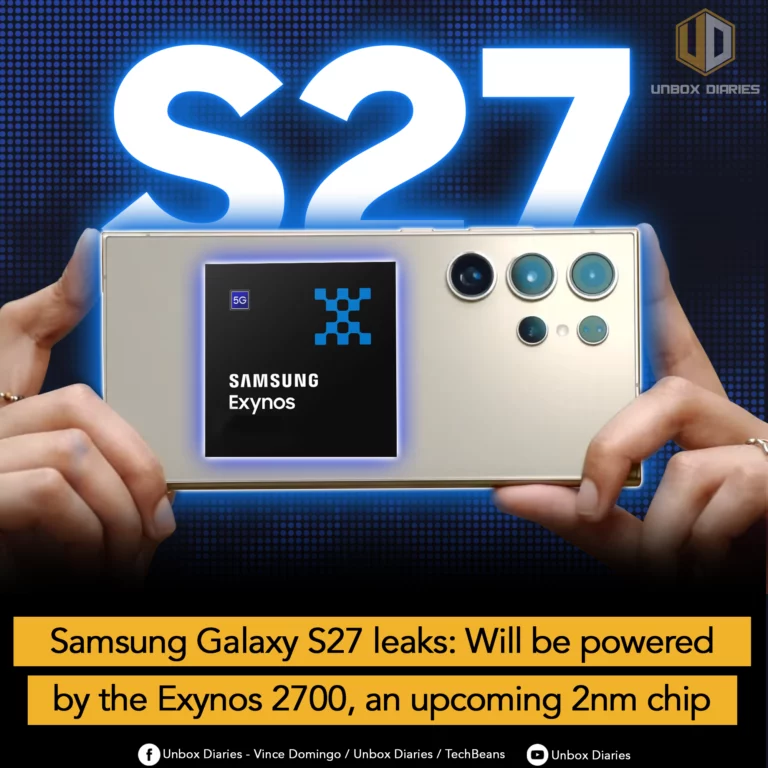
At the heart of this saga lies a complex intersection of semiconductor physics and corporate accounting. Designing a flagship system-on-chip (SoC) for a device like the Galaxy S27 Ultra requires immense upfront capital expenditure (CapEx) in research and development (R&D), lithography equipment, and cleanroom infrastructure.
The technical parameters governing the next-generation Exynos and Snapdragon architectures focus heavily on neural processing unit (NPU) throughput for on-device generative artificial intelligence, advanced thermal dissipation, and power envelope efficiency. Transitioning to sub-3nm and 2nm production nodes introduces severe yield challenges. When wafer defect densities remain stubbornly high, the unit economic cost of each functional die skyrockets, squeezing Samsung MX's operating margins.
| Metric / Parameter | Legacy Approach (Galaxy S25/S26 Era) | Latest Twist Strategy (Galaxy S27 Ultra Outlook) | Strategic Business Impact |
|---|---|---|---|
| Foundry Partner Allocation | Heavy reliance on TSMC N3 nodes for global variants; limited Exynos use. | Re-introduction of internal 2nm GAA trials alongside external Qualcomm orders. | Improves foundry utilization rates but elevates yield risk. |
| Bill of Materials (BOM) Cost | Elevated external chipset procurement costs impacting gross margins. | Hybrid model aimed at curbing external pricing leverage from Qualcomm. | Long-term margin stabilization if internal yields meet targets. |
| AI Compute Architecture | Standardized NPU integration across regional models. | Proprietary multi-core NPU accelerators optimized for edge-AI processing. | Enhances enterprise appeal for secure, localized data workloads. |
| Supply Chain Risk Mitigation | Moderate exposure to single-source foundry bottlenecks in Taiwan. | Geographic and infrastructural diversification across domestic and offshore fabs. | Superior regulatory compliance and business continuity resilience. |
Industry & Market Implications: Winners, Losers, and Economic Ripple Effects
The repercussions of Samsung’s strategic pivots extend far beyond its own assembly lines, creating clear victors and casualties across the global technology landscape.
The Winners
- Semiconductor Equipment Manufacturers: Companies providing extreme ultraviolet (EUV) lithography systems, deposition tools, and automated optical inspection systems stand to benefit from Samsung’s continued capital investment in 2nm node readiness.
- Enterprise IT Buyers: A more competitive chipset market forces continuous innovation in energy efficiency and security processing, providing corporate fleets with superior device longevity and reduced total cost of ownership (TCO).
The Losers
- Short-Term Margin Stability: Samsung’s System LSI division faces immense operational pressure to prove that its proprietary silicon can match the thermal and computational benchmarks set by competitors without destroying divisional profitability.
- Supply Chain Predictability: Procurement planners must navigate shifting production schedules and dual-track inventory management, increasing operational complexity.
From a macroeconomic perspective, this saga highlights the precarious nature of advanced manufacturing. In an era where sovereign states are pouring billions into domestic semiconductor subsidies (such as the US CHIPS Act and European Chips Act), corporate capital allocation must constantly balance geopolitical incentives against pure economic efficiency.
Frequently Asked Questions (People Also Ask)
What is the core issue behind the Galaxy S27 Ultra chipset saga?
The saga revolves around Samsung's ongoing dilemma regarding whether to use its in-house Exynos processors (manufactured via its proprietary foundry nodes) or rely exclusively on external suppliers like Qualcomm and TSMC. The debate centers on achieving performance parity, managing component costs, and ensuring supply chain resilience.
How does this chipset strategy impact Samsung's financial performance?
Chipset sourcing directly influences the Bill of Materials (BOM) and gross operating margins. Relying entirely on external suppliers increases procurement expenses, whereas developing proprietary silicon involves massive upfront capital expenditures and yield risks that can temporarily depress divisional profitability.
Will all regional variants of the Galaxy S27 Ultra feature the same processor?
While definitive final specifications have not been officially locked by Samsung executives, industry consensus points toward a continued hybrid or carefully managed regional distribution strategy, depending on final yield metrics and regulatory certification milestones.
Why is the transition to 2nm GAA technology so critical for Samsung?
The 2nm gate-all-around (GAA) architecture represents the bleeding edge of semiconductor manufacturing. Successful implementation allows for significantly higher transistor densities, improved power efficiency, and enhanced neural processing capabilities essential for next-generation mobile artificial intelligence workloads.
Future Outlook and Key Milestones to Watch
As the timeline toward the commercial launch of the Galaxy S27 Ultra accelerates, market watchers and institutional analysts must monitor several critical leading indicators:
- Foundry Yield Reports: Early-stage test wafer defect densities reported by Samsung Foundry will dictate whether proprietary Exynos chips make the final cut for flagship devices.
- Qualcomm Contractual Filings: SEC disclosures and partner earnings calls will reveal the pricing power and volume commitments agreed upon between Samsung and external chipmakers.
- Enterprise Benchmark Leaks: Independent thermal, battery drain, and NPU benchmark data will ultimately determine consumer reception and enterprise procurement willingness.
Ultimately, the Galaxy S27 Ultra chipset saga is much more than a routine hardware rumor cycle—it is a bellwether for the future of mobile computing economics. How Samsung navigates this high-stakes engineering and financial labyrinth will set the strategic playbook for the entire consumer electronics industry for the remainder of the decade.