NEW YORK — In the high-stakes theater of semiconductor engineering, physical dimensions are measured not merely in angstroms, but in geopolitical leverage, valuation multiples, and the future viability of the digital economy. According to primary wire disclosures originating from Quantum Zeitgeist, International Business Machines (IBM) has achieved a watershed milestone: the successful fabrication and testing of the world’s first semiconductor built at the 0.7-nanometer, or 7-angstrom, node.
This development shatters conventional wisdom regarding quantum tunneling limits and gate-all-around (GAA) structural integrity. By pushing the boundaries down to sub-1 nanometer scales, IBM’s research division has unlocked a verified 50% performance-per-watt advantage over reigning 2nm architectures. For institutional investors, hedge fund managers, and enterprise chief technology officers, this breakthrough is not academic; it is a disruptive catalyst that will fundamentally alter capital allocation, infrastructure scalability, and the competitive positioning of global silicon foundries over the next decade.
The Anatomy of the Breakthrough: How IBM Defied Physics
For decades, Wall Street analysts and semiconductor physicists have tracked the decelerating cadence of Moore’s Law—the empirical observation that transistor density doubles roughly every two years. As nodes shrank from 7nm to 3nm and subsequently approached 2nm, the industry ran headfirst into the terrifying reality of quantum mechanics: electrons leaking across ultra-thin barriers, generating prohibitive thermal loads and threatening total operational failure.
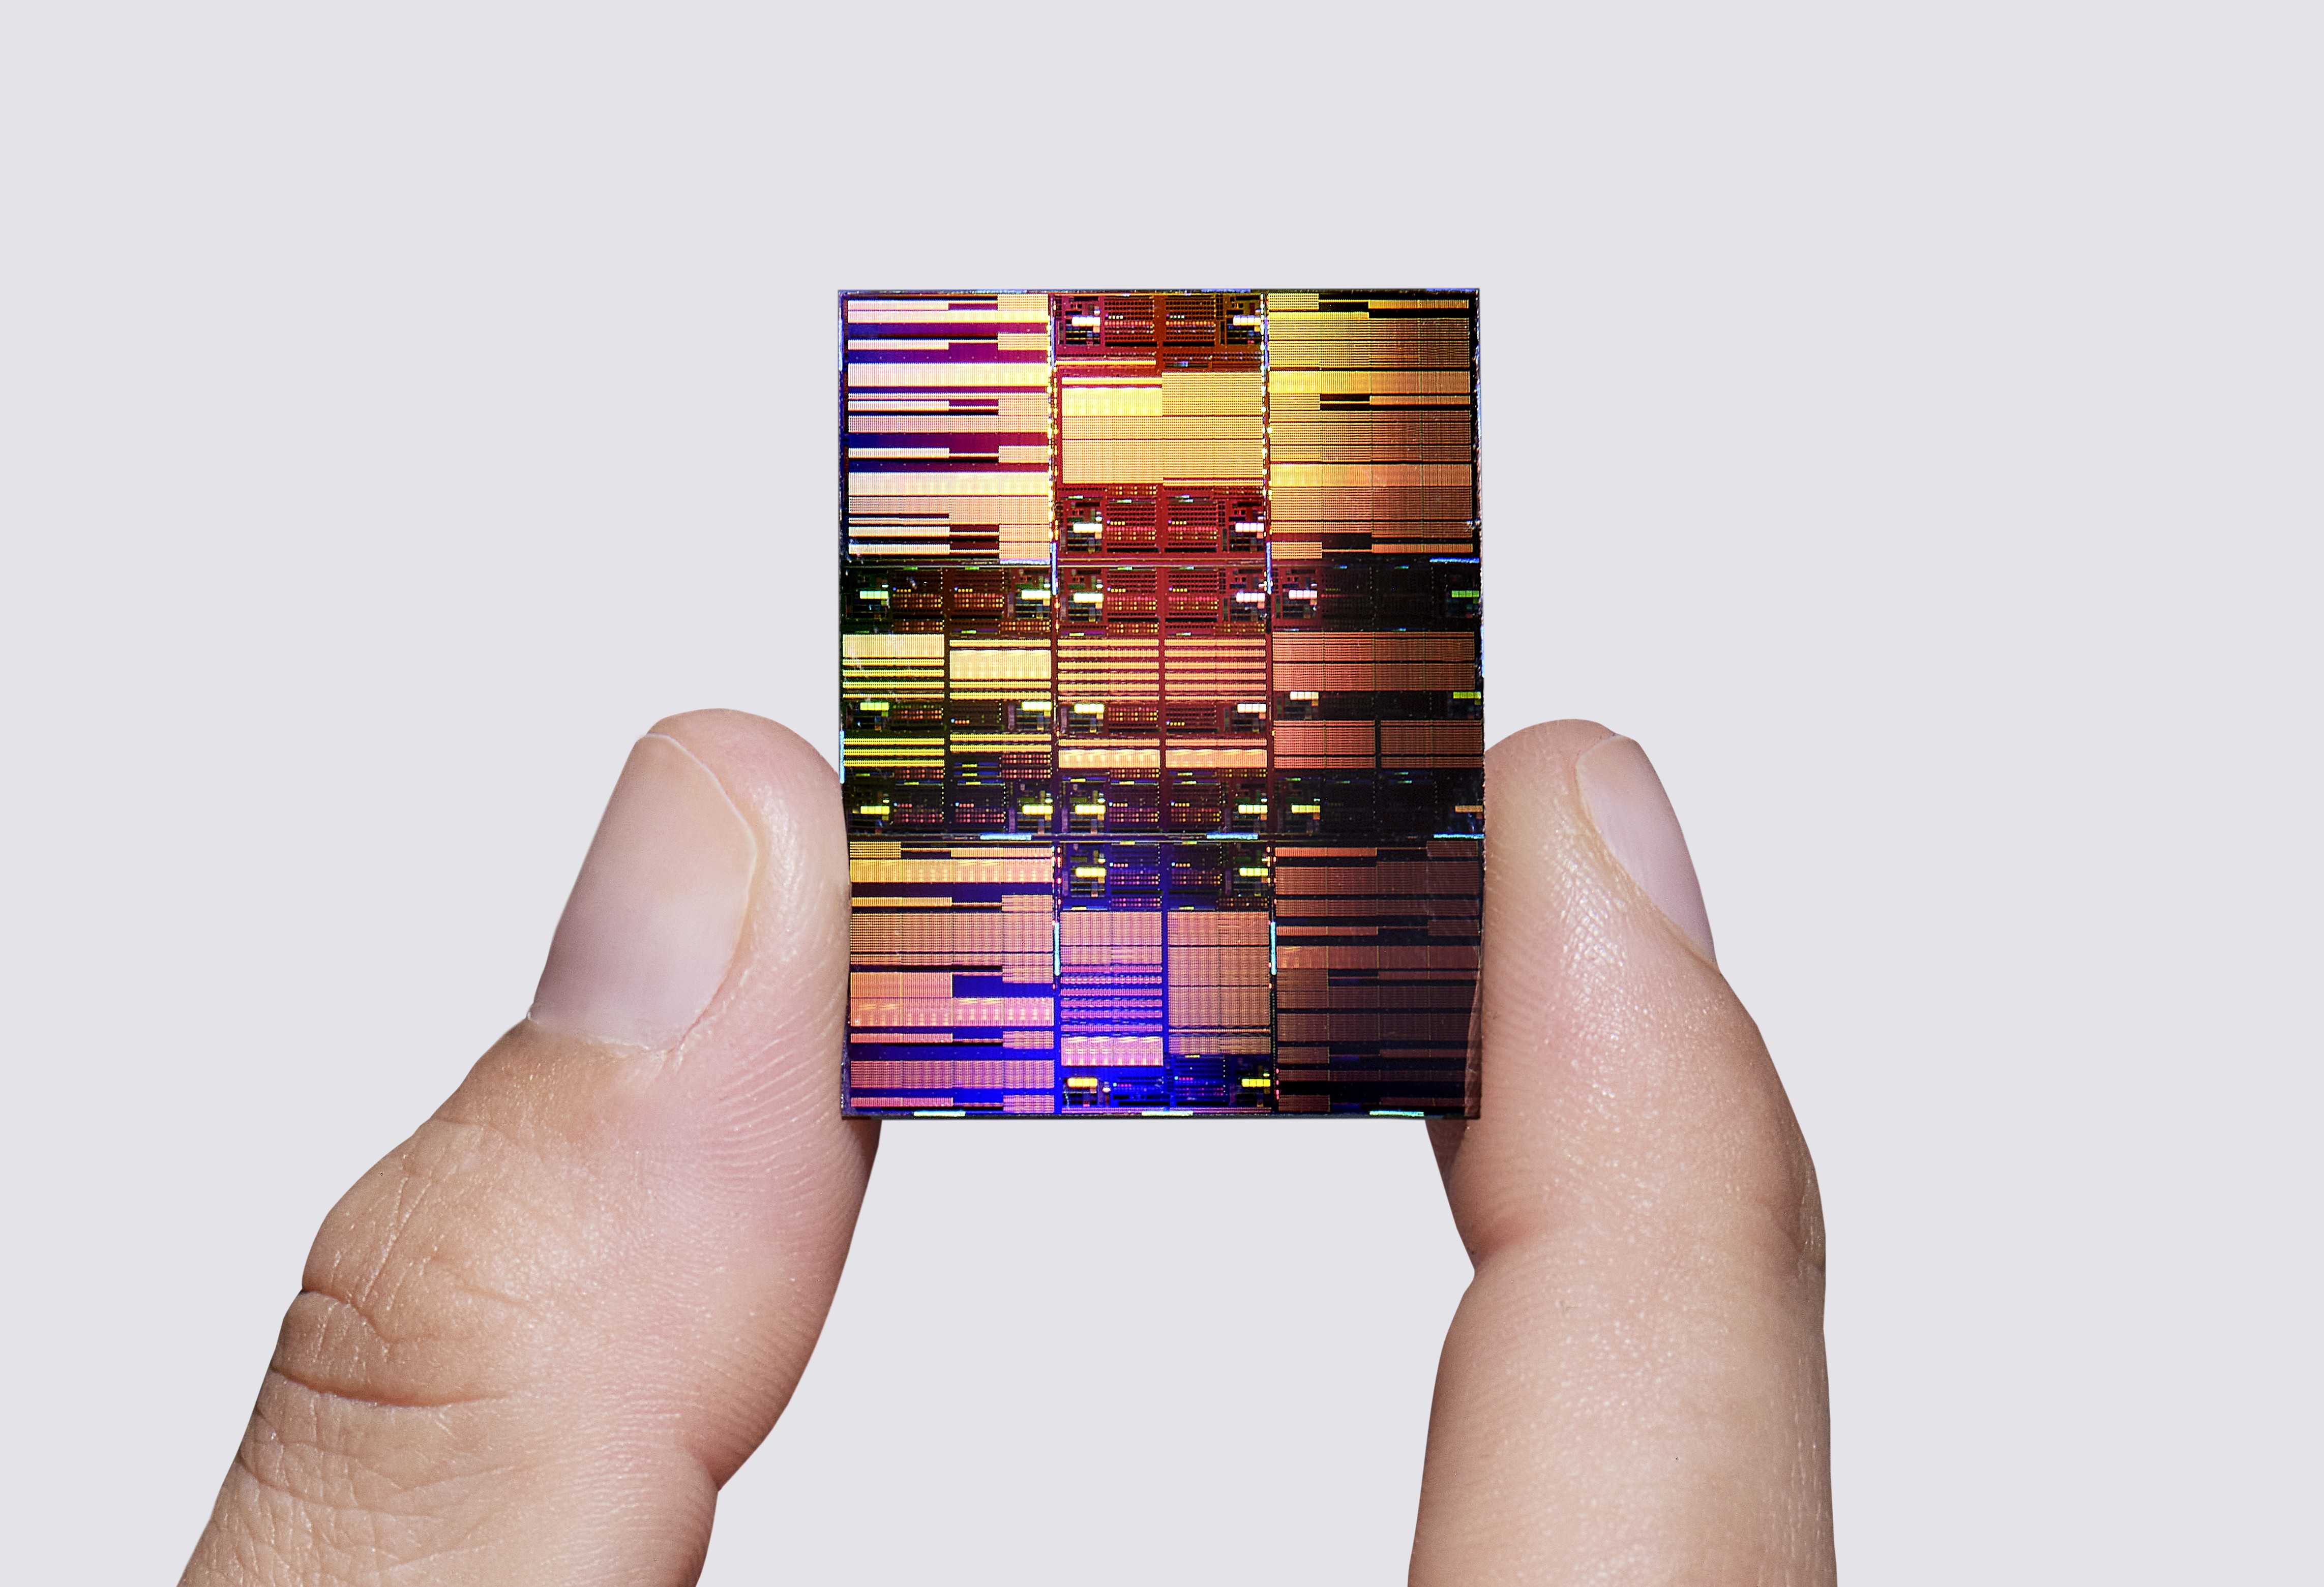
IBM’s research team sidestepped these thermodynamic dead-ends by pioneering radically novel material science approaches and proprietary vertical transport gate-all-around (VTFET) architectures. By routing electrical current vertically up and down through individual transistors rather than flowing horizontally across the silicon wafer, IBM engineers managed to bypass traditional routing bottlenecks. At the 0.7-nanometer mark—equivalent to just a few rows of silicon atoms—the material constraints are immense. Yet, initial stress-tests confirm that electron mobility remains remarkably stable, allowing for a density scaling factor that packs tens of billions more active switches onto a thumbnail-sized die.
"What we are witnessing is the re-engineering of the atomic foundation of modern compute," notes a senior semiconductor equity analyst based in lower Manhattan. "When you achieve a 50% performance uplift at sub-1 nanometer without triggering thermal runaway, you completely rewrite the unit economics of enterprise cloud infrastructure. The total cost of ownership for hyper-scale AI training clusters drops precipitously."
Market Liquidity, Enterprise ROI, and Valuation Multiples
The financial implications of IBM’s disclosure reverberate far beyond research laboratories. In contemporary equity markets, enterprise valuation multiples for cloud providers and semiconductor equipment manufacturers are inextricably tied to compute efficiency. As artificial intelligence models demand unprecedented volumes of processing power, power-grid constraints and cooling expenses have emerged as the primary operational bottlenecks for enterprise data center expansion.
By delivering a 50% efficiency gain at the 0.7nm threshold, enterprise buyers face a vastly accelerated depreciation cycle for existing hardware inventories. CIOs allocating budgets for next-generation data center architecture must now factor sub-1nm roadmaps into their risk mitigation frameworks. Companies that fail to transition to ultra-dense, low-power nodes risk structural margin compression as energy costs mount.
Simultaneously, the capital expenditure (capex) required to tool up commercial fabs capable of handling sub-1nm extreme ultraviolet (EUV) lithography will test the balance sheets of even the most liquid industry heavyweights. Venture capital and private equity syndicates are already pivoting investment theses toward specialized equipment suppliers, advanced packaging innovators, and proprietary EDA (Electronic Design Automation) software providers capable of modeling sub-atomic quantum interactions.
Verified Data & Metrics Breakdown
To contextualize the magnitude of IBM’s 0.7nm engineering feat, industry benchmarks and architectural parameters are contrasted below against previous generation nodes:
| Semiconductor Node | Approximate Gate Size | Relative Performance Gain | Primary Architectural Innovation |
|---|---|---|---|
| 5 Nanometer (5nm) | 50 Angstroms | Baseline Reference | FinFET mainstream adoption |
| 2 Nanometer (2nm) | 20 Angstroms | ~30% over 5nm | Gate-All-Around (GAA) nanosheets |
| 0.7 Nanometer (0.7nm) [NEW] | 7 Angstroms | 50% over baseline 2nm | Advanced VTFET & Atomic Material Stacking |
Industry & Market Implications: Winners and Loses
As financial markets digest the operational reality of sub-1nm silicon, a clear divergence is emerging between strategic winners and vulnerable incumbents. Enterprise software firms specializing in high-performance computing (HPC) and localized generative AI inferencing stand to capture immense windfall profits. Their software suites, optimized for dense multi-core environments, will run with unprecedented velocity.
Conversely, legacy infrastructure hardware providers reliant on older, thermally inefficient process nodes face accelerated margin decay. Furthermore, global foundries that delay capital commitments toward High-NA EUV infrastructure risk finding themselves locked out of the lucrative tier-1 enterprise supply chain. Regulatory compliance agencies, meanwhile, are monitoring these developments with heightened scrutiny, recognizing that control over sub-1nm fabrication lines represents the ultimate sovereign choke point of the twenty-first century.
Frequently Asked Questions (People Also Ask)
What exactly does a 0.7-nanometer (7-angstrom) chip architecture mean?
It refers to the physical dimensions of the transistor components on the silicon die. At 0.7 nanometers (7 angstroms), the scale approaches the width of individual silicon atoms, enabling an unprecedented density of switches that drastically increases processing power while conserving electrical energy.
How does this impact enterprise cloud compute infrastructure and ROI?
The 50% performance-per-watt improvement directly addresses data center power constraints and cooling costs. For enterprise buyers, this translates to faster model training times, lower electricity expenditures, and superior long-term return on investment (ROI) on hardware deployments.
When will sub-1 nanometer chips become commercially available for production?
While IBM has successfully unveiled and tested prototype designs at the 0.7nm node, commercial foundry scale-up requires extensive tooling, High-NA EUV equipment integration, and yield optimization. Industry consensus projects commercial pilot manufacturing reaching enterprise markets toward the end of the decade.
Why is the sub-1nm threshold considered a milestone for Moore’s Law?
For decades, physicists warned that quantum tunneling—where electrons leak uncontrollably through barriers—would halt transistor miniaturization well before reaching the sub-1nm mark. IBM's breakthrough proves that novel architectural designs and material sciences can successfully bypass these physical limits, extending the trajectory of Moore’s Law.
Future Outlook and Key Milestones to Watch
The transition from laboratory prototype to commercial foundry reality will be the defining narrative of the semiconductor sector over the next thirty-six months. Institutional investors and technology strategists must closely monitor three critical milestones:
- Equipment Lead Times: Delivery schedules for High-NA EUV lithography systems required to pattern sub-1nm structures.
- Yield Optimization Metrics: Early defect-density reports from pilot fabrication lines to verify commercial economic viability.
- Hyperscaler Adoption Announcements: Strategic partnerships between IBM, major cloud providers, and fabless designers committing enterprise workloads to the 0.7nm platform.
As the geopolitical and financial chess pieces align around the 7-angstrom frontier, one reality is indisputable: the rules of global competition are being rewritten at the atomic level. Those equipped to navigate this seismic shift will dictate the contours of the global digital economy for generations to come.