Executive Takeaways:
- Supermajor oil conglomerates have posted staggering consecutive quarters of cash flow generation, defying broader global macroeconomic deceleration.
- Aggressive capital allocation strategies have shifted away from high-risk exploration toward high-return brownfield optimization, share buybacks, and dividend optimization.
- Enterprise ROI and valuation multiples remain insulated due to tight global market liquidity, geopolitical supply shocks, and disciplined capital expenditure frameworks.
- Institutional investors and regulatory compliance bodies face mounting scrutiny over environmental mandates versus immediate shareholder return demands.
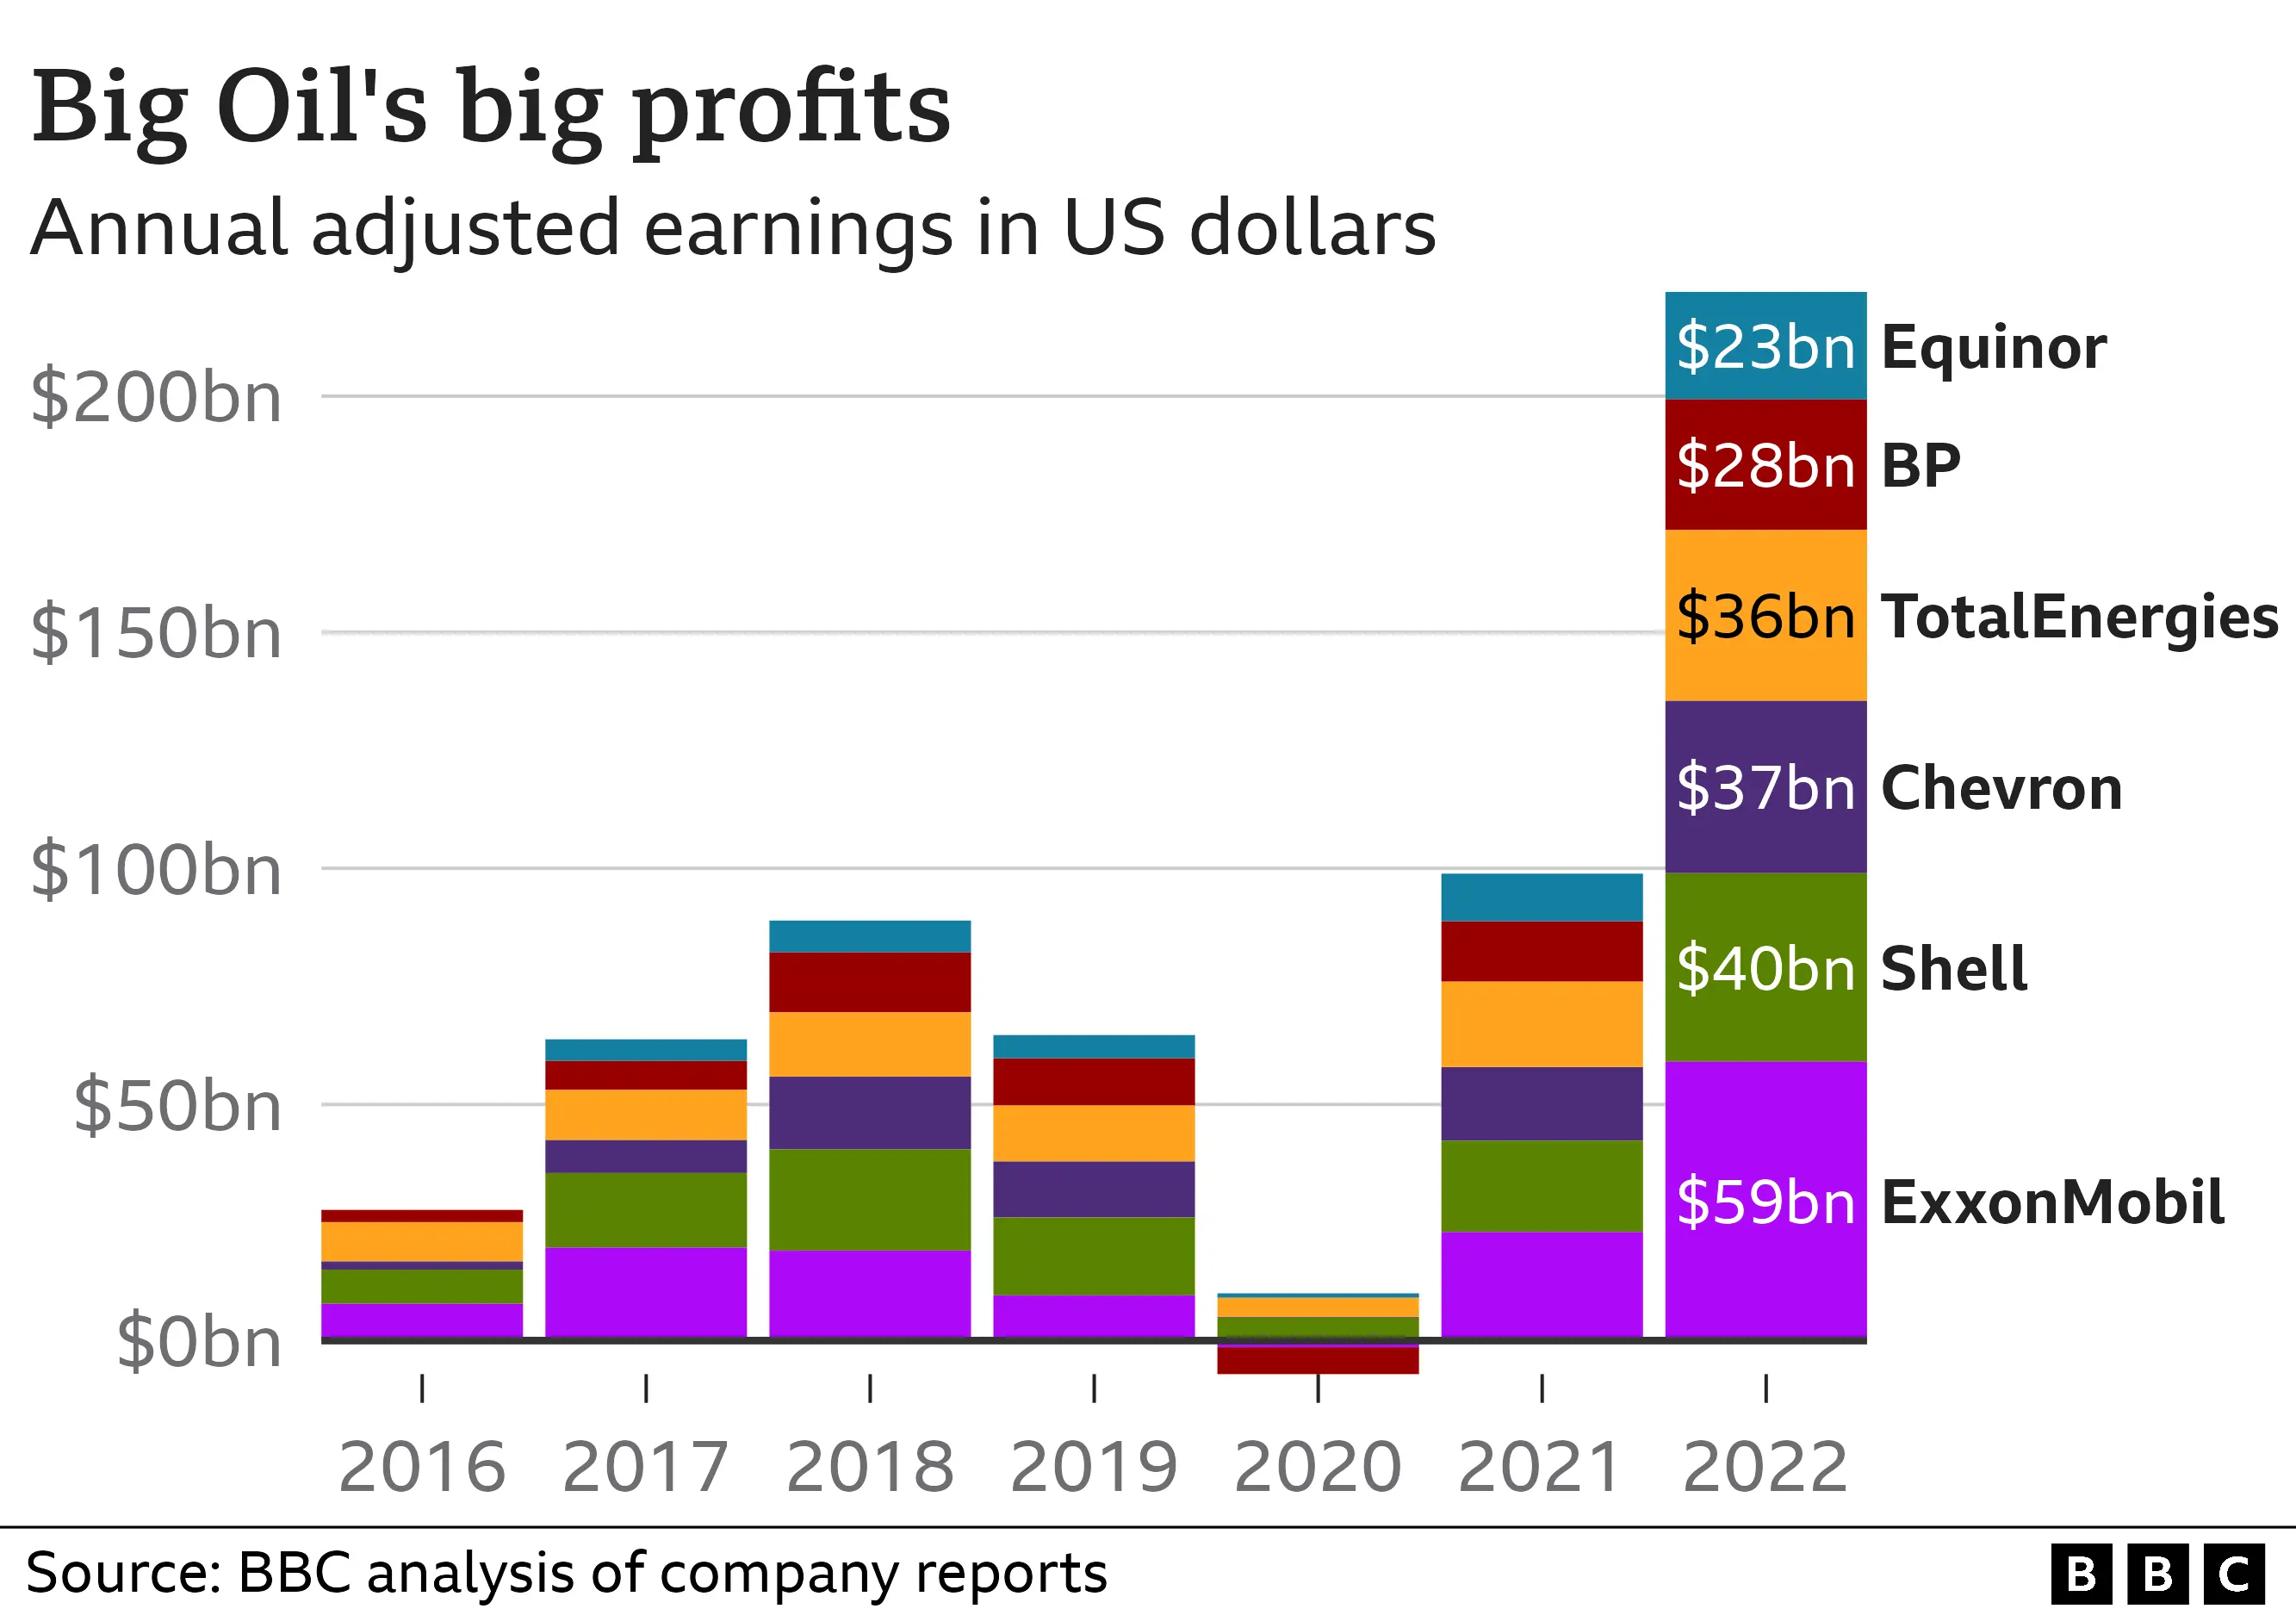
LONDON, NEW YORK, HOUSTON — In corporate boardrooms across Houston, London, and Paris, the champagne corks are once again popping to the sound of historic cash registers. Global energy giants have reported another staggering wave of multi-billion-dollar quarterly profits, reigniting fierce political debates, testing investor relations, and forcing a radical rethinking of enterprise valuation multiples in the commodities sector. As inflation recalibrates industrial supply chains and central banks navigate fragile economic growth, the world’s premier hydrocarbon producers are demonstrating an unprecedented ability to monetize high commodity price floors.
This latest surge in profitability is not merely a byproduct of random market volatility. It represents the culmination of a multi-year structural pivot toward uncompromising financial discipline, operational streamlining, and ruthless risk mitigation. For institutional investors navigating a complex macroeconomic landscape, understanding the mechanics behind these surging earnings requires peeling back the layers of balance sheet restructuring, cloud compute architecture integration in field operations, and shifting geopolitical risk premiums.
The Catalytic Engine: Supply Discipline Meets Resilient Demand
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To comprehend how supermajors continue to print historic profits, one must examine the fundamental shift in executive strategy that occurred in the wake of the 2020 market crash. Historically, high oil prices triggered an immediate, aggressive capital expenditure (CapEx) super-cycle characterized by reckless drilling, speculative frontier exploration, and bloated operational overhead. Today, that playbook has been permanently discarded.
Instead, legacy producers have embraced a philosophy of capital discipline. Even as West Texas Intermediate (WTI) and Brent crude benchmarks hover at levels that historically would have incited a drilling frenzy, executive boards have kept capital spending tight. Infrastructure scalability is now achieved through high-efficiency brownfield development rather than expensive, long-lead greenfield projects. By optimizing existing asset bases, energy firms have successfully lowered their enterprise break-even thresholds—many operating profitably with Brent below $40 per barrel.
Simultaneously, global demand has proven remarkably inelastic. Despite aggressive monetary tightening by the U.S. Federal Reserve and the European Central Bank, international aviation, maritime transit, and petrochemical feedstock requirements have sustained robust baseline consumption. This demand resilience, paired with ongoing supply-side management by OPEC+ and structural underinvestment in global oil infrastructure over the past decade, has created a permanent structural deficit that bolsters commodity pricing power.
Corporate Strategy: Capital Allocation, Buybacks, and Shareholder Yield

With billions in free cash flow accumulating on corporate balance sheets, the primary battleground for executive leadership has shifted to capital allocation. Unlike past decades where cash was funneled into speculative ventures, modern energy firms are aggressively prioritizing direct shareholder returns.
Mega-cap producers have deployed billions into aggressive share repurchase programs, effectively shrinking their share counts and driving up earnings per share (EPS). Simultaneously, variable dividend frameworks have been institutionalized, offering institutional investors unprecedented dividend yields that vastly outperform traditional safe-haven assets and broader equity indices.
However, this capital return strategy is executed against a backdrop of complex regulatory compliance and energy transition mandates. CEOs find themselves walking a delicate tightrope: appeasing institutional shareholders demanding short-term yield while satisfying ESG (Environmental, Social, and Governance) rating agencies by allocating fractional capital budgets to lower-carbon initiatives, carbon capture utilization and storage (CCUS), and hydrogen infrastructure.
| Metric / Indicator | Current Period | Historical Baseline (Pre-2020 Avg) | Strategic Impact |
|---|---|---|---|
| Average Brent Crude Benchmark | $85 - $95 / bbl | $60 - $70 / bbl | Drives robust cash flow generation and margin expansion. |
| CapEx-to-Cash Flow Ratio | 35% - 45% | 70% - 90% | Reflects strict capital discipline and reduced greenfield exposure. |
| Shareholder Distribution Yield | 8% - 12% combined | 4% - 5% (dividends only) | Attracts institutional capital via buybacks and variable dividends. |
| Average Break-Even Price | $35 - $42 / bbl | $50 - $65 / bbl | Provides immense buffer against downward commodity price shocks. |
Technology, Digital Transformation, and Operational Efficiency
Behind the headline-grabbing financial figures lies a quiet technological revolution. Modern oil and gas extraction bears little resemblance to the wildcat drilling operations of the 20th century. Today’s supermajors function increasingly as advanced data-analytics and engineering enterprises.
The integration of high-performance cloud compute architecture, real-time IoT (Internet of Things) sensor grids across pipeline networks, and machine learning algorithms for seismic interpretation has dramatically compressed operational expenditures. Predictive maintenance models powered by artificial intelligence allow engineers to anticipate mechanical failures in offshore platforms weeks before they occur, drastically minimizing costly downtime.
Furthermore, automated drilling rigs and remote-controlled extraction units have optimized labor productivity and enhanced workplace safety. This technological leverage directly improves enterprise ROI, ensuring that even as labor and materials inflation impacts the broader industrial sector, upstream energy operators maintain fat operating margins.
Industry & Market Implications: Winners, Losers, and Macro Fallout
The macroeconomic ramifications of sustained high oil earnings ripple far beyond the balance sheets of energy conglomerates. The market dynamics create distinct classes of beneficiaries and casualties across the global economy.
- Winners: Upstream operators, oilfield service providers (such as Schlumberger and Halliburton) experiencing surging demand for equipment rentals, and institutional equity holders benefiting from outsized dividend payouts. Furthermore, resource-exporting sovereign states in the Middle East and Latin Arabia are accumulating immense sovereign wealth funds, funding massive domestic diversification projects.
- Losers: Energy-intensive manufacturing sectors, chemical processors, and freight transportation companies face persistent margin compression. These industries struggle to pass soaring fuel and feedstock costs down to end consumers without eroding sales volume.
- Geopolitical & Economic Fallout: Persistent high energy costs complicate the policy mandates of central banks attempting to stamp out stubborn inflation. Governments face intense populist pressure to enact windfall profit taxes, a policy move that energy executives warn could stifle vital long-term energy security investments and dislocate market liquidity.
Frequently Asked Questions (People Also Ask)
Why are oil company earnings rising so dramatically when global growth is slowing?
Oil company profitability is driven primarily by commodity pricing power, structural supply discipline, and significantly lowered break-even operational costs. Unlike previous cycles where high prices sparked reckless over-drilling, modern producers are prioritizing capital efficiency, share buybacks, and debt reduction. This restraint, combined with resilient global demand and geopolitical supply constraints, keeps cash flows exceptionally high regardless of broader macroeconomic deceleration.
How are energy firms allocating their record-breaking free cash flows?
Modern capital allocation strategies focus heavily on returning capital to shareholders through aggressive share buyback programs and enhanced dividend yields. Concurrently, firms are directing capital toward low-cost brownfield asset optimization, digital transformation initiatives, and fractional investments in low-carbon technologies like carbon capture and hydrogen to satisfy ESG compliance requirements.
What role does technology play in maintaining these high profit margins?
Digital transformation has fundamentally reshaped the upstream sector. The implementation of cloud-based data analytics, IoT sensor monitoring, predictive AI maintenance, and automated drilling systems has drastically reduced operational expenditures and minimized costly equipment downtime. This technological leverage allows companies to extract maximum value from existing reserves at lower cost per barrel.
Will government windfall taxes impact future oil company valuations?
The threat of windfall profit taxes remains a persistent regulatory risk for multinational energy firms. While such taxation can create near-term earnings friction and weigh on equity valuations, major producers often respond by shifting capital deployment toward jurisdictions with more favorable, predictable fiscal regimes. Analysts note that regulatory uncertainty is already factored into current valuation multiples.
Future Outlook: Strategic Milestones to Watch
As the industry navigates the coming fiscal quarters, market analysts and institutional investors will be monitoring several critical indicators to gauge the sustainability of these financial highs.
First, market participants must track capital expenditure guidance updates from major Permian Basin operators and OPEC+ production quota adjustments. Any premature loosening of discipline could destabilize the pricing floor. Second, the pace of technological adoption—specifically regarding carbon capture monetization and automated extraction scalability—will determine how effectively legacy energy firms future-proof their business models against long-term decarbonization trends.
Ultimately, the latest surge in oil earnings serves as a powerful reminder of the hydrocarbon sector's enduring financial resilience. By mastering capital discipline, technological efficiency, and shareholder-centric capital allocation, global energy giants have cemented their status as formidable cash-generating powerhouses in an increasingly uncertain global economy.