Executive Takeaways
- The Paradigm Shift: Originally formulated by financial planner William Bengen in 1994, the rigid 4% withdrawal rule assumes historical market correlations that are increasingly disconnected from modern economic realities.
- Structural Headwinds: Elevated inflation, lower prospective equity valuation multiples, and compressed bond yields drastically diminish the statistical probability of a portfolio surviving a 30-year retirement horizon.
- Capital Allocation Urgency: Wealth managers and institutional risk officers are advising a pivot toward dynamic withdrawal strategies, tax optimization, and alternative asset classes to ensure long-term risk mitigation.
For three decades, the "4% rule" has served as the sacred text of retirement planning. Conceived by financial advisor William Bengen in 1994 and later codified by the famous "Trinity Study," the heuristic posits that a retiree can withdraw 4% of their initial portfolio balance in year one, adjusting that dollar amount annually for inflation, with an extraordinarily high statistical certainty that the capital will last 30 years.
However, as global markets grapple with structural regime changes, the financial engineering underpinning the 4% rule is facing unprecedented stress tests. Behind closed doors at major wealth management firms, private banks, and institutional research desks, analysts are warning that the confluence of contemporary macroeconomic forces could render this golden rule obsolete for a new generation of retirees. Ensuring portfolio longevity now requires a granular evaluation of five distinct catalytic factors capable of derailing traditional retirement math.
1. Structural Inflation Volatility and Purchasing Power Erosion
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The 4% rule assumes a stable monetary environment where inflation oscillates within predictable historical bands. The post-pandemic economic landscape, however, has introduced a regime of structural inflation volatility. When consumer prices surge, the mechanics of the 4% rule dictate that the absolute dollar withdrawal must increase correspondingly to maintain purchasing power.
During periods of persistent, higher-than-average inflation—reminiscent of the 1970s stagflation era—portfolios experience a devastating phenomenon known as reverse dollar-cost averaging. Selling depreciated assets to fund mandatory withdrawals locks in permanent capital losses. If inflation hovers consistently above 3% to 4%, the real return required from the underlying asset allocation increases exponentially, accelerating the depletion of the principal balance long before the traditional 30-year horizon concludes.
2. Compressed Bond Yields and Fixed-Income Impairment
Traditional retirement portfolios rely on a balanced architecture—classically split between equities and fixed-income securities. The fixed-income allocation is engineered to act as a ballast, generating steady income and capital preservation during equity market drawdowns.
Following a decade of artificially suppressed interest rates and ongoing macroeconomic adjustments, the traditional role of the bond aggregate has been severely impaired. When sovereign and corporate debt yields fail to outpace inflation and tax burdens, the fixed-income portion of the portfolio ceases to generate real alpha. Instead of functioning as a growth engine or an effective risk hedge, cash and bond yields often act as a drag on enterprise ROI for the individual investor, forcing equities to carry an unsustainable burden of total portfolio returns.
3. Elevated Equity Valuations and Reduced Forward Return Multiples
Market liquidity and concentrated capital allocation into mega-cap technology equities have driven major indices to historic valuation multiples, such as elevated cyclically adjusted price-to-earnings (CAPE) ratios. Historical financial modeling confirms a robust, inverse correlation between starting market valuations and subsequent 10-to-30-year annualized returns.
When retirees enter their golden years during a period of peak market valuations, the probability of encountering an early-retirement bear market increases significantly. If a portfolio sustains a 20% to 30% drawdown in years one through five, combined with ongoing annual distributions, the mathematical damage—known as sequence-of-returns risk—becomes nearly insurmountable. The portfolio lacks the necessary runway to compound its way back to baseline solvency.
4. Extended Longevity and the Expanding Retirement Horizon
When William Bengen and the authors of the Trinity Study formulated their parameters, a 30-year retirement horizon was considered an ultra-conservative, worst-case scenario. Today, medical advancements, biotechnology breakthroughs, and healthier lifestyles mean that a 60-year-old retiree must frequently plan for a horizon spanning 35 to 40 years.
Extending the timeline by an additional decade fundamentally alters the stochastic probability models. A withdrawal rate designed to survive 360 months experiences an exponential jump in failure rates when forced to sustain distributions for 480 months. Compounding fees, healthcare expenditure inflation, and prolonged exposure to market volatility compound the risk profile of the aging investor.
5. Healthcare Cost Inflation Outpacing General CPI
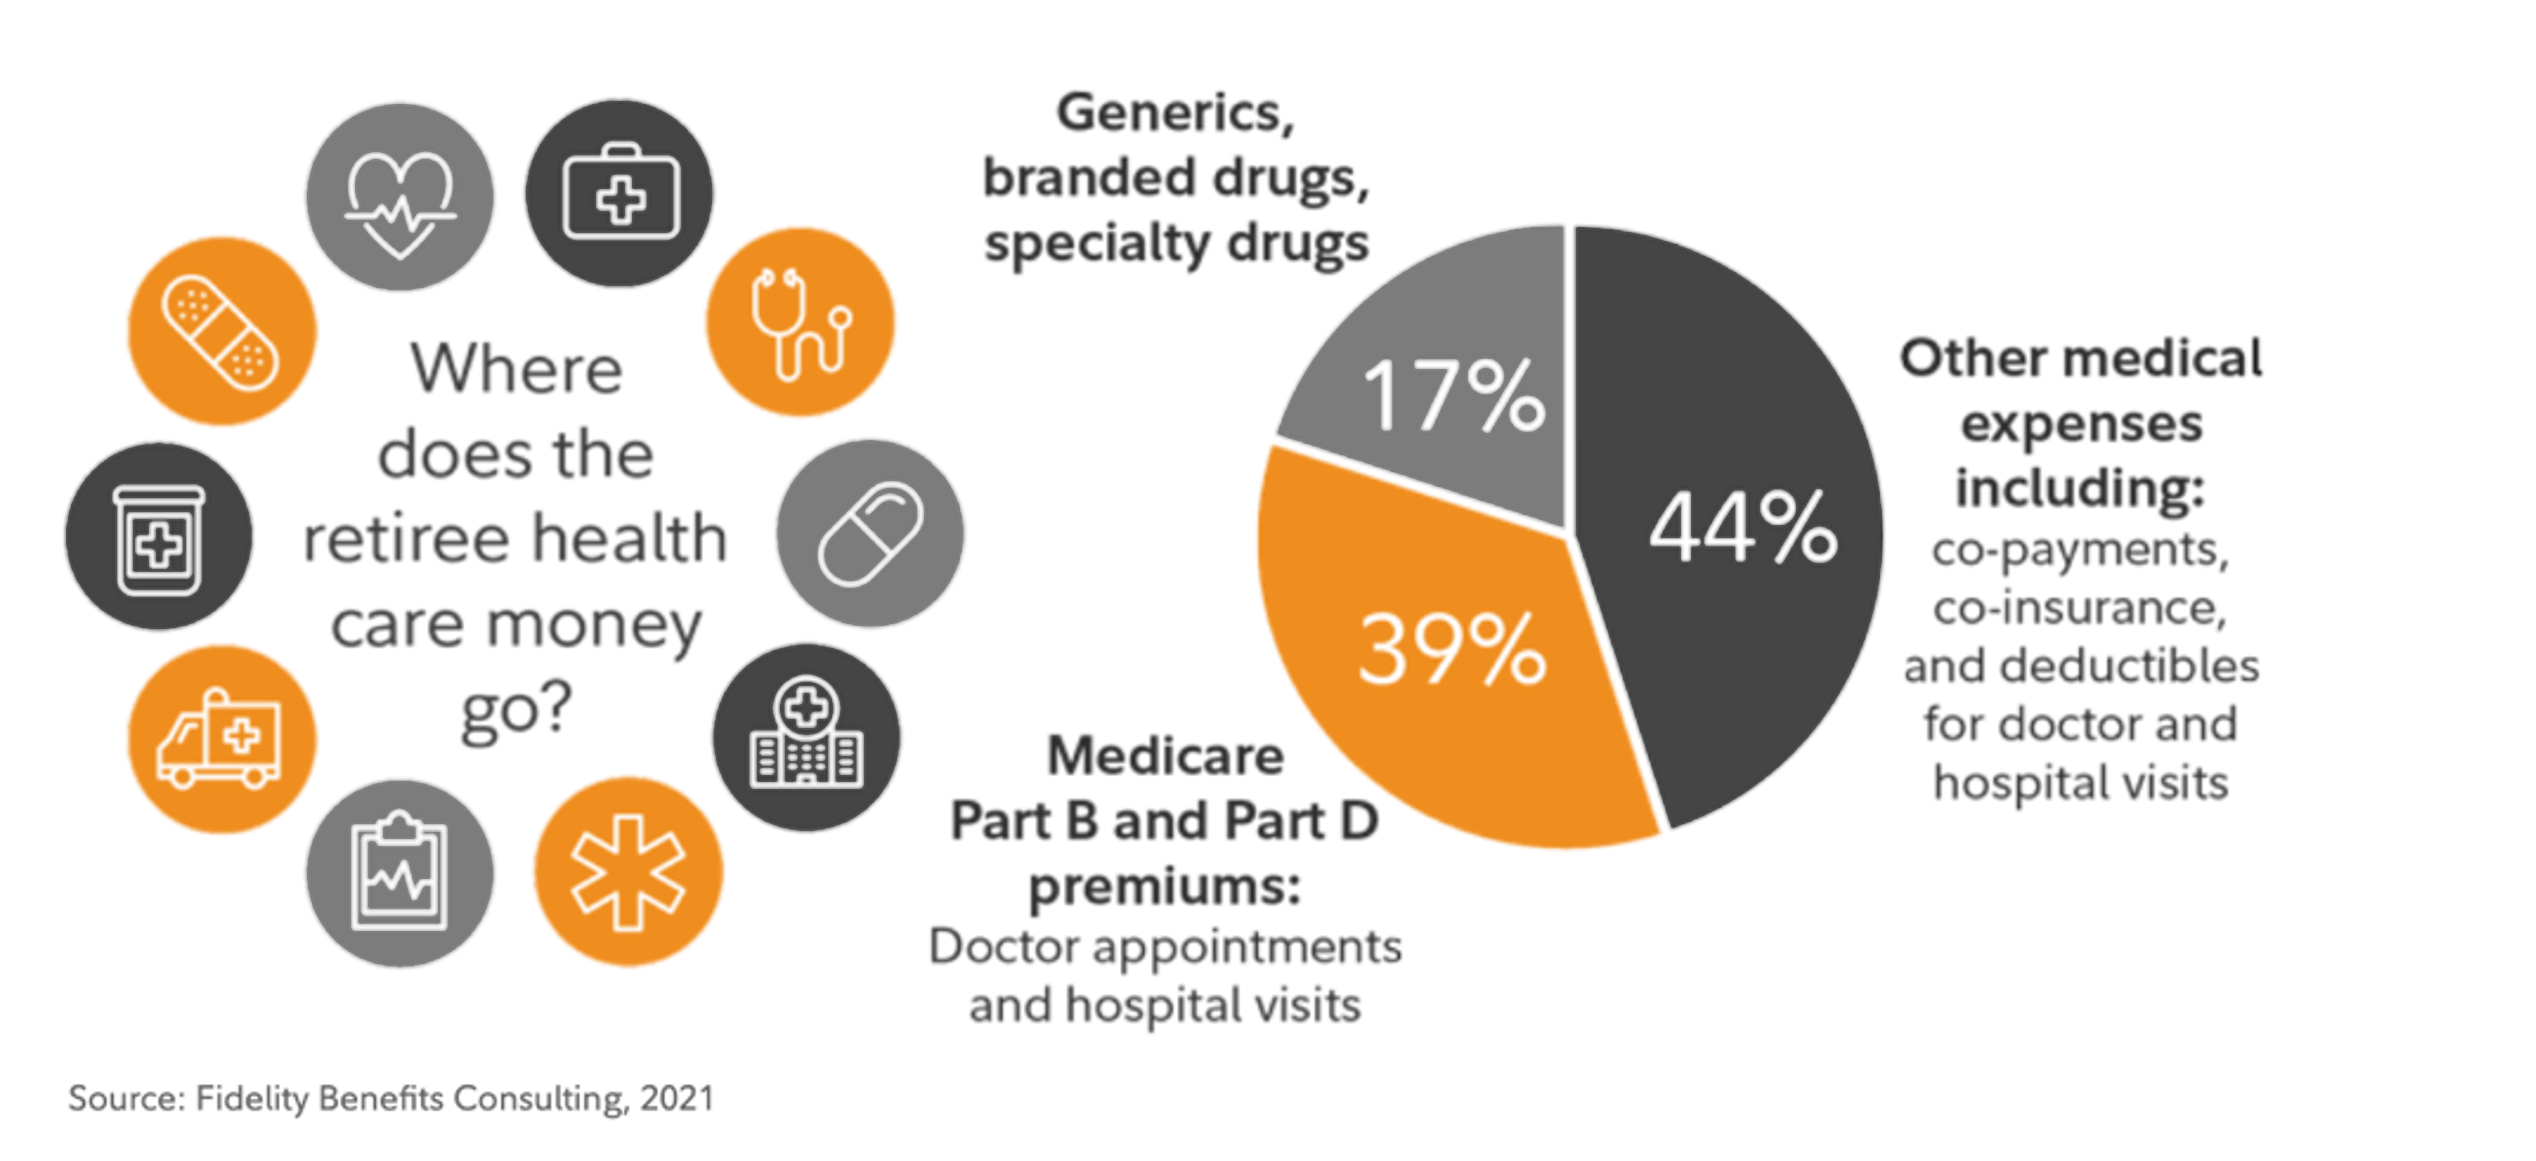
General Consumer Price Index (CPI) metrics fail to capture the hyper-inflationary reality of specialized consumer sectors, most notably healthcare and long-term elder care. Medical cost inflation consistently outpaces headline economic inflation by several percentage points annually.
As retirees age, their expenditure profile shifts away from discretionary goods toward non-negotiable medical services, pharmaceutical interventions, and potential assisted living infrastructure. Because these costs scale aggressively during the final third of retirement, they frequently punch unexpected holes in cash-flow projections, forcing emergency liquidations of tax-advantaged accounts outside of planned asset allocation schedules.
Verified Data and Macroeconomic Metric Comparison
To contextualize the systemic pressure on traditional retirement models, the following matrix compares baseline assumptions of the original 1990s framework against current financial market realities:
| Retirement Metric | Original 1990s Baseline | Current Market Reality (2024–2026) | Impact on Portfolio Survival |
|---|---|---|---|
| Initial Safe Withdrawal Rate | 4.0% to 4.5% | 3.0% to 3.5% (Conservative) | Requires higher asset accumulation to generate equivalent income. |
| Starting Bond Yield (10-Yr Treasury) | 6.0% to 8.0% | 3.8% to 4.5% | Significantly reduced fixed-income cash flow generation. |
| Average CAPE Ratio | 15x to 20x | 30x+ (Elevated historical levels) | Heightened exposure to sequence-of-returns risk. |
| Retirement Horizon Duration | 30 Years | 35 to 40 Years | Demands greater capital scalability and longevity risk mitigation. |
Industry & Market Implications
The erosion of the 4% rule has far-reaching ripple effects across the wealth management, insurance, and asset management sectors. Institutional players are aggressively recalibrating their product offerings to address the anxiety of mass-affluent clients.
Who Wins: Fee-only registered investment advisors (RIAs) specializing in dynamic, tax-gated withdrawal strategies are seeing a surge in demand. Furthermore, providers of structured annuities, registered index-linked annuities (RILAs), and pension-risk transfer solutions are capitalizing on the flight to guaranteed income streams. Alternative asset managers offering private credit and infrastructure funds are also capturing capital as investors search for yield outside public markets.
Who Loses: Passive, static "set-it-and-forget-it" target-date funds that rely strictly on a rigid 60/40 equity-to-bond split face intense criticism. Retail investors who fail to adapt their capital allocation strategies to dynamic withdrawal frameworks risk catastrophic depletion of their wealth in the event of concurrent equity and debt drawdowns.
Frequently Asked Questions (People Also Ask)
What is the alternative to the 4% rule if macroeconomic conditions remain volatile?
Financial planners increasingly recommend dynamic withdrawal strategies—such as the "guardrails" approach—where annual distributions are adjusted upward or downward based on portfolio performance rather than flat inflation adjustments. Other alternatives include the "Guyton-Klinger rules," which mandate spending cuts following market drawdowns and spending increases during robust market expansions.
How does sequence-of-returns risk destroy a retirement portfolio?
Sequence-of-returns risk refers to the danger of experiencing poor market returns or a severe bear market in the first five to ten years of retirement. Because the investor is actively selling assets to fund living expenses while the portfolio is down, they lock in permanent capital losses. Even if the market recovers later, the smaller principal base lacks the compounding capacity to sustain the original withdrawal schedule.
Can alternative assets completely replace traditional bonds in a modern retirement model?
While institutional portfolios routinely allocate capital to private equity, real estate, private credit, and infrastructure for inflation hedging and non-correlated returns, replicating traditional liquidity for individual retail retirees remains challenging. Alternative assets often feature lock-up periods, higher fee structures, and complex regulatory compliance hurdles, requiring careful risk mitigation before implementation.
Future Outlook and Key Milestones to Watch
As central banks navigate terminal interest rate policies and global sovereign debt levels continue to expand, the margin for error in retirement planning is shrinking. Financial engineers are moving away from static historical backtesting in favor of forward-looking stochastic modeling that accounts for fat-tail economic events.
Investors and wealth managers must monitor key structural milestones over the next 12 to 24 months, including central bank quantitative tightening trajectories, structural labor productivity shifts driven by cloud compute and artificial intelligence efficiencies, and fiscal policy adjustments regarding social insurance programs. Ultimately, navigating the post-4% era requires abandoning rigid rules of thumb in favor of agile, data-driven capital allocation frameworks capable of withstanding macroeconomic turbulence.