Executive Takeaways
- Macroeconomic Crosscurrents: Institutional capital allocators are aggressively reassessing valuation multiples as sticky inflation metrics collide with shifting Federal Reserve rate expectations.
- Faltering Mega-Cap Momentum: High-flying technology equities face a severe reality check over infrastructure scalability, enterprise ROI timelines, and slowing cloud compute architecture expansion.
- Earnings Season Bellwethers: Q3 corporate guidance will determine whether surging equity valuations are supported by genuine operational execution or inflated by speculative liquidity.
- Risk Mitigation Strategies: Portfolio managers are rapidly rotating capital into defensive asset classes and high-yield fixed income to protect against heightened market volatility.
As Wall Street enters a critical trading week in July 2026, institutional investors and asset managers find themselves at a perilous macroeconomic crossroads. Following an unprecedented multi-year bull run fueled largely by generative artificial intelligence exuberance and aggressive capital allocation into mega-cap technology names, the market is exhibiting classic symptoms of exhaustion. A pronounced tech wobble has sent shockwaves through major indices, forcing portfolio managers to reevaluate baseline assumptions regarding corporate earnings growth, market liquidity, and Federal Reserve monetary policy.
The convergence of slowing top-line revenue growth in core technology sectors and mixed macroeconomic indicators has dismantled the "buy-the-dip" mentality that dominated previous quarters. Investors are no longer willing to write blank checks for speculative infrastructure scalability without verifiable proof of enterprise return on investment (ROI). This investigative report examines the structural catalysts driving the current market sentiment shift, analyzes the incoming economic data points, and outlines the strategic implications for institutional portfolios navigating the remainder of 2026.
The Anatomy of the Tech Wobble: Valuation Multiples Meet Operational Reality
For the better part of three years, Wall Street's narrative was defined by relentless multiple expansion across the semiconductor, cloud computing, and enterprise software sectors. Driven by insatiable demand for advanced computing hardware and expansive cloud compute architecture, tech giants traded at historic price-to-earnings premiums. However, the calculus has fundamentally altered.
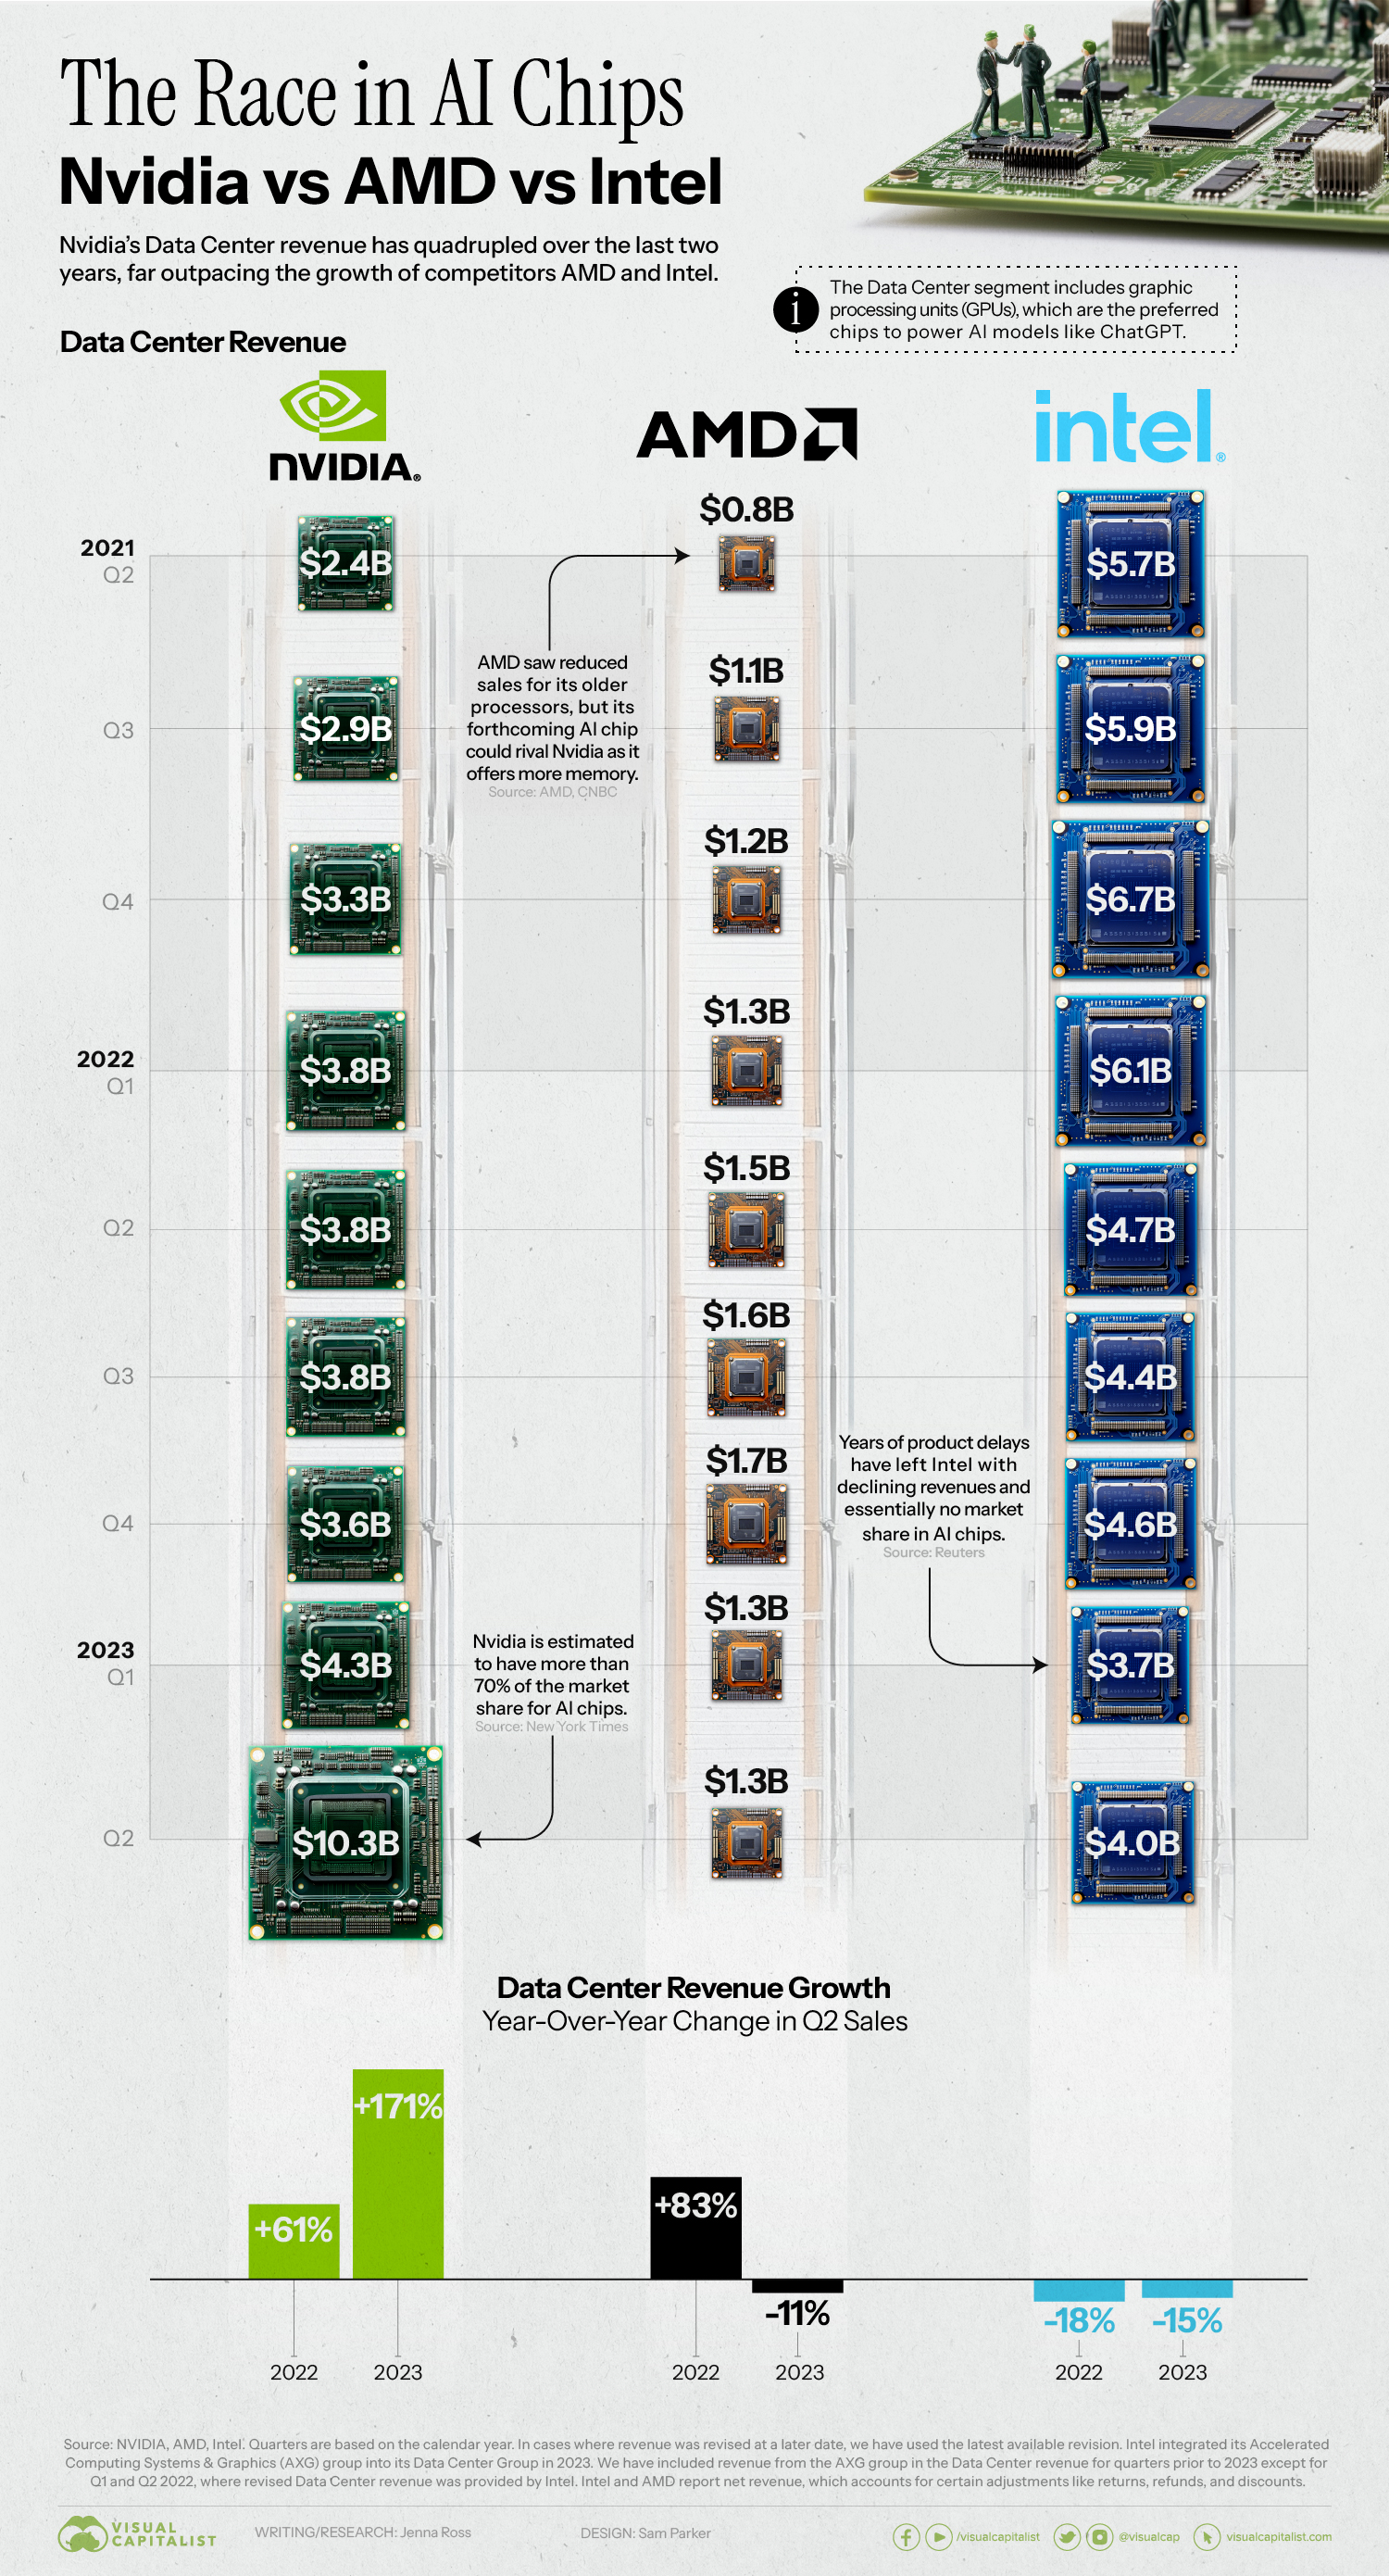
Recent market action reveals a growing skepticism among institutional desk traders regarding the monetization timeline of enterprise AI solutions. While capital expenditures on data centers and specialized silicon have reached astronomical levels, Chief Information Officers (CIOs) across Fortune 500 corporations are increasingly demanding rigorous regulatory compliance, proven cost savings, and tangible productivity metrics before deploying large-scale rollouts. This friction has created a bottleneck in revenue realization for hardware manufacturers and hyperscalers alike.
Furthermore, rising bond yields and persistent core inflation readings have increased the opportunity cost of holding high-duration growth assets. As discount rates tick upward, future earnings streams are subjected to harsher valuation models, triggering automatic de-risking protocols among quantitative hedge funds and systematic equity strategies. The era of unconditional capital availability for unprofitable or cash-burn-heavy tech ventures has officially drawn to a close.
Federal Reserve Policy Clues and the Interest Rate Impasse
Beyond sector-specific headwinds in technology, the broader macroeconomic trajectory remains dictated by the Federal Open Market Committee (FOMC). Wall Street participants are parsing every public utterance from central bank officials, searching for definitive clues regarding the timing and magnitude of future interest rate adjustments.
The central bank's delicate balancing act—suppressing lingering inflationary pressures without inadvertently tipping the labor market into a severe contraction—has kept market volatility elevated. Fixed-income desks are currently pricing in a prolonged plateau rather than an immediate easing cycle. This "higher-for-longer" reality fundamentally alters corporate borrowing costs and forces CFOs to overhaul their capital allocation frameworks.
- Debt Refinancing Pressures: Companies with upcoming corporate debt maturities face substantially higher coupon rates, pressuring net profit margins.
- Consumer Health Divergence: Retail spending data shows bifurcation, with high-income consumers sustaining luxury markets while middle- and lower-income cohorts pull back due to cumulative price increases.
- Liquidity Contraction: Quantitative tightening programs continue to drain system liquidity, making margin expansion a prerequisite for equity outperformance.
Verified Data & Metrics Breakdown
The following table provides a comprehensive quantitative snapshot of key macroeconomic indicators, equity index performance benchmarks, and valuation metrics driving Wall Street sentiment as of July 2026.
| Metric / Indicator | Current Reading (July 2026) | Historical Context / Prior Year | Market Impact & Significance |
|---|---|---|---|
| Fed Funds Target Rate | 5.25% - 5.50% (Plateau) | Same (Prolonged Pause) | Maintains tight credit conditions; limits multiple expansion for equities. |
| S&P 500 Forward P/E Ratio | 21.4x | 19.2x (Historical 10-Yr Avg: 17.8x) | Indicates elevated equity valuations, leaving little margin for earnings misses. |
| 10-Year U.S. Treasury Yield | 4.38% | 4.25% | Binds equity valuations and increases corporate debt servicing burdens. |
| Tech Sector Q3 Earnings Growth (Est.) | +8.5% YoY | +18.2% YoY (Previous Year) | Reflects normalisation of hyper-growth curves in mega-cap technology. |
Industry & Market Implications: Winners and Loses
Market corrections invariably redistribute wealth and market share. As growth-at-any-price strategies falter, distinct winners and losers are emerging across global capital markets.
The Winners: Quality, Cash Flow, and Defensive Positioning
Institutional portfolio managers are executing a decisive flight to quality. Corporations boasting pristine balance sheets, high free cash flow conversion rates, and reliable dividend growth are outperforming speculative growth plays. Energy majors, healthcare conglomerates, and defensive consumer staples are capturing inflows as allocators seek shelter from tech sector volatility. Furthermore, private credit and structured finance desks are thriving as traditional bank lending standards remain stringent.
The Losers: High-Multiple Growth and Speculative Tech
Conversely, unprofitable growth companies, highly leveraged startups, and semiconductor firms reliant on aggressive cyclical demand are experiencing severe valuation compression. Venture capital markets continue to face a protracted valuation reset, with late-stage private rounds frequently resulting in down-rounds or punitive liquidation preferences. Public equities lacking near-term profitability face intense selling pressure from institutional block traders.
Frequently Asked Questions (People Also Ask)
Why are investors currently concerned about the technology sector?
Investors are questioning whether the massive capital expenditures poured into artificial intelligence and cloud infrastructure will generate sufficient enterprise return on investment (ROI) in the near term. Combined with high valuation multiples and elevated interest rates, any sign of slowing revenue growth triggers sharp sell-offs.
How does Federal Reserve monetary policy impact stock market valuations?
The Federal Reserve influences valuations primarily through interest rates. Higher interest rates increase the discount rate applied to future corporate earnings, reducing the present value of high-growth stocks. Additionally, higher borrowing costs compress corporate profit margins and increase the attractiveness of fixed-income alternatives like Treasury bonds.
What should individual investors look for during upcoming earnings seasons?
Investors should scrutinize forward-looking management guidance, operational margin stability, and explicit evidence of cost efficiencies. Companies that can demonstrate robust organic revenue growth without relying on aggressive debt financing or unsustainable cost-cutting are best positioned to withstand market turbulence.
Are we entering a structural bear market or a routine market correction?
Most institutional strategists categorize current market movements as a healthy valuation reset and sector rotation rather than the onset of a structural bear market. Economic fundamentals remain resilient, but asset prices are adjusting to a higher-interest-rate paradigm and normalized corporate growth rates.
Future Outlook and Key Milestones to Watch
Looking ahead, Wall Street's trajectory will be dictated by three primary catalysts. First, incoming employment and consumer price index (CPI) releases will determine whether the Federal Reserve gains the latitude to initiate rate cuts in the latter half of the year. Second, upcoming corporate earnings reports will provide the ultimate litmus test for whether enterprise technology adoption can sustain elevated equity valuations.
Finally, geopolitical developments and global supply chain dynamics will continue to influence commodity prices and corporate input costs. For institutional asset managers, risk mitigation, disciplined asset allocation, and a rigorous focus on fundamental balance sheet strength will remain the defining hallmarks of successful portfolio management through the remainder of 2026.