Executive Takeaways
- A Structural Shift in Market Plumbing: The U.S. Department of the Treasury’s revived bond buyback operations—analyzed rigorously in groundbreaking research by Rebecca Patterson for the Council on Foreign Relations (CFR)—mark the first systematic intervention in sovereign debt markets since 2000, signaling systemic anxiety over dealer balance sheet capacity.
- Bifurcated Operations Target Distinct Pressures: The program deploys a twin-track strategy: "liquidity support" operations designed to absorb illiquid, "off-the-run" debt, alongside "cash management" buybacks engineered to smooth out tax-receipt volatility and optimize T-bill issuance schedules.
- Regulatory Friction Meets Fiscal Reality: Decades of post-Global Financial Crisis bank regulations, specifically the Supplementary Leverage Ratio (SLR), have crippled primary dealers' willingness to warehouse Treasuries just as annual federal issuance approaches record multi-trillion-dollar run rates.
- Monetary and Fiscal Cross-Currents: While Treasury officials adamantly distinguish buybacks from Federal Reserve Quantitative Easing (QE), the aggressive repurchase of deeply discounted paper operates as a de facto backstop for leveraged basis traders and institutional asset allocators navigating historic duration risk.
The Anatomy of a Quiet Revolution at the Treasury
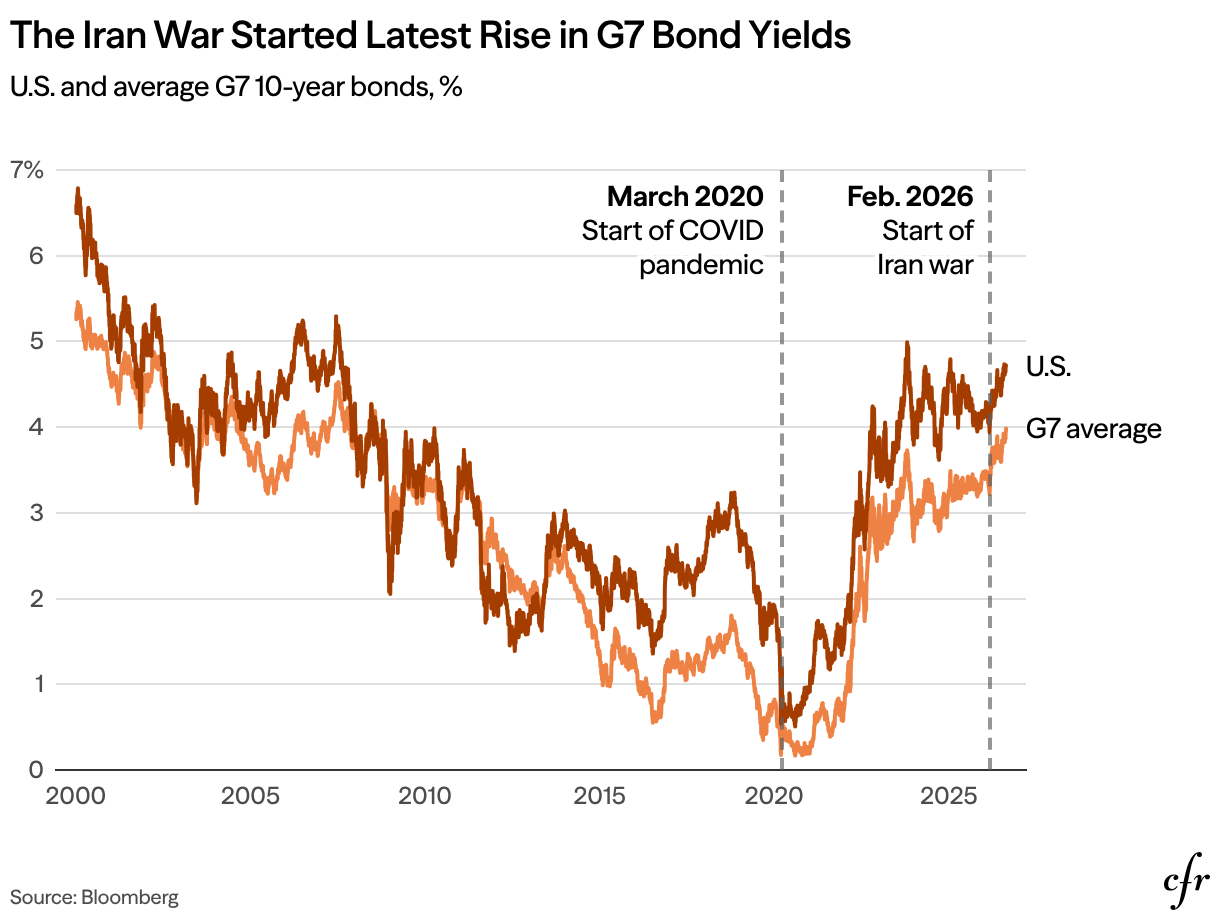
In the vaulted trading rooms of Lower Manhattan and the credit desks of Mayfair, market veterans have long viewed the U.S. Department of the Treasury as a pure debt issuer—an indifferent machine auctioning off trillions of dollars in paper to fund Washington's fiscal expansion. Yet, a quiet transformation has fundamentally altered that relationship. As documented in a landmark analysis by former Bridgewater Chief Investment Strategist and Council on Foreign Relations Senior Fellow Rebecca Patterson, the Treasury has evolved from a passive auctioneer into an active, discerning portfolio operator inside its own secondary market.
The Treasury's re-entry into debt repurchases represents the most consequential structural evolution in sovereign debt architecture in a quarter of a century. Unlike the Clinton-era buybacks of 2000–2002—which retired debt fueled by rare federal budget surpluses—the modern framework operates under the shadow of persistent trillion-dollar fiscal deficits, climbing interest costs, and an expanding national debt pile exceeding $35 trillion. The catalyst is not excess cash, but market plumbing: an urgent imperative to inject resilience into the foundational collateral of global capitalism.
To grasp why this intervention surprised institutional allocators, one must inspect the fracture lines within the Treasury market itself. The headline liquidity of U.S. sovereign debt is overwhelmingly concentrated in "on-the-run" issues—the most recently minted benchmarks. However, the sprawling ocean of "off-the-run" securities—older notes and bonds that make up the vast majority of outstanding nominal debt—routinely suffers from chronic trading friction, wide bid-ask spreads, and frozen dealer intermediation. By stepping into this void as a reliable counterparty, the Treasury is attempting to resolve an issue that has haunted market participants since the catastrophic repo squeeze of September 2019 and the pandemic flash crash of March 2020.
Liquidity Support vs. Cash Management: Deconstructing the Mechanics
The Treasury’s operational architecture divides buybacks into two distinct operational sleeves, each designed to resolve a specific institutional vulnerability:
1. Liquidity Support Operations
Conducted on a regular, predictable monthly calendar, these operations target older, illiquid off-the-run nominal coupons and Treasury Inflation-Protected Securities (TIPS). The Treasury issues small, transparent invitations to primary dealers to sell back seasoned issues that carry limited market turnover. By absorbing these sticky positions and simultaneously reissuing larger, benchmark-sized on-the-run tranches, debt managers systematically upgrade the aggregate liquidity profile of the sovereign debt stock. This process reduces the structural yield premium investors demand to hold older debt, lowering long-term borrowing costs for taxpayers.
2. Cash Management Operations
Historically, the Treasury Cash Account (TCA) held at the Federal Reserve swings wildly between quarterly corporate tax deadlines and massive entitlement disbursement dates. To prevent disruptive spikes and cliffs in Treasury bill (T-bill) supply, the debt office now utilizes cash-management buybacks. When tax inflows swell cash balances, the Treasury buys back near-term bills and short-dated coupons, mitigating the need to abruptly cut auction sizes. Conversely, it avoids saturating money markets when cash runs thin. This dynamic creates an indispensable cash-absorption mechanism for global institutions managing enterprise treasury liquidity.
| Strategic Feature | Modern Liquidity Support (Current Era) | Modern Cash Management | Historical Buybacks (2000–2002) | Federal Reserve QE Operations |
|---|---|---|---|---|
| Primary Objective | Reduce friction in off-the-run bonds; free dealer balance sheets | Smooth cash balances & insulate bill issuance from tax volatility | Retire debt using federal budget surpluses | Inject monetary stimulus & ease broader financial conditions |
| Target Securities | Seasoned, off-the-run nominal coupons & TIPS (1 to 30 years) | Securities maturing within weeks or months; Treasury bills | Long-duration high-coupon bonds (10 to 30 years) | Full maturity spectrum across Treasuries and Agency MBS |
| Funding Source | Increased on-the-run debt issuance (duration/issuance neutral) | Excess Treasury cash balance buffer (TCA) | Federal fiscal budget surpluses | Central bank reserve creation (unsterilized) |
| Market Impact | Narrows off-the-run vs. on-the-run yield spreads; mitigates tail risk | Stabilizes front-end repo rates and SOFR benchmarks | Flattened long end of the yield curve dramatically | Expands broad money supply; depresses aggregate term premium |
The Dealer Constraint: Why Wall Street Needed a Lifeline
At the center of Rebecca Patterson’s CFR thesis is an unvarnished reality: Wall Street’s primary dealers—the foundational intermediaries mandated to make markets in U.S. debt—are structurally incapacitated. Following the 2008 financial crisis, global regulators imposed stringent risk-weighted capital frameworks, headlined by the Basel III Supplementary Leverage Ratio (SLR). The SLR treats low-risk Treasury bonds identically to risky corporate assets when calculating minimum leverage constraints, strictly limiting how many Treasuries a Tier-1 bank can warehouse relative to its equity capital.
In 2007, the total outstanding marketable U.S. Treasury debt sat around $4.5 trillion, and primary dealer balance sheets were sufficiently capitalized to intermediate trading volume. Today, the marketable debt stock exceeds $27 trillion, but primary dealer balance-sheet capacity has remained virtually stagnant. This creates an exponential mismatch: an ocean of newly minted federal debt pouring into an intermediation funnel whose pipes have not expanded in fifteen years.
When market volatility surges, primary dealers routinely withdraw from off-the-run market making to preserve regulatory capital ratios. Bid-ask spreads widen catastrophically, corporate treasuries face elevated liquidation costs, and systemic basis trades—where hedge funds exploit micro-pricing discrepancies between Treasury cash bonds and futures—face violent margin liquidations. The Treasury's willingness to step in as a non-economic buyer of off-the-run debt directly mitigates this inventory risk, taking balance-sheet drag off dealer ledgers and recycling vital regulatory capacity back into the primary auctions.
Who Wins, Who Loses, and What It Signals About the Yield Curve
The institutional ramifications of the Treasury’s active intervention reverberate across asset classes, creating distinct operational winners and capital allocation challenges:
- The Winners: Primary Dealers & Asset Managers. Bank balance sheets benefit immediately. Dealers offload illiquid, capital-intensive inventory to the Treasury at predictable spreads, allowing them to optimize their return on equity (ROE) and redeploy risk limits into higher-margin underwriting. Multi-asset fund managers gain continuous price discovery and exit optionality on seasoned bond holdings without suffering punitive market-impact costs.
- The Winners: Leveraged Basis Traders. Quantitative hedge funds running Treasury cash-futures basis strategies receive an implicit structural backstop. Knowing that off-the-run bonds possess a natural buyer of last resort lowers the probability of sudden, catastrophic widening in basis spreads, preserving the mechanics of leverage across alternative asset managers.
- The Losers: Traditional Volatility Arbitrage Desks. Proprietary trading desks that historically captured wide mispricings between off-the-run and on-the-run paper find their enterprise ROI compressed. As the Treasury steadily dampens pricing anomalies across the curve, arbitrage spreads tighten, erasing high-margin structural dislocation trades.
- The Systemic Question: The Fiscal Dominance Signal. By actively managing secondary market liquidity, the Treasury is performing functions historically associated with central bank open-market desks. While Treasury officials maintain that these operations are debt-issuance neutral and fundamentally detached from monetary policy, the initiative underscores how sovereign debt management is increasingly forced to engineer market stability in an era of relentless fiscal supply.
Frequently Asked Questions (People Also Ask)
Is the Treasury’s buyback program the same as Federal Reserve Quantitative Easing (QE)?
No. While both programs involve purchasing Treasury debt in the open market, their mechanics, objectives, and funding sources are fundamentally different. When the Federal Reserve conducts QE, it creates brand-new commercial bank reserves out of thin air, expanding the total money supply to lower overall financial conditions and suppress term premiums. In contrast, the Treasury cannot create money. When the Treasury buys back off-the-run debt, it funds the purchase by issuing an equivalent amount of new on-the-run Treasuries or drawing down cash reserves collected through tax receipts. The Treasury's operations are sterilized, duration-calibrated, and designed solely to improve liquidity plumbing, not to stimulate consumer inflation or expand money supply.
Why does the Treasury focus its buybacks on "off-the-run" debt?
"Off-the-run" Treasuries are older issues that have been superseded by newly auctioned benchmark bonds ("on-the-run"). Because the vast majority of trading, hedging, and derivatives activity clusters around the newest on-the-run issues, seasoned off-the-run bonds become illiquid. Institutional investors often demand a liquidity discount to hold them, which raises the government’s overall borrowing costs across the yield curve. By purchasing these older, discounted bonds back from primary dealers, the Treasury eliminates structural inventory bottlenecks, compresses yield premiums, and restores balance-sheet flexibility to market makers.
How does the Supplementary Leverage Ratio (SLR) impact Treasury liquidity?
The Supplementary Leverage Ratio is a post-crisis banking rule that requires global systemically important banks (G-SIBs) to hold a minimum percentage of Tier-1 capital against their total unweighted assets—including risk-free U.S. Treasuries and cash reserves. Because the rule ignores the credit safety of Treasuries, warehousing sovereign bonds consumes significant bank equity capital. As the national debt has grown past $27 trillion, dealer balance sheets have failed to grow in proportion, limiting their capacity to facilitate trades during market stress. The buyback program acts as an external release valve for this regulatory constraint.
What does the buyback operation tell us about future Treasury auction sizes?
The buybacks demonstrate that debt managers are intensely focused on avoiding "auction indigestion." By establishing a permanent mechanism to buy back older debt, the Treasury creates headroom to issue larger volumes of on-the-run benchmark notes and bills without blowing out dealer balance sheets. However, it also reveals that the sheer scale of future issuance will require permanent structural support, signaling that federal debt managers anticipate continuous market fragility as long as budget deficits require multi-trillion-dollar annual gross borrowing.
Future Outlook: Strategic Milestones to Monitor
The institutional maturation of the U.S. Treasury buyback framework marks a turning point in global finance. As debt managers, primary dealers, and foreign sovereign reserve managers adapt to this operational reality, three forward-looking catalysts will dictate market direction:
First, monitor the Treasury Borrowing Advisory Committee (TBAC) quarterly refunding statements. Any structural increase in the gross cap on monthly liquidity support operations will signal deeper underlying concerns regarding dealer absorption capacity. Second, watch the progress of regulatory reform, specifically potential recalibrations of the SLR by the Federal Reserve and Basel regulators; if banking regulations are relaxed to exempt Treasuries from leverage tests, the absolute burden on Treasury-led buybacks may diminish. Finally, observe the Treasury Cash Account behavior during upcoming debt-ceiling negotiations. As liquidity volatility tests market plumbing, the buyback engine will stand as the front line of defense between order and disarray in the world’s most critical financial market.