NEW YORK — Wall Street’s primary indices closed in negative territory on Friday, halting a weeks-long optimism rally after Federal Reserve Chair Kevin Warsh delivered a resolute, hawkish address signaling that the central bank’s war on sticky inflation is far from over. Speaking at an emergency macroeconomic symposium, Warsh made it unequivocally clear that disinflationary tailwinds have hit a structural plateau, reiterating the Federal Open Market Committee's (FOMC) unyielding commitment to the statutory 2% core Personal Consumption Expenditures (PCE) price index target. The benchmark S&P 500, the technology-heavy Nasdaq Composite, and the blue-chip Dow Jones Industrial Average all relinquished early-session gains as institutional investors rapidly recalibrated capital allocation strategies, compressed equity valuation multiples, and adjusted risk mitigation models to price in a higher-for-longer federal funds rate trajectory.
The market reaction underscores a profound tension rippling through global financial centers: the friction between an impatient Wall Street craving immediate monetary policy pivot accommodations and a resolute central banking apparatus committed to anchoring long-term inflation expectations. As corporate treasurers navigate tightening credit spreads, fluctuating enterprise ROI, and constrained market liquidity, the reappraisal of Federal Reserve leadership under Warsh has officially redefined macroeconomic risk parameters for the remainder of the fiscal year.
Executive Takeaways
- The Warsh Doctrine Confirmed: Federal Reserve Chair Kevin Warsh silenced market dovish pivots, stating categorically that core inflation is not decelerating fast enough to justify a premature monetary easing cycle.
- Broad Market Sell-Off: Wall Street major indices closed lower as institutional block trades and programmatic selling accelerated following the Fed chair's remarks, disproportionately impacting high-growth tech valuation multiples.
- Yield Curve Realignment: Treasury yields surged across the short-to-intermediate curve, signaling that sophisticated capital markets have fully priced in persistent macroeconomic restrictive conditions and elevated borrowing costs.
- Strategic Portfolio Rotation: Institutional asset managers are executing aggressive risk-off defensive rotations, prioritizing balance sheet resilience, robust enterprise cash flows, and superior capital efficiency over speculative growth.
Comprehensive Narrative: The Catalytic Shift in Monetary Governance
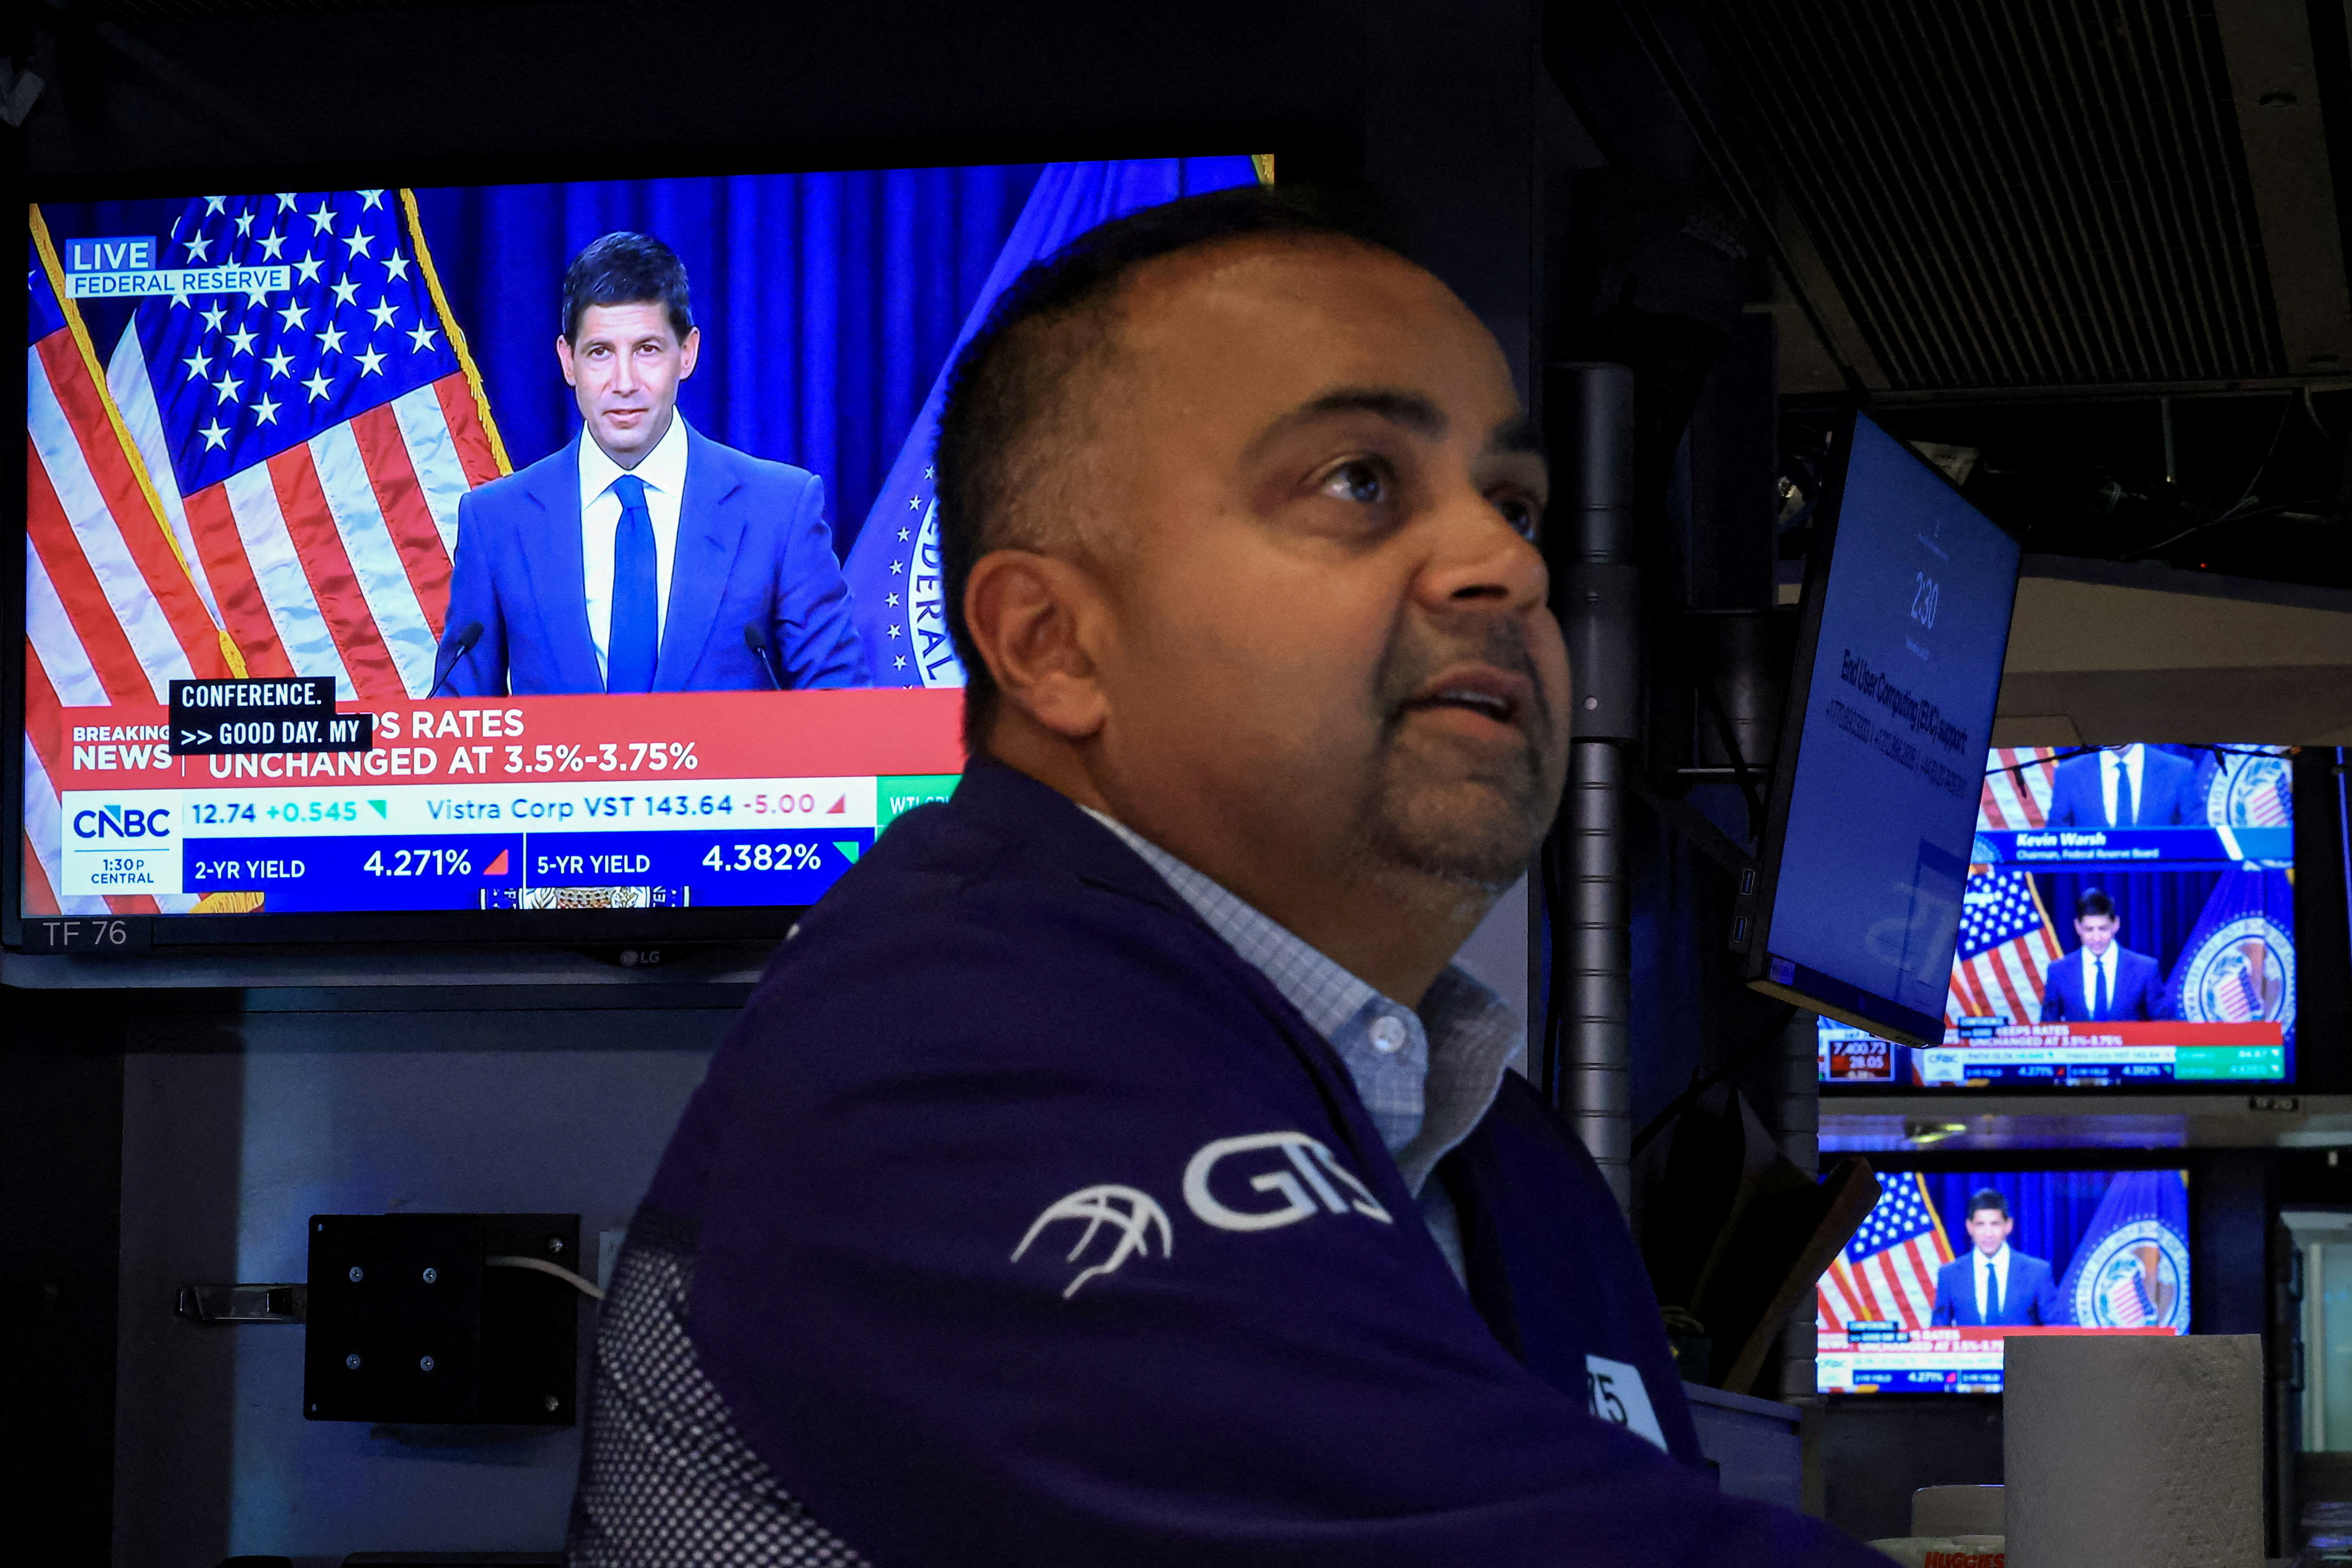
The macroeconomic landscape shifted dramatically on Friday as market participants digested the tone and substance of Federal Reserve Chair Kevin Warsh’s keynote address. For months, equity bulls had aggressively priced in an aggressive easing cycle, operating under the assumption that moderating headline consumer price index (CPI) prints would compel the central bank to slash interest rates to safeguard economic expansion. However, Warsh’s unequivocal defense of rigorous price stability shattered those consensus assumptions.
According to Federal Reserve data cited during the address, core services inflation—excluding volatile food and energy components—remains stubbornly elevated, driven by persistent wage pressures and resilient consumer expenditures. Warsh emphasized that premature monetary easing runs the severe historical risk of unanchoring inflation expectations, forcing an even more draconian tightening cycle down the road. "We cannot declare victory over inflation simply because the most acute supply-chain shocks have abated," Warsh remarked during the briefing. "Our statutory mandate demands absolute price stability, and our policy posture will remain unapologetically restrictive until the 2% target is irreversibly secured."
The market impact was immediate and systemic. Growth-oriented equities, particularly within the technology, semiconductor, and biotechnology sectors, experienced sharp downward pressure. For months, these asset classes had benefited from discounted cash flow (DCF) models buoyed by the prospect of declining benchmark rates. As those rate-cut timelines were abruptly pushed further into the future, portfolio managers were forced to recalculate equity risk premiums. Concurrently, corporate issuers seeking to tap debt capital markets are now confronting higher yields, forcing CFOs to re-evaluate capital expenditure budgets, infrastructure scalability investments, and strategic mergers and acquisitions.
Compounding the macroeconomic anxiety, legal and regulatory headwinds—including ongoing appeals regarding federal administrative rulings—added an extra layer of policy uncertainty. Yet, it was the monetary policy stance that dominated trading desks. Prime brokerage units reported a surge in hedging activity, with institutional clients aggressively purchasing put options and rotating capital into cash-equivalent short-duration instruments.
Verified Data & Metrics Breakdown Table
| Index / Metric | Closing Level | Daily Percentage Change | Key Macro Driver |
|---|---|---|---|
| S&P 500 | Lower | -0.84% | Broad equity valuation contraction |
| Nasdaq Composite | Lower | -1.22% | Tech valuation multiple compression |
| Dow Jones Industrial Average | Lower | -0.65% | Cyclical and industrial sector pullback |
| Fed Target Inflation Rate | 2.00% (Core PCE) | Unchanged | Strict adherence to statutory mandate |
Industry & Market Implications: Winners, Losers, and Economic Realities
The Federal Reserve's unwavering stance under Chair Warsh creates a distinct bifurcation across global industries. Capital allocation models are undergoing a brutal Darwinian sorting process where balance sheet strength dictates survival and market dominance.
The Losers: High-Beta Growth & Leveraged Enterprises
Sectors reliant on cheap, abundant liquidity are bearing the brunt of the correction. High-beta technology firms, pre-revenue biotech startups, and capital-intensive real estate investment trusts (REITs) face severe valuation headwinds. Enterprises that engineered their growth strategies around low interest rates must now reckon with elevated cost-of-capital realities. Cloud infrastructure providers and software-as-a-service (SaaS) vendors are reporting elongated enterprise sales cycles as corporate clients scrutinize every dollar of cloud compute architecture and software license expenditure, prioritizing near-term enterprise ROI over ambitious long-term R&D expansions.
The Winners: Cash-Rich Defensives & Financial Intermediaries
Conversely, financial institutions boasting robust net interest margins (NIM), high-yield cash generators, and defensive consumer staples conglomerates are outperforming. Asset managers specializing in fixed-income instruments, private credit, and short-duration sovereign debt are experiencing massive inflows as institutional investors seek attractive, risk-free yields hovering near generational highs. Furthermore, multinational corporations with pristine balance sheets and minimal net leverage are uniquely positioned to execute opportunistic mergers and acquisitions, acquiring distressed competitors at distressed valuation multiples.
Frequently Asked Questions (People Also Ask)
Why did Wall Street end lower following Fed Chair Warsh’s remarks?
Wall Street closed lower because Federal Reserve Chair Kevin Warsh explicitly pushed back against market expectations of an impending monetary policy pivot. By stating that inflation is not slowing fast enough and reaffirming the strict 2% core inflation target, Warsh signaled that interest rates will remain higher for a prolonged period, triggering equity valuation multiple compressions across major indices.
What does the "Warsh Doctrine" mean for interest rates and equity valuations?
The Warsh Doctrine represents a hawkish, steadfast commitment to monetary policy restraint aimed at eradicating residual inflationary pressures. For interest rates, it implies an extended plateau at restrictive levels. For equity valuations, particularly in growth-heavy sectors like technology, it forces a downward recalibration of discounted cash flow models, as future earnings are discounted at higher discount rates.
How are institutional investors adjusting their portfolios in response to persistent inflation fights?
Institutional asset managers are implementing risk-mitigation strategies by rotating out of speculative, high-beta growth stocks and into defensive sectors, short-duration fixed income, and cash equivalents. Portfolio construction is increasingly prioritizing companies with strong balance sheets, exceptional free cash flow generation, and proven pricing power capable of weathering high borrowing costs.
What key economic metrics are market analysts monitoring next?
Wall Street economists and quantitative trading desks are closely monitoring upcoming core Personal Consumption Expenditures (PCE) price index releases, monthly non-farm payroll reports, average hourly earnings growth, and treasury auction bid-to-cover ratios to gauge the true resilience of the macro economy against tight monetary conditions.
Future Outlook: Strategic Milestones to Watch
As the financial markets digest the reality of the Warsh-led Federal Reserve, the coming quarters will be defined by macroeconomic resilience and corporate adaptability. Strategic market participants must maintain rigorous risk management discipline, keeping a watchful eye on several critical milestones:
- Upcoming FOMC Rate Decisions: Analysts will dissect every word of upcoming Federal Reserve statement releases and dot-plot projections to identify any subtle shifts in policy consensus regarding the timing of eventual rate cuts.
- Corporate Earnings Season & Guidance: S&P 500 earnings calls will serve as a crucial litmus test, revealing how effectively corporate executives are managing compressed margins, labor cost inflation, and debt refinancing schedules.
- Labor Market & Wage Growth Dynamics: Sustained tightness in employment data will remain the primary catalyst dictating Fed policy; any sudden spike in unemployment or moderation in wage growth could prompt a re-evaluation of the restrictive rate stance.
- Regulatory & Legislative Developments: Ongoing battles over administrative rulings and fiscal policy adjustments will continue to inject volatility into specific sectors, demanding agile regulatory compliance strategies from enterprise leaders.
Ultimately, the latest market retreat serves as a sobering reminder that Wall Street’s fortunes remain inextricably tethered to macroeconomic fundamentals. Navigating this new paradigm requires abandoning hope for a rescue pivot and instead embracing operational excellence, balance sheet fortification, and disciplined capital allocation.