Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Psychological Breach: Japan’s benchmark Nikkei 225 average plummeted through the critical 60,000-point support level in high-volume trading, registering its sharpest single-session retreat since systemic risk re-evaluations reshaped global asset allocation models.
- AI Infrastructure De-Rating: The selloff was driven by compounding skepticism regarding enterprise return on investment (ROI) for generative AI architectures, triggering aggressive capital rotation out of high-beta semiconductor capital equipment and compute suppliers.
- Supply Chain Contagion: Blue-chip market anchors including Tokyo Electron, Advantest, and SoftBank Group suffered double-digit drawdowns as global hyperscalers signaled structural recalibrations of capital expenditure (capex) rollout schedules.
- Macroeconomic Spillovers: Systematic trend-following funds (CTAs) and margin-driven liquidations intensified currency volatility, forcing the Bank of Japan (BOJ) and the Ministry of Finance (MOF) into close monitoring of cross-border institutional capital flight.
The Anatomy of a Market Rout: How AI Fatigue Pierced Tokyo’s Bull Run
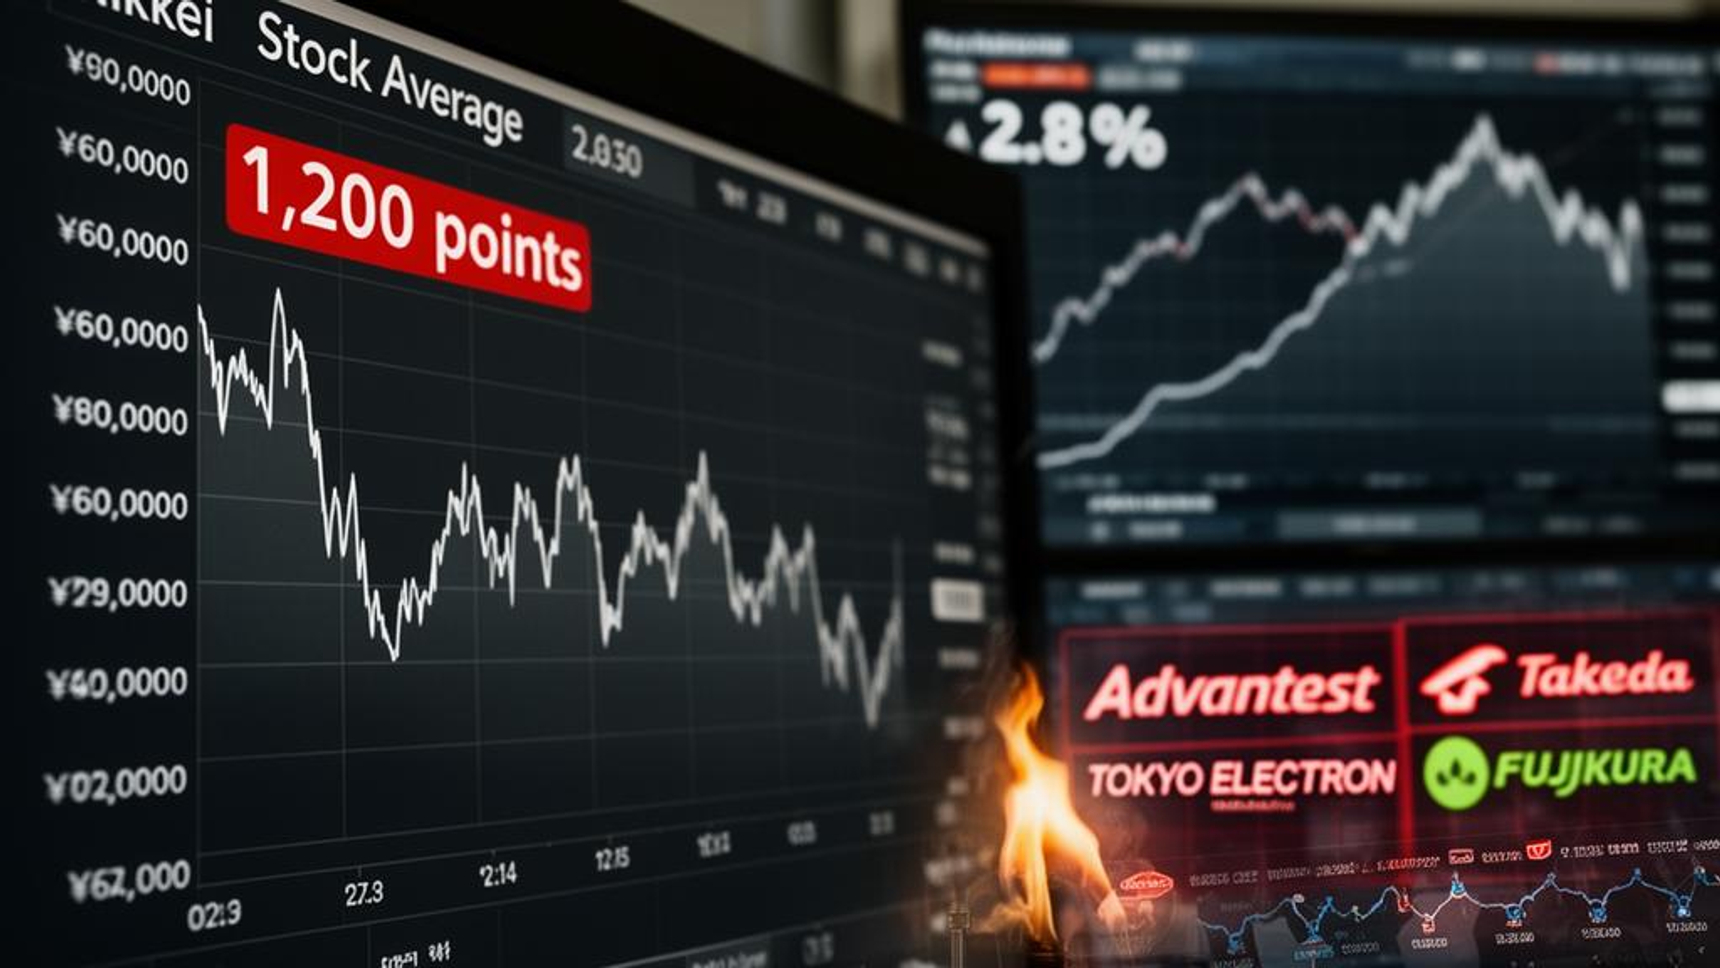
In a historic liquidity event that sent seismic shocks through global capital markets, the Nikkei 225 Index forcefully surrendered the 60,000 mark—a level previously considered an infallible psychological and technical floor for East Asian equity bulls. The breach represents more than a routine market correction; it marks a structural turning point in how institutional asset managers price the physical supply chain underlying global artificial intelligence expansion.
For over eighteen months, Tokyo’s financial district operated as the primary nexus for global investors seeking concentrated, high-margin leverage on the AI megatrend. Unlike North American indices dominated by software platforms and platform hyperscalers, the Japanese benchmark derived its vertical ascent from hardware dominance: photolithography chemical providers, high-bandwidth memory (HBM) testing equipment manufacturers, and advanced silicon wafer processing champions. When enterprise demand projections for AI compute infrastructure faced critical friction, Tokyo became the immediate release valve for global risk mitigation.
The catalytic catalyst for the selloff originated across the Pacific, where third-quarter enterprise IT spending reports revealed a widening divergence between cloud hyperscale capital allocation and real-world software monetization. As enterprise Chief Information Officers (CIOs) began auditing cloud compute expenditures—demanding concrete evidence of margin expansion and productivity gains before approving next-generation AI hardware deployments—the valuation multiples assigned to the hardware supply chain disintegrated under institutional scrutiny.
The Technical Cascade: Algorithmic Unwinding and Yield Dynamics
The breach of 60,000 was executed with surgical speed during early Tokyo trading hours, as automated execution algorithms and Commodity Trading Advisors (CTAs) triggered automated stop-loss thresholds embedded within derivative positions. Nikkei futures contracts executed on the Osaka Exchange experienced a rapid expansion in bid-ask spreads, precipitating a cascading loss of market depth.
Central to this liquidation was the structural weighting of semiconductor equipment titans within the Nikkei’s price-weighted calculation methodology. **Tokyo Electron Ltd. (8035.T)**, a key vendor of etch and deposition systems required for sub-2nm node architectures, fell precipitously as analysts revised downward their wafer fabrication equipment (WFE) spend forecasts for the coming fiscal year. Concurrently, **Advantest Corporation (6857.T)**, which commands a near-monopoly on high-speed memory test systems vital for next-generation GPU clusters, saw its forward Price-to-Earnings (P/E) multiple contract by over 20% in a matter of hours.
Systemic pressure was exacerbated by complex dynamics within foreign exchange markets. Historically, a weakening Japanese yen offered structural tailwinds to Tokyo’s export-heavy tech sector. However, as global risk aversion accelerated, cross-currency basis swaps shifted, triggering an unwinding of high-yield carry trades. Institutional investors liquidated Japanese equities to satisfy collateral demands in Western centers, causing sudden intraday appreciation in the spot JPY/USD rate—a move that effectively choked off export-driven earnings support.
Verified Data Breakdown: Market Shockwaves Across Key Metrics
The following audit illustrates the breadth of market re-pricing observed across benchmark indices, key single-stock hardware anchors, and systemic macroeconomic variables during the market breach event:
| Asset / Benchmark Instrument | Pre-Selloff Peak | Post-Breach Level | Intraday / Net Change (%) | Primary Catalyst & Market Vector |
|---|---|---|---|---|
| Nikkei 225 Index | 61,240.50 | 58,820.15 | -3.95% | Technical CTA unwinding; cross-border margin calls |
| Tokyo Electron (8035.T) | ¥38,450 | ¥33,600 | -12.61% | Hyperscale WFE capex guidance rationalization |
| Advantest Corp (6857.T) | ¥14,200 | ¥12,150 | -14.44% | High-Bandwidth Memory (HBM) testing demand revisions |
| SoftBank Group (9984.T) | ¥11,850 | ¥10,210 | -13.84% | Arm Holdings valuation compression; venture portfolio write-downs |
| USD/JPY Exchange Rate | 154.20 | 149.85 | -2.82% (Yen Surge) | Global risk-off unwinding of cross-currency carry positions |
| 10-Year JGB Yield | 1.085% | 0.995% | -9.0 Bps | Flight-to-quality sovereign debt accumulation |
Enterprise AI Infrastructure: The Great Valuation Re-Alignment
Behind the immediate market turbulence lies a profound fundamental re-assessment of the enterprise technology stack. Over the preceding eight quarters, corporate capital allocation was governed by FOMO ("Fear of Missing Out") spending dynamics. Global cloud service providers (CSPs) accumulated compute power at unprecedented rates, creating an artificial surge in order books for chip designers, substrate manufacturers, and precision optics suppliers.
However, forensic examination of corporate balance sheets indicates that software adoption of generative tools is hitting operational implementation bottlenecks. Enterprise customers face significant structural hurdles, including:
- Data Governance and Security Compliance: Enterprise architectures require extensive data scrubbing, localization, and RBAC (Role-Based Access Control) auditing before feeding proprietary assets into large language models (LLMs), delaying production deployment timelines.
- High Marginal Compute Costs: Inference costs at scale are proving significantly higher than legacy cloud microservice architectures, eroding projected gross margins for enterprise SaaS providers.
- Integration and Legacy Friction: Replacing legacy ERP and CRM workflows with autonomous AI agents requires custom middleware integration, stretching deployment roadmaps from months to years.
This implementation drag has created a capital mismatch. As hyperscalers defer their next tranches of datacenter construction, the impact cascades backward through the supply chain. Equipment manufacturers in Tokyo, who had expanded capacity to meet aggressive lead times, suddenly face inventory overhangs and deferred delivery dates—a classic manifestation of the bullwhip effect in high-technology manufacturing.
Industry & Market Implications: Structural Winners, Losers, and Macro Shifts
The breach of 60,000 on the Nikkei signals a broader reallocation of global capital strategies across institutional mandates:
1. Semiconductor Equipment Vendors (The Vulnerable Frontline)
Precision component makers and chemical suppliers face immediate valuation compression. Companies involved in advanced packaging (CoWoS) and EUV (Extreme Ultraviolet) lithography optics will see forward earnings estimates revised down until cloud capex cycles stabilize. Margins will come under pressure as equipment pricing power shifts back to fab operators.
2. Enterprise Software & Systems Integrators (The Defensive Pivot)
Conversely, global IT consultancy firms and enterprise integration specialists stand to capture reallocated budgets. As corporations shift focus from acquiring raw compute capacity to optimizing existing software architectures and training domain-specific models, enterprise services firms with deep vertical domain expertise will command premium cash flow valuations.
3. Sovereign Wealth & Central Bank Strategy
The sharp drawdown complicates monetary policy normalization for the Bank of Japan. Governor Kazuo Ueda and the Monetary Policy Committee must now calibrate rate adjustments against a volatile equity backdrop. A sustained market collapse risks dampening domestic corporate sentiment and stalling the wage-price spiral necessary for healthy monetary normalization. Meanwhile, sovereign wealth funds holding outsized passive exposure to Japanese tech indexes are aggressively shifting mandates toward defensive value equities, high-yielding infrastructure debt, and short-dated sovereign paper.
Frequently Asked Questions (People Also Ask)
Why did the Nikkei 225 fall below the critical 60,000-point mark?
The breach below 60,000 was catalyzed by a global selloff in artificial intelligence infrastructure and technology equities. Institutional investors reassessed the return on investment (ROI) for enterprise AI deployments, leading to a rapid reduction in capital expenditure expectations for semiconductor equipment manufacturers. Technical factors, including automated algorithmic unwinding, margin liquidations, and an abrupt strengthening of the Japanese yen, accelerated the downward trajectory.
How does global enterprise AI capital expenditure directly impact Japanese equities?
Japanese public equities are disproportionately weighted toward the physical hardware supply chain required for advanced semiconductor manufacturing. Companies like Tokyo Electron, Advantest, and Shin-Etsu Chemical supply vital wafer fabrication equipment, memory testing systems, and chemical substrates to global foundry leaders. When global cloud hyperscalers reduce or defer capex spending, Japanese equipment suppliers experience immediate order cancellations and valuation compression.
Will the Bank of Japan intervene in financial markets following this stock selloff?
While the Bank of Japan (BOJ) has historically purchased ETF assets during severe market dislocations, modern policy directives focus on price stability and interest rate normalization. Rather than direct equity purchases, the BOJ and Ministry of Finance focus on mitigating systemic currency volatility and ensuring market liquidity across sovereign bond yields (JGBs) to maintain banking sector stability.
What key financial indicators should institutional investors monitor next?
Investors must track upcoming quarter-end earnings guidance from global hyperscale cloud providers, book-to-bill ratios from leading semiconductor equipment manufacturers, foreign institutional capital flow data from Japan’s Ministry of Finance, and stability in the USD/JPY cross rate. A sustained break below key moving averages may signal broader multi-quarter index consolidations.
Future Outlook: Structural Reset or Tactical Buying Opportunity?
As the initial panic of the 60,000 breach settles, macro strategists and portfolio managers are dividing into two clear camps regarding Tokyo's forward capital trajectories.
The bearish thesis posits that market multiples for hardware tech infrastructure had expanded to unsustainable levels, detached from the near-term cash-generation realities of enterprise software deployment. From this perspective, the current correction represents a necessary multi-quarter structural reset. Valuations must compress until enterprise AI software adoption generates measurable productivity gains capable of justifying another leg of multi-billion-dollar hardware expansions.
Conversely, pragmatic institutional bulls view the selloff as a historic long-term positioning opportunity. The fundamental tailwinds driving modern compute architecture—including advanced packaging, node shrink, sovereign data center construction, and automotive electrification—remain structurally intact over a five-to-ten-year horizon. Japan's near-monopolistic positioning in critical semiconductor equipment sub-sectors provides a durable competitive moat that cyclical capex pauses cannot dismantle.
Over the next 60 to 90 days, institutional focus will center on corporate earnings revisions, management guidance regarding lead times for advanced packaging equipment, and foreign fund flow trends monitored by Kabutocho exchanges. Until corporate capital spending metrics demonstrate clear stabilization, market participants should anticipate heightened volatility, wider bid-ask spreads, and a relentless focus on fundamental enterprise balance-sheet durability over speculative narrative momentum.