Executive Takeaways
- The $1 Trillion Vaporization: Global equity markets witnessed a severe contraction as high-growth technology equities shed over $1 trillion in cumulative market capitalization in a single trading session.
- Energy Shock: Brent crude breached the $110-per-barrel threshold for the first time since May, driven by compounding geopolitical supply constraints and tightening global market liquidity.
- Valuation Compression: Software-as-a-Service (SaaS), semiconductor manufacturers, and hyper-scalers experienced aggressive multiple compression as discount rates adjusted upward to price in persistent inflationary pressures.
- Strategic Reallocation: Institutional capital is rapidly shifting away from long-duration tech assets toward cash-flowing commodities, defensive sectors, and high-yield fixed income.
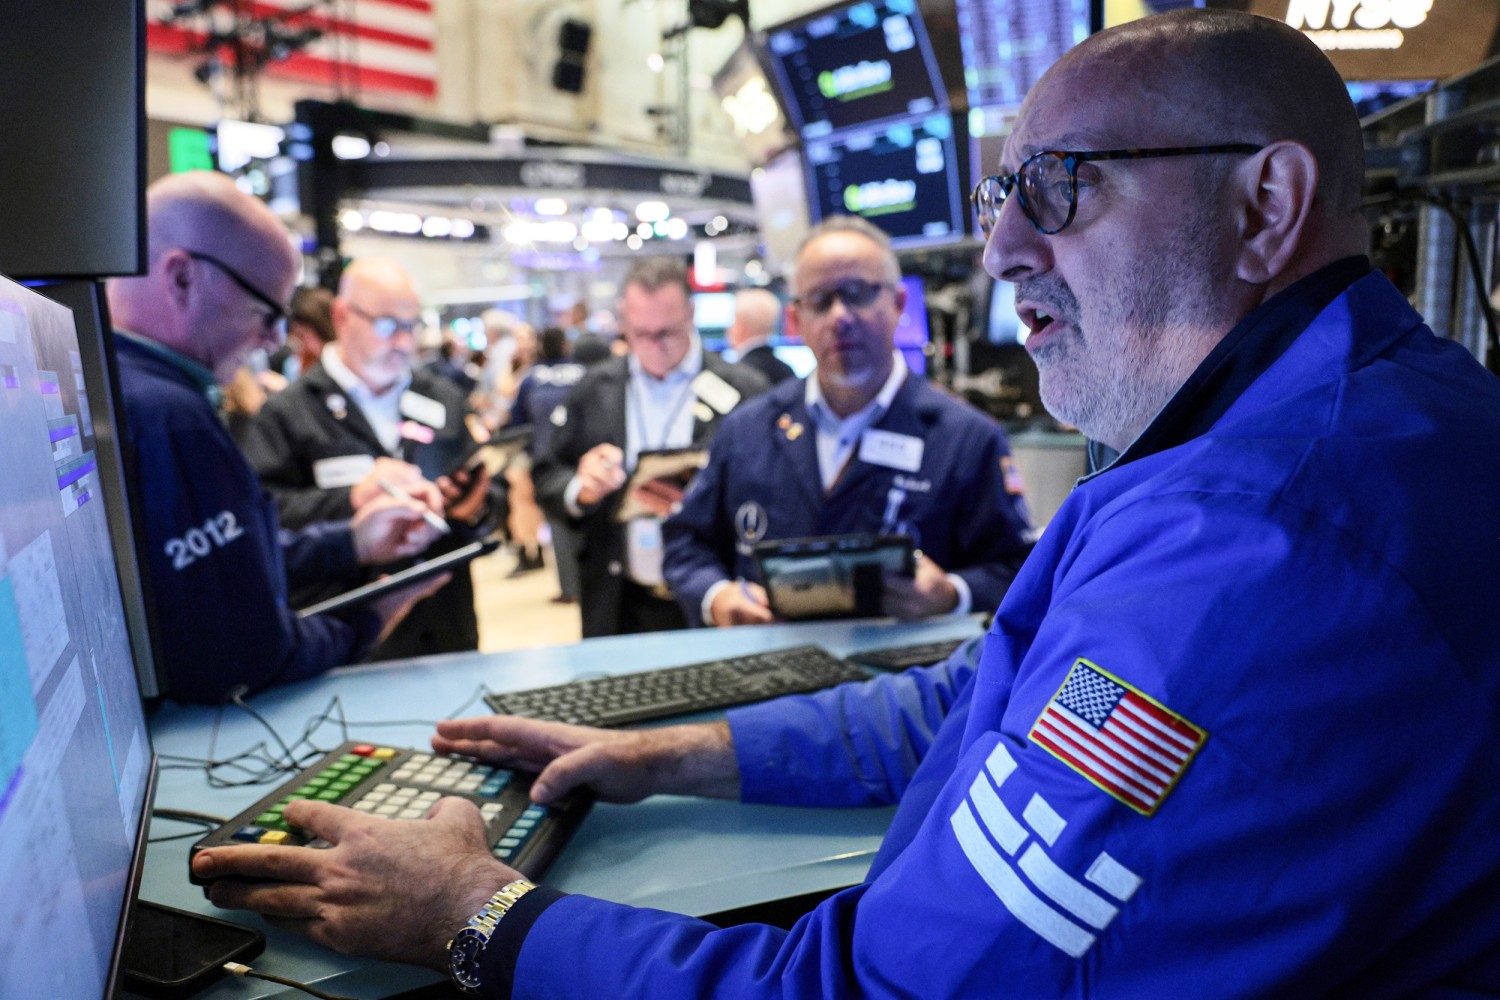
Wall Street woke up to a brutal reality check as a violent convergence of energy market shocks and valuation corrections erased more than $1 trillion in enterprise value across the global technology sector. As Brent crude surged past $110 per barrel for the first time since May, institutional investors rushed to re-evaluate their portfolio risk exposure. The cascading sell-off tore through semiconductor manufacturers, cloud infrastructure providers, and high-growth software firms, exposing vulnerabilities in capital allocation strategies that had relied on assumptions of declining interest rates and stable energy input costs.
The macroeconomic transmission mechanism was swift and unforgiving. Higher energy prices act as a regressive tax on consumers while simultaneously driving up operational expenditures for energy-intensive data centers powering the artificial intelligence boom. As central banks grapple with renewed inflationary impulse, bond yields climbed, forcing quantitative analysts and portfolio managers to recalibrate valuation models. The era of loose capital liquidity has officially collided with physical supply chain constraints, setting off a scramble for risk mitigation and capital preservation.
The Anatomy of the Sell-Off: Catalytic Events and Market Mechanics
The roots of this market rout extend deep into the intricate supply chains of global energy markets and the structural composition of equity indices. For months, tech equities maintained elevated valuation multiples—often trading at forward price-to-earnings ratios well above historical medians—on the premise that enterprise IT spending and AI infrastructure scalability would remain insulated from broader macroeconomic turbulence. However, the sudden spike in crude oil shattered that thesis.
When oil touches $110, the ripples touch every facet of the technology ecosystem:
- Data Center Operational Costs: Cloud computing architecture relies on massive server farms that consume staggering amounts of electricity. Rising energy costs compress EBITDA margins for major cloud providers, forcing them to either absorb the costs or pass them downstream to enterprise clients.
- Hardware and Semiconductor Supply Chains: Silicon wafer fabrication, advanced packaging, and global logistics depend heavily on petroleum-derived products and transportation fuels. Margin pressures at the manufacturing level quickly translate into lower forward earnings guidance.
- Discount Rate Adjustments: Higher energy-driven inflation forces central banks to maintain higher-for-longer interest rates. In discounted cash flow (DCF) models, a higher risk-free rate aggressively penalizes long-duration assets—companies whose projected earnings are heavily weighted far into the future, which is the hallmark of growth tech.
Institutional desks reported heavy algorithmic selling triggered by momentum breaks, followed by discretionary block trades as risk committees enforced strict stop-loss protocols. The concentration of market capitalization in a handful of mega-cap tech stocks meant that when institutional capital began to unwind, the downward pressure dragged down broader indices indiscriminately.
Verified Market Metrics & Comparative Breakdown
To fully grasp the magnitude of the recent market dislocation, the following data table outlines the core financial and macroeconomic metrics driving the current trading environment:
| Metric / Asset Class | Previous Baseline | Current Level | Market Impact & Strategic Implication |
|---|---|---|---|
| Brent Crude Oil | $85 – $92 / bbl | $110.45 / bbl | Triggers cost-push inflation; highest level since May; strains global transport and logistics. |
| Tech Sector Market Cap | All-Time Highs | -$1.02 Trillion Wipeout | Severe multiple compression; aggressive de-risking by institutional equity funds. |
| 10-Year U.S. Treasury Yield | 3.95% | 4.38% | Raises the cost of capital; compresses growth stock valuation multiples. |
| Semiconductor Index (SOX) | Bullish Momentum | -6.4% Daily Drop | Reflects fears of weaker consumer hardware demand and rising fabrication overhead. |
Industry & Market Implications: Winners and Losers
Every major market dislocation creates clear delineations between corporate beneficiaries and casualties. The pivot from a growth-led paradigm to a resource-constrained, inflationary environment has fundamentally altered sector dynamics.
The Losers: High-Multiple Software, Consumer Tech, and Hardware
Enterprise software firms with high customer acquisition costs and deferred profitability are facing intense scrutiny. Chief Information Officers (CIOs) are beginning to audit software budgets, prioritizing essential operational security and infrastructure over experimental deployments. Similarly, consumer-facing hardware manufacturers are bracing for demand destruction as persistent inflation eats into disposable consumer income.
The Winners: Energy Producers, Commodities, and Defensive Yield
Traditional energy majors and upstream oil and gas producers are seeing massive cash flow generation windfalls. Capital is rotating aggressively into commodities as a natural hedge against inflation. Furthermore, short-duration fixed income and high-yield dividend-paying sectors (such as utilities and defense contractors) are absorbing the liquidity fleeing the tech patch.
Frequently Asked Questions (People Also Ask)
Why did the surge in oil prices trigger such a massive sell-off in tech stocks?
When oil prices spike to $110 per barrel, it stokes fears of persistent, sticky inflation. This forces central banks to keep interest rates elevated. Higher interest rates increase the discount rate applied in financial models to calculate the present value of future tech earnings, heavily penalizing growth stocks whose profits are expected years down the line. Additionally, high energy costs raise operational expenses for energy-intensive cloud data centers and semiconductor foundries.
Which specific technology sub-sectors were hit the hardest during the $1 trillion wipeout?
Semiconductor manufacturers, high-growth Software-as-a-Service (SaaS) providers, and consumer electronics firms experienced the most severe multiple compression. Companies that lack immediate, robust cash flow generation and rely heavily on venture debt or low-cost equity financing faced the heaviest institutional selling pressure.
Is this market correction a temporary dip or the start of a structural bear market?
Market strategists remain divided. While many view it as a necessary valuation reset after excessive multiple expansion, institutional desks warn that if oil remains elevated above $110 for a sustained period, corporate earnings guidance for Q3 and Q4 will face downward revisions. The ultimate trajectory depends on upcoming central bank monetary policy decisions and geopolitical developments affecting energy supply lines.
How should institutional asset allocators manage portfolio risk in this environment?
Risk mitigation strategies currently favored by chief investment officers include reducing exposure to high-beta growth equities, increasing allocations to cash-flowing commodities and energy assets, and locking in attractive yields in short-duration fixed-income instruments while maintaining disciplined liquidity buffers.
Future Outlook: What Comes Next and Key Milestones to Watch
As global financial markets digest this trillion-dollar shock, attention turns to upcoming macroeconomic data releases and corporate earnings calls. The interplay between energy market stabilization and monetary policy will dictate equity market direction through the remainder of the fiscal year.
Investors and analysts must monitor several critical milestones:
- OPEC+ Production Announcements: Any indication of output adjustments or resolutions to geopolitical supply blockages will be the primary driver of whether crude oil sustains its $110 footing or retreats.
- Corporate Guidance Revisions: As Fortune 500 tech firms report upcoming quarterly earnings, management commentary regarding enterprise IT spending budgets and margin compression will validate or disprove current valuation models.
- Central Bank Forward Guidance: Upcoming statements from Federal Reserve officials regarding core inflation metrics and interest rate paths will determine the movement of bond yields and, by extension, tech equity valuation multiples.
The events mark a definitive transition from the post-pandemic liquidity cycle into a disciplined, macro-driven operating environment. For corporate executives and institutional investors alike, strategic agility, capital preservation, and rigorous risk management are no longer optional—they are the prerequisites for survival.