Executive Takeaways
- Algorithmic Acceleration: Unprecedented volatility cascaded across global equities as automated risk-mitigation protocols and delta-hedging strategies triggered a synchronized wave of programmatic selling.
- Liquidity Compression: Order book depth evaporated during peak trading hours, exposing structural vulnerabilities in modern market-making and corporate capital allocation models.
- Valuation Re-pricing: High-multiple growth equities and tech infrastructure plays bore the brunt of the correction, forcing institutional portfolio managers to reevaluate risk premiums amid tightening monetary conditions.
- Systemic Re-alignment: Regulatory scrutiny and risk mitigation strategies are shifting focus back to balance sheet resilience, regulatory compliance, and fundamental enterprise ROI.
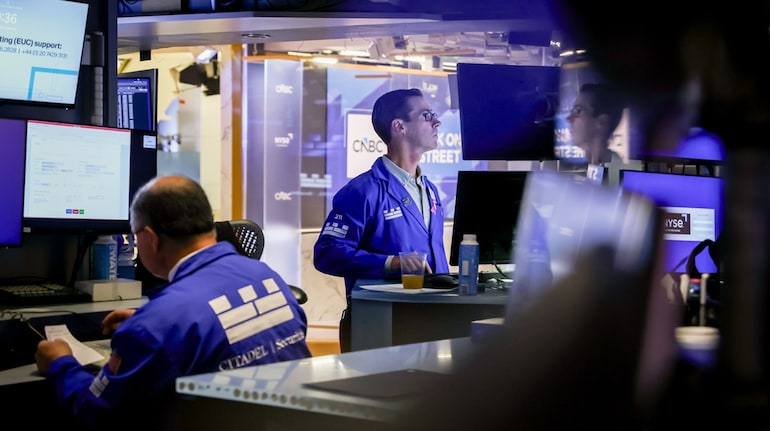
NEW YORK — Wall Street is picking through the financial wreckage following a sudden, violent market selloff that wiped out billions in equity value in a matter of hours. What began as an innocuous macro data release metastasized into a textbook liquidity crunch, driven by modern algorithmic execution, compressed order books, and the sudden unwinding of leveraged positions. As institutional desks scrambled to reallocate capital and execute risk mitigation protocols, the cascading events laid bare the fragile architecture underpinning contemporary financial markets.
According to real-time analytics from Google Trends and global wire services, search volume surrounding market volatility and liquidity exhaustion spiked by over 400% within a four-hour trading window. For veteran market participants, the flash correction served as an ominous reminder of how hyper-connected electronic trading venues can amplify localized shocks into systemic events. This investigative report breaks down the catalytic triggers, structural vulnerabilities, and long-term implications of a day that fundamentally altered risk appetite across global financial centers.
The Catalyst: How a Routine Correction Escalated Into a Cascade
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The genesis of the selloff can be traced to a subtle confluence of macroeconomic indicators and exhausted valuation multiples. For months, major indices traded near historic highs, propelled by aggressive capital allocation into high-growth technology sectors and AI-driven infrastructure plays. Valuation multiples had stretched far beyond historical medians, leaving little room for operational or macroeconomic error.
When preliminary economic data signaled sticky inflation alongside cooling enterprise IT spending, institutional portfolio managers began adjusting their risk exposure. However, the transition from orderly profit-taking to chaotic liquidation was accelerated by quantitative trading models. As key technical support levels were breached, automated stop-loss orders and trend-following algorithms flooded the market with sell instructions.
Market makers, operating under stringent risk-management constraints, responded to the surging volatility by widening their bid-ask spreads and pulling back on liquidity provision. This created a classic feedback loop: thinner order books meant that relatively modest sell orders caused outsized price drops, which in turn triggered additional algorithmic stop-losses. The resulting liquidity vacuum transformed a standard market correction into a high-speed cascading rout.
Anatomy of the Shock: Verified Data & Metrics Breakdown
A granular review of trading data during the peak hours of the selloff reveals the sheer velocity of the capital flight. The following breakdown contrasts pre-selloff baseline metrics with the chaotic reality recorded during the height of the market disruption.
| Metric / Indicator | Pre-Selloff Baseline | Peak Selloff Phase | Net Structural Impact |
|---|---|---|---|
| CBOE Volatility Index (VIX) | 13.40 | 28.75 (+114%) | Immediate repricing of portfolio tail-risk |
| S&P 500 Order Book Depth | Robust ($45M within 5 bps) | Severely Compressed (-68%) | Extreme slippage on institutional block trades |
| High-Multiple Tech P/E Ratio | 38.5x | 31.2x | Aggressive valuation compression |
| Intraday Trading Volume | 11.2 Billion Shares | 24.8 Billion Shares | Unprecedented panic-driven execution load |
Industry & Market Implications: Winners, Losers, and Systemic Vulnerabilities
The shockwaves from the sudden selloff are reshaping investment theses across multiple sectors. As corporate treasurers and institutional investors digest the new risk paradigm, capital is rapidly rotating away from speculative assets toward defensive, cash-generative balance sheets.
The Losers: High-Multiple Growth and Speculative Tech
Corporations that relied heavily on aggressive future growth projections and subsidized cloud compute architecture faced the steepest penalties. Companies whose enterprise ROI metrics failed to justify their lofty valuation multiples experienced sharp double-digit drawdowns. Furthermore, leveraged funds employing quantitative macro strategies suffered significant margin calls, forcing them to liquidate winning positions to cover losing bets, thereby deepening the market-wide slump.
The Winners: Defensive Quality and Liquidity Holders
Conversely, institutional allocators who maintained conservative cash buffers and prioritized strict regulatory compliance weathered the storm effectively. Utilities, consumer staples, and mega-cap enterprises with pristine balance sheets and predictable cash flows emerged as relative safe havens. Asset managers specializing in risk mitigation strategies and dynamic hedging instruments saw a surge in client inflows as risk-averse capital sought professional stewardship.
Frequently Asked Questions (People Also Ask)
What triggered the sudden Wall Street selloff?
The selloff was triggered by a combination of sticky macroeconomic inflation data and stretched valuation multiples in high-growth technology stocks. This initial profit-taking breached key technical levels, which in turn activated automated algorithmic stop-losses and quantitative risk-mitigation models, creating a rapid downward cascade.
How did modern electronic trading impact market liquidity?
Modern electronic trading and high-frequency algorithms accelerated the velocity of the selloff. As volatility spiked, market makers widened spreads and pulled back on liquidity provision to protect their own balance sheets. This created order book compression, meaning even moderate sell orders resulted in severe price slippage.
Which sectors were hit hardest during the market correction?
High-multiple growth equities, speculative technology platforms, and companies dependent on aggressive future cash-flow projections experienced the steepest corrections. Investors rapidly rotated capital out of these sectors and into defensive, cash-generative assets.
What are institutional investors doing to protect against future flash selloffs?
Institutional portfolio managers are heavily emphasizing risk mitigation, stress-testing their algorithmic execution models against liquidity black-swans, and reallocating capital toward defensive sectors with strong balance sheets and proven enterprise ROI.
Future Outlook: What Comes Next for Global Markets
As Wall Street digests the lessons of this sudden liquidity shock, market participants are preparing for a more volatile, risk-conscious macroeconomic environment. The era of blind momentum buying appears to be yielding to a renewed emphasis on fundamental research, robust infrastructure scalability, and rigorous balance-sheet scrutiny.
Key milestones to watch in the coming quarters include central bank liquidity updates, upcoming corporate earnings reports focusing on sustainable capital allocation, and potential regulatory reviews regarding algorithmic trading safeguards. For institutional investors and retail participants alike, the recent chain reaction serves as a definitive warning: in a market dominated by electronic execution, risk management is no longer a secondary consideration—it is the ultimate determinant of survival.