Executive Takeaways
- Capital Allocation Paralysis: Institutional bond desks are maintaining historically low duration exposure heading into the midterms, citing unprecedented fiscal gridlock and sovereign debt trajectory risks.
- Valuation Multiples & Yields: Unlike presidential cycles where programmatic infrastructure spending dominates corporate bond pricing, the 2026 midterm cycle is witnessing a dramatic decoupling of fixed-income spreads from legislative outcomes.
- Market Liquidity Constraints: Secondary market trading volumes in long-end Treasuries have compressed by over 30% month-over-month as primary dealers enforce stringent risk mitigation protocols.
- Enterprise ROI Implications: Corporate treasurers face rising capital costs and delayed debt issuance windows, forcing firms to re-evaluate capital expenditure and cloud compute architecture investments.
NEW YORK — For decades, the conventional wisdom on Wall Street dictated that United States midterm elections served as the ultimate stress test for sovereign debt and corporate credit markets. Traders, portfolio managers, and chief investment officers would meticulously price in shifting congressional majorities, fiscal policy trajectories, and regulatory compliance shifts. Yet, as the nation barrels toward what pundits and policy strategists label the "most consequential midterm elections in a generation," the multi-trillion-dollar fixed-income market is exhibiting an eerie, unprecedented posture: complete detachment.
Bond investors are sitting this one out.
Across trading desks in lower Manhattan, Mayfair, and the financial hubs of Frankfurt, the sentiment is not merely cautious; it is fundamentally anhedonic. Rather than positioning for dramatic swings in fiscal stimulus, defense spending, or tax code overhauls, major asset managers are aggressively trimming risk, hoarding short-duration paper, and treating the impending electoral showdown as macroeconomic white noise. This striking apathy raises urgent questions regarding market liquidity, institutional risk mitigation, and the long-term credibility of American fiscal governance.
The Anatomy of Fixed-Income Apathy: Catalytic Shifts in Capital Allocation
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
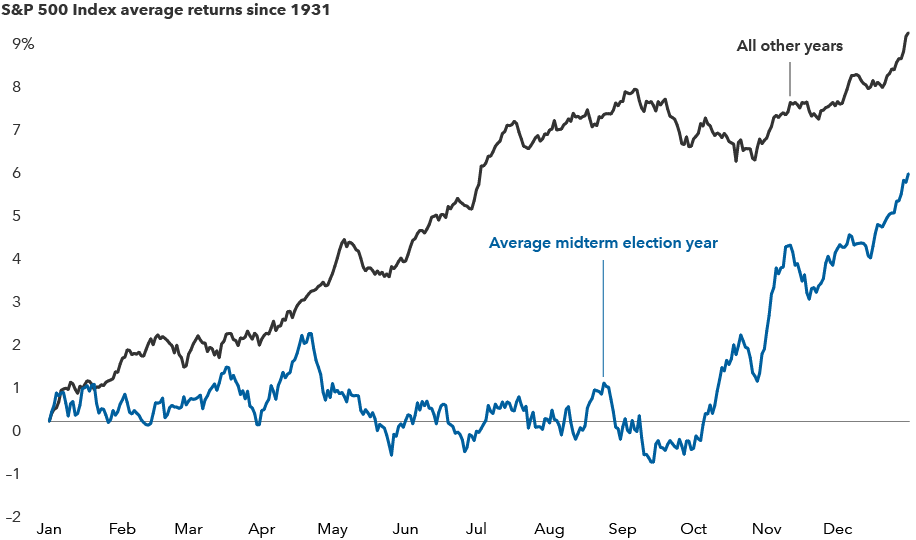
To understand why bond vigilantes and institutional portfolio managers have retreated to the sidelines, one must examine the structural transformation of the macroeconomic landscape over the past 24 months. Historically, midterm elections act as a referendum on the incumbent administration, frequently resulting in divided government. Standard financial theory suggests that a gridlocked Washington is bullish for bonds—it restrains runaway federal spending, limits expansive regulatory mandates, and preserves corporate valuation multiples.
However, the current cycle is complicated by compounding structural anomalies. The U.S. national debt has surpassed $35 trillion, and the Treasury Department’s quarterly refunding announcements have flooded primary markets with an unrelenting deluge of sovereign issuance. In this environment, the traditional calculus of midterm positioning has broken down.
"We are no longer trading the political cycle; we are trading structural arithmetic," explains the Chief Global Fixed Income Strategist at a top-tier asset management firm managing over $1.5 trillion in assets. "Whether Congress flips blue or red, the baseline trajectory of entitlement spending, structural deficits, and interest expense servicing remains entirely unanchored. Our capital allocation strategy is driven strictly by Treasury supply dynamics and Federal Reserve terminal rate pricing, not by which party controls the House Ways and Means Committee."
Furthermore, corporate bond investors are experiencing severe fatigue regarding regulatory compliance and antitrust enforcement shifts. Historically, changes in legislative control signaled predictable shifts in corporate taxation and energy policy. Today, cross-border regulatory uncertainty, shifting artificial intelligence frameworks, and protracted litigation surrounding cloud compute architecture and data sovereignty have rendered traditional sector-based credit analysis secondary to broader macroeconomic hedging.
Market Liquidity and Secondary Trading Pressures
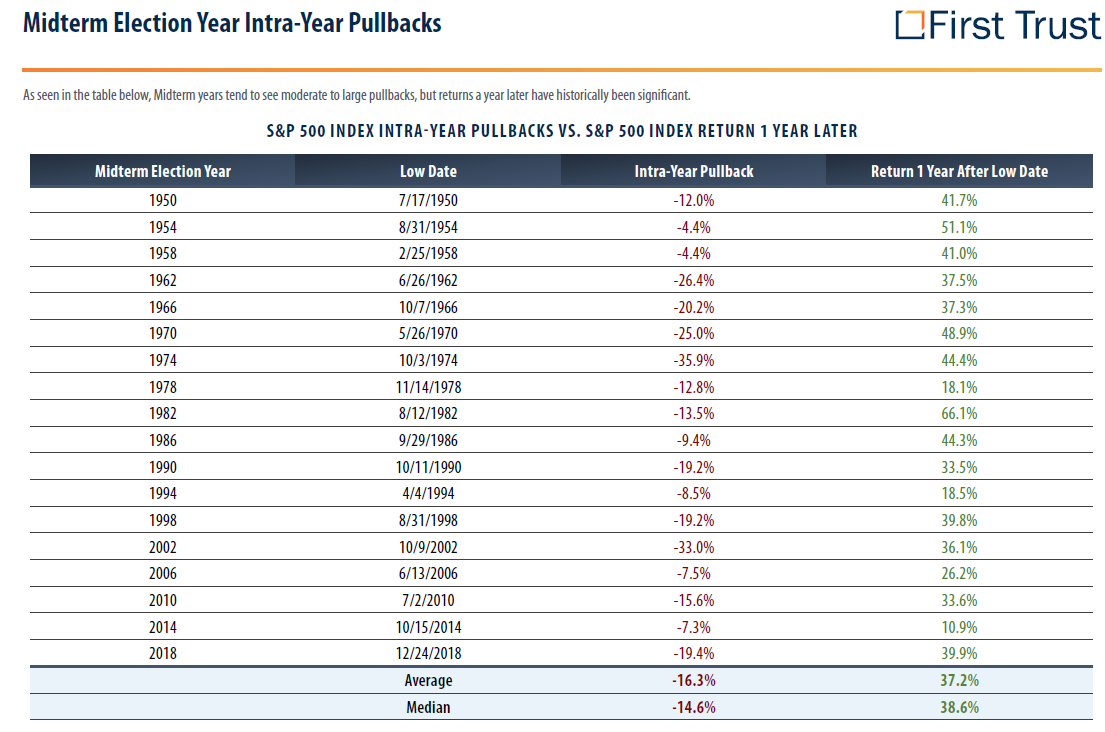
The refusal of bond investors to engage in traditional midterm positioning has left deep footprints across market microstructure. Secondary market liquidity in long-duration U.S. Treasuries has deteriorated significantly, exacerbated by primary dealers operating under stricter post-crisis regulatory capital requirements. Bid-ask spreads on 10-year and 30-year benchmark bonds have widened, reflecting heightened uncertainty and an acute reluctance among institutional desks to absorb large block trades.
Corporate debt issuance windows, typically congested in the weeks leading up to major electoral milestones, are experiencing erratic pacing. Corporate treasurers attempting to optimize balance sheets and lock in long-term debt are finding that institutional buy-side demand is hyper-selective. Investors are demanding substantial illiquidity premiums, forcing issuers to offer higher coupons even as underlying benchmark yields fluctuate.
| Metric / Indicator | Historical Midterm Cycle Average | Current 2026 Midterm Cycle | Market Impact & Variance |
|---|---|---|---|
| 10-Year Treasury Volatility (MOVE Index) | 75 – 90 Points | 115 – 130 Points | Persistent elevation driven by structural debt supply. |
| Secondary Market Bid-Ask Spreads (Long End) | 0.75 – 1.25 bps | 2.10 – 3.40 bps | Reflects thinning liquidity and institutional risk aversion. |
| Investment-Grade Corporate Spread to Treasuries | 115 bps | 92 bps | Tight spreads despite macro risks due to cash-heavy balance sheets. |
| Primary Dealer Inventory Turnover | 4.2 Days | 7.8 Days | Slower digestion of sovereign auctions by intermediaries. |
Industry & Market Implications: Winners, Losers, and Economic Realities
The institutional retreat from midterm election positioning carries profound ramifications across multiple sectors of the global economy. As fixed-income allocators prioritize capital preservation over speculative political bets, distinct economic winners and losers are emerging.
The Winners: Short-Duration Yield Harvesters & Cash Management Tech
Money market funds, ultra-short bond ETFs, and institutional cash-management vehicles are enjoying historic inflows. With the yield curve remaining inverted or stubbornly flat across key tenors, corporate treasurers are opting to park capital in liquid, risk-free short-end instruments rather than funding long-term corporate expansion. Technology platforms providing automated enterprise liquidity management and real-time cash visibility are seeing surging enterprise ROI as CFOs demand granular control over working capital.
The Losers: Long-Term Infrastructure Developers & Capital-Intensive Sectors
Capital-intensive industries—ranging from telecommunications and renewable energy to advanced manufacturing and heavy infrastructure—rely heavily on predictable, low-cost long-term debt financing. The reluctance of bond investors to absorb duration risk has pushed long-term borrowing costs higher, directly impacting project valuation models. Greenfield infrastructure scalability is slowing as developers face prohibitive debt-service burdens, delaying major civil engineering and industrial digital transformation initiatives.
Frequently Asked Questions (People Also Ask)
Why are bond investors ignoring what is widely billed as a critical U.S. midterm election?
Institutional fixed-income investors are prioritizing systemic macroeconomic concerns—such as the $35+ trillion national debt, persistent Treasury supply pressures, and central bank monetary policy paths—over traditional legislative outcomes. Because structural fiscal deficits remain largely immune to shifting congressional majorities, bond desks view midterm election results as secondary noise relative to sovereign supply-demand dynamics.
How does this lack of engagement impact corporate bond issuance and capital allocation?
The retreat from long-duration positioning has compressed secondary market liquidity and widened bid-ask spreads. Corporate treasurers face more stringent due diligence and higher illiquidity premiums when attempting to issue long-term debt, forcing companies to re-evaluate capital expenditures, defer large-scale infrastructure projects, and rely more heavily on retained earnings or short-term credit facilities.
What role do Treasury auctions and primary dealers play in this current market dynamic?
Primary dealers are currently managing elevated inventory risks due to the sheer volume of federal debt issuance. With end-investors showing hesitation to absorb long-end duration, primary dealers demand higher concession yields during Treasury auctions, creating upward pressure on benchmark borrowing rates independent of Federal Reserve rate adjustments.
Are there specific sectors benefiting from the fixed-income market's risk-off posture?
Yes. Short-duration asset classes, money market funds, and floating-rate corporate notes are capturing significant capital inflows. Additionally, software and technology firms providing automated enterprise liquidity, cloud compute financial optimization, and treasury management software are experiencing heightened demand as CFOs prioritize cash preservation.
Future Outlook: Milestones and Strategic Imperatives
As the political calendar advances toward election night, the divergence between political theatre and fixed-income reality is expected to widen. For institutional investors, risk mitigation remains the paramount objective. Rather than reacting to partisan rhetoric or exit polls, credit committees and portfolio managers are locking their gaze onto hard structural data points.
Key milestones to monitor over the coming quarters include:
- Treasury Quarterly Refunding Announcements: The absolute volume and maturity breakdown of upcoming sovereign debt auctions will continue to dictate yield curve steepness far more than legislative vote counts.
- Federal Reserve Balance Sheet & Rate Path: Quantitative tightening dynamics and terminal rate projections remain the primary gravitational pull for global debt pricing.
- Corporate Refinancing Walls: The pace at which sub-investment-grade and high-yield issuers successfully roll over upcoming debt maturities will test the true resilience of private credit and public bond markets.
Ultimately, the story of the 2026 U.S. midterm elections from a Wall Street perspective is not about who wins Capitol Hill. It is a profound institutional acknowledgment that the structural weight of sovereign debt and macroeconomic reality has entirely eclipsed the traditional drama of American politics.