Executive Takeaways
- Legislative Gridlock vs. Subsidies: Institutional investors are aggressively stress-testing portfolios against various configurations of Congressional control, balancing the survival of the CHIPS and Science Act against potential fiscal tightening.
- AI Infrastructure CAPEX Velocity: Hyperscalers and enterprise buyers are recalibrating cloud compute architecture investments based on upcoming regulatory compliance frameworks and bipartisan data center permitting reform.
- Valuation Multiples at Risk: Capital allocation strategies are shifting toward risk mitigation as tech-heavy equity portfolios face heightened sensitivity to corporate tax rates and federal research appropriations.
- Market Liquidity Dynamics: Fixed-income desks and equity macro strategists are positioning for sovereign debt issuance shifts that could directly impact long-duration technology asset pricing.
As election cycles converge with an unprecedented technological paradigm shift, Wall Street’s elite quantitative strategists, macro-economists, and policy analysts are engaged in a high-stakes analytical exercise: gaming out every conceivable permutation of Congressional control. The primary objective is not merely predicting legislative winners and losers; it is mapping the direct trajectory of federal spending, regulatory scrutiny, and the multi-trillion-dollar artificial intelligence (AI) infrastructure boom.
For institutional asset managers, sovereign wealth funds, and private equity titans, the stakes could not be higher. The intersection of fiscal policy, congressional oversight, and enterprise technological adoption is dictating capital allocation models worldwide. From the silicon wafer fabrication plants of Arizona and Taiwan to the massive, power-hungry data center campuses rising across Northern Virginia and the Midwest, the flow of capital is inextricably linked to the legislative posture of Capitol Hill.
The Macro Catalyst: Why Congress Control Dictates Tech Valuations
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The relationship between Washington D.C. and Silicon Valley has traditionally been viewed through the lens of antitrust scrutiny and data privacy legislation. However, the maturation of generative AI has transformed the federal government into an active participant—and principal financier—of the technology sector. Through historic legislative frameworks like the CHIPS and Science Act and the Inflation Reduction Act, federal appropriations have become a foundational pillar of enterprise ROI for semiconductor manufacturers, cloud infrastructure providers, and energy grid operators.
Consequently, the composition of the 119th Congress carries profound implications for fiscal policy and industrial strategy. Investors are currently modeling three distinct electoral scenarios:
- The Unified Government Scenario: A single party controlling both the White House and Capitol Hill, opening the door for streamlined budget reconciliations, targeted industrial subsidies, and aggressive regulatory agendas—though potentially accompanied by higher corporate tax burdens or increased debt issuance.
- The Divided Government Scenario: A split Congress (e.g., a Democratic Senate and Republican House, or vice versa), which historically guarantees legislative gridlock, protecting existing corporate tax structures while forcing bipartisan compromises on critical national security technology initiatives.
- The Bipartisan Consensus Scenario: Rare moments of alignment where national security imperatives, specifically counteracting international competitors in AI and semiconductor manufacturing, supersede partisan divides to maintain robust capital appropriations.
Institutional desks are utilizing sophisticated econometric modeling to simulate how each scenario impacts valuation multiples, free cash flow generation, and the cost of capital for hyper-growth technology enterprises.
AI Infrastructure Scalability and the Washington Bottleneck

While venture capitalists and public equity markets have fixated on software algorithms and large language model (LLM) parameter counts, savvy institutional investors recognize that the true bottleneck for AI adoption is physical: power, silicon, and permitting. Here, Congressional oversight and federal agency appointments hold immense sway.
Energy Grid Integration and Data Center Compute Architecture
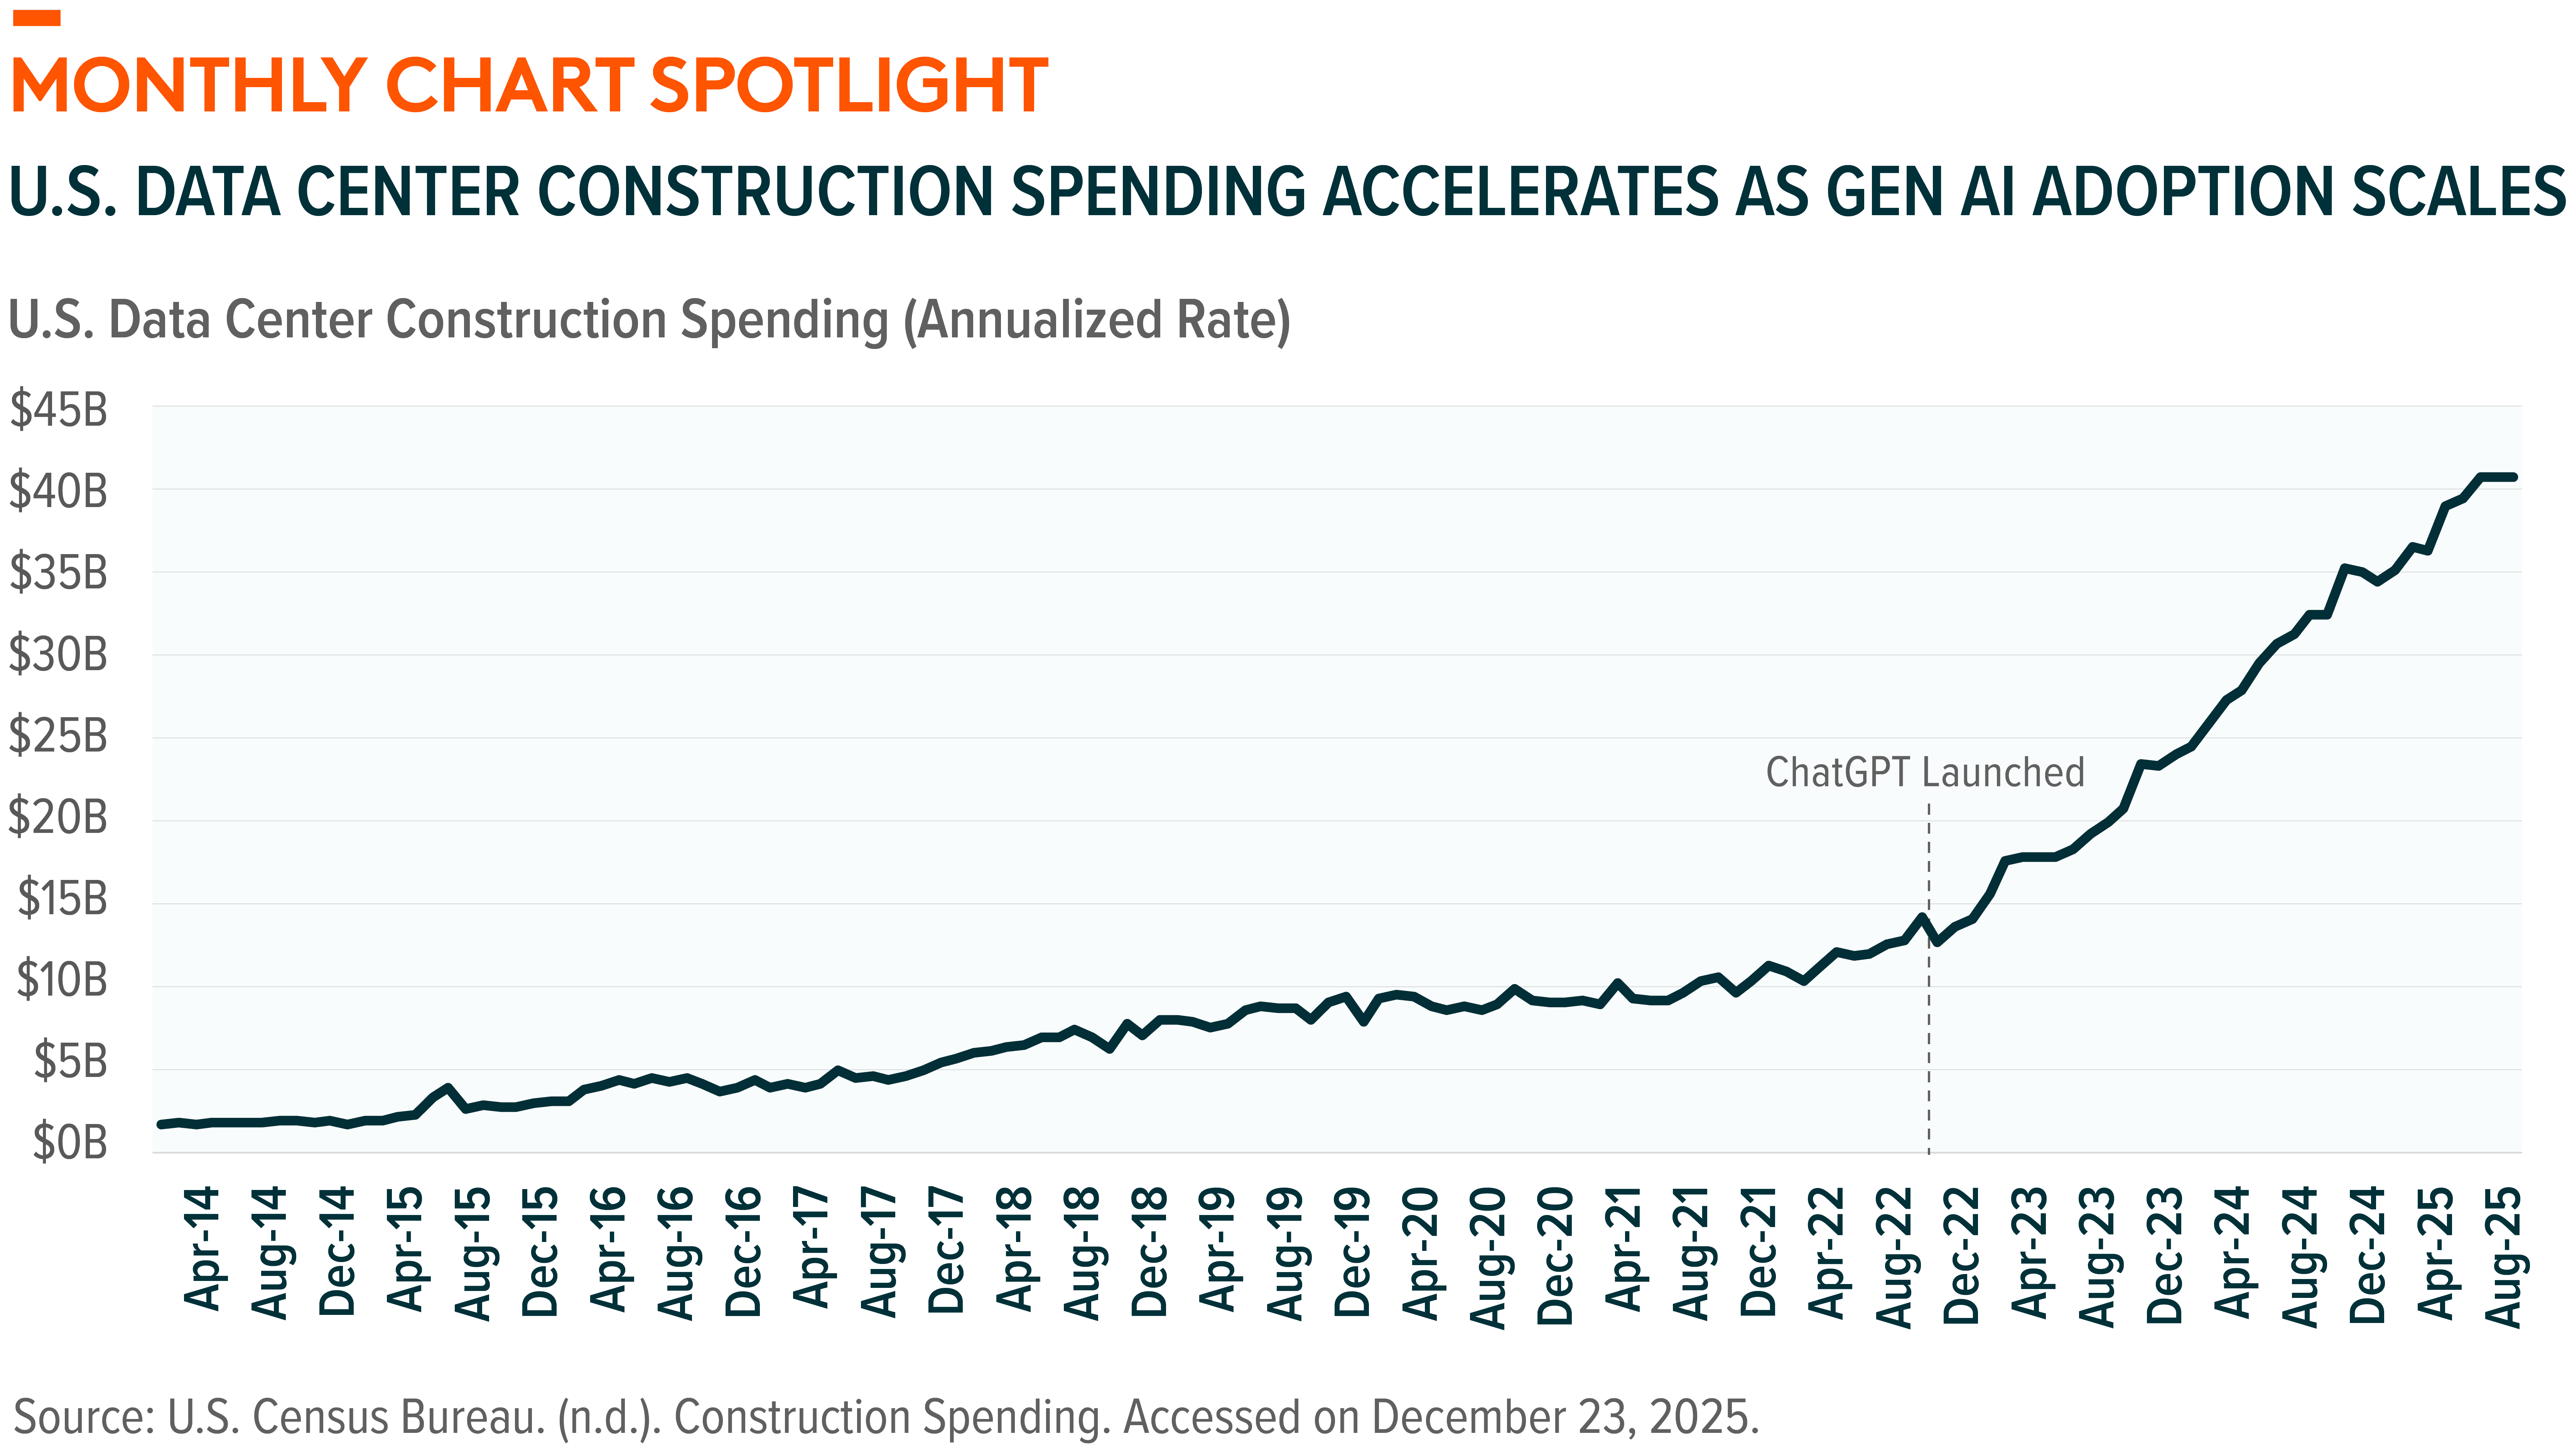
Training and deploying frontier AI models requires unprecedented levels of electrical power. Hyperscalers—including Microsoft, Google, Amazon, and Meta—are aggressively securing long-term power purchase agreements (PPAs), frequently turning to nuclear and natural gas assets to feed power-hungry data center campus builds.
However, the buildout of high-voltage transmission lines and the integration of these facilities into the national grid are subject to intense federal regulatory compliance managed by the Federal Energy Regulatory Commission (FERC) and the Department of Energy. A Congress focused on energy independence and grid modernization could fast-track transmission permitting reform, unlocking billions in stalled infrastructure spending. Conversely, a gridlocked or hyper-polarized legislature could delay crucial capital deployment, compressing the projected margins of utilities and tech operators alike.
Semiconductor Supply Chains and Export Controls
The geopolitical dimension of AI remains a bipartisan priority, yet the nuances of execution vary sharply across political lines. Bureaucratic oversight of export controls, Bureau of Industry and Security (BIS) regulations, and the disbursement of remaining CHIPS Act grants heavily influence where semiconductor firms build out their next-generation fabrication plants.
Investors gaming out Congressional control are closely monitoring committee assignments—specifically the House Committee on Science, Space, and Technology and the Senate Committee on Commerce, Science, and Transportation. The leadership of these committees will dictate whether federal funding for advanced packaging, quantum computing, and neuromorphic engineering expands or faces contraction amid broader deficit-reduction efforts.
Verified Data: Macro-Tech Fiscal Metrics Comparison
| Legislative / Economic Vector | Unified Government Impact | Divided Government Impact | Primary Market Risk |
|---|---|---|---|
| CHIPS Act Funding & Subsidies | Accelerated disbursement; potential expansion into downstream AI hardware. | Status quo maintenance; bureaucratic delays in unallocated tranche releases. | Capital expenditure contraction for second-tier foundry suppliers. |
| Corporate Tax Rates (TCJA Expirations) | High volatility; risk of rate hikes under Democratic control or deficit-funded extensions under Republican control. | Prolonged negotiation resulting in temporary extensions and compromise rates. | Net income compression and repatriation friction for multinational tech firms. |
| AI Regulatory Frameworks | Comprehensive federal legislation or sweeping executive agency rulemakings. | Fragmented state-level patchwork of privacy and algorithmic bias laws. | Compliance cost inflation and slowed enterprise software deployment velocity. |
| Sovereign Debt & Treasury Yields | Potential for increased deficit spending, upward pressure on long-duration yields. | Fiscal restraint via budget standoffs; intermittent volatility in fixed-income liquidity. | Discount rate expansion dampening high-growth tech valuation multiples. |
Industry & Market Implications: Winners, Losers, and Capital Rotation
As portfolio managers rebalance asset allocations based on political risk models, clear sector winners and losers are emerging across global equity markets.
The Winners: Defense Tech, Domestic Foundries, and Grid Modernizers
Companies positioned at the intersection of national security and advanced computing are seeing robust inflows. Defense contractors developing autonomous systems, domestic semiconductor foundries insulated from foreign supply chain shocks, and electrical equipment manufacturers supplying transformers and switchgear to data centers are enjoying structural tailwinds. Regardless of which party holds Congress, these sectors benefit from bipartisan consensus regarding strategic autonomy.
The Vulnerable: High-Multiple Software and Over-Leveraged Infrastructure
Conversely, speculative software-as-a-service (SaaS) providers lacking clear enterprise ROI metrics face capital flight. Furthermore, capital-intensive infrastructure plays that rely heavily on low interest rates and uninterrupted debt financing are vulnerable if legislative gridlock causes prolonged Treasury market volatility or if tax reforms alter corporate borrowing costs.
Frequently Asked Questions (People Also Ask)
How does Congressional control directly impact AI corporate spending?
Congressional control dictates federal budget allocations, R&D tax credits, and the enforcement of the CHIPS and Science Act. A supportive legislature can accelerate public-private partnerships and subsidize domestic data center and silicon manufacturing, whereas fiscal tightening or gridlock can delay capital deployment and alter corporate investment horizons.
Are tech stock valuations currently pricing in political gridlock?
Partially. Sophisticated institutional desks price in baseline regulatory risks and potential tax code expirations, but sudden shifts in Congressional majorities routinely trigger sector-wide rotations. High-multiple growth stocks remain particularly sensitive to changes in long-duration Treasury yields driven by federal borrowing projections.
What is the role of federal permitting reform in the AI infrastructure boom?
Data centers require massive, uninterrupted power supplies. Federal permitting reform—governing transmission lines, natural gas pipelines, and nuclear plant licenses—determines how quickly energy providers can connect new power generation assets to hyperscale data center campuses. Legislative bottlenecks in Congress directly constrain the physical scalability of AI compute infrastructure.
Which regulatory bodies are investors monitoring most closely alongside Congress?
Beyond Congressional committees, institutional investors monitor the Federal Trade Commission (FTC), the Department of Justice (DOJ) Antitrust Division, the Federal Energy Regulatory Commission (FERC), and the Department of Commerce’s Bureau of Industry and Security (BIS) for rules governing cloud computing dominance, AI model openness, and semiconductor export controls.
Future Outlook: Key Milestones and Strategic Positioning
Looking ahead, executive leadership and institutional investment committees must maintain agile risk-mitigation strategies. As legislative calendars unfold and election outcomes crystallize, market participants should monitor several critical milestones:
- Congressional Committee Chair Assignments: The appointment of key leaders in Senate and House commerce, armed services, and budget committees will signal the legislative appetite for tech subsidies and regulatory oversight.
- Federal Agency Budget Appropriations: Finalized omnibus spending bills will reveal the immediate funding velocity for federal AI initiatives, defense tech integration, and energy grid expansion.
- Tax Code Negotiations: Corporate tax provisions and R&D amortization rules under upcoming fiscal deadlines will heavily influence quarterly free cash flow projections for large-cap technology firms.
Ultimately, the intersection of politics and technology has entered a permanent structural phase. Investors who successfully model the granular impacts of Congressional control on AI infrastructure and liquidity dynamics will capture outsized returns, while those reliant on historical macro assumptions risk severe valuation dislocation.