Executive Takeaways
- Market Sell-Off: The Dow Jones Industrial Average slid sharply on October 23, 2026, pressured by surging energy input costs and a broader flight from equity risk.
- Commodity Catalyst: Brent and WTI crude futures climbed to their highest settlement levels in five months, directly threatening corporate operating margins and supply chain economics.
- Capital Allocation Shift: Institutional investors are rapidly reassessing valuation multiples, rotating capital out of high-growth technology and consumer discretionary assets into defensive infrastructure and cash equivalents.
- Monetary Policy Strains: The persistent energy price escalation complicates the Federal Reserve’s risk mitigation framework, threatening a resurgence of sticky core inflation.
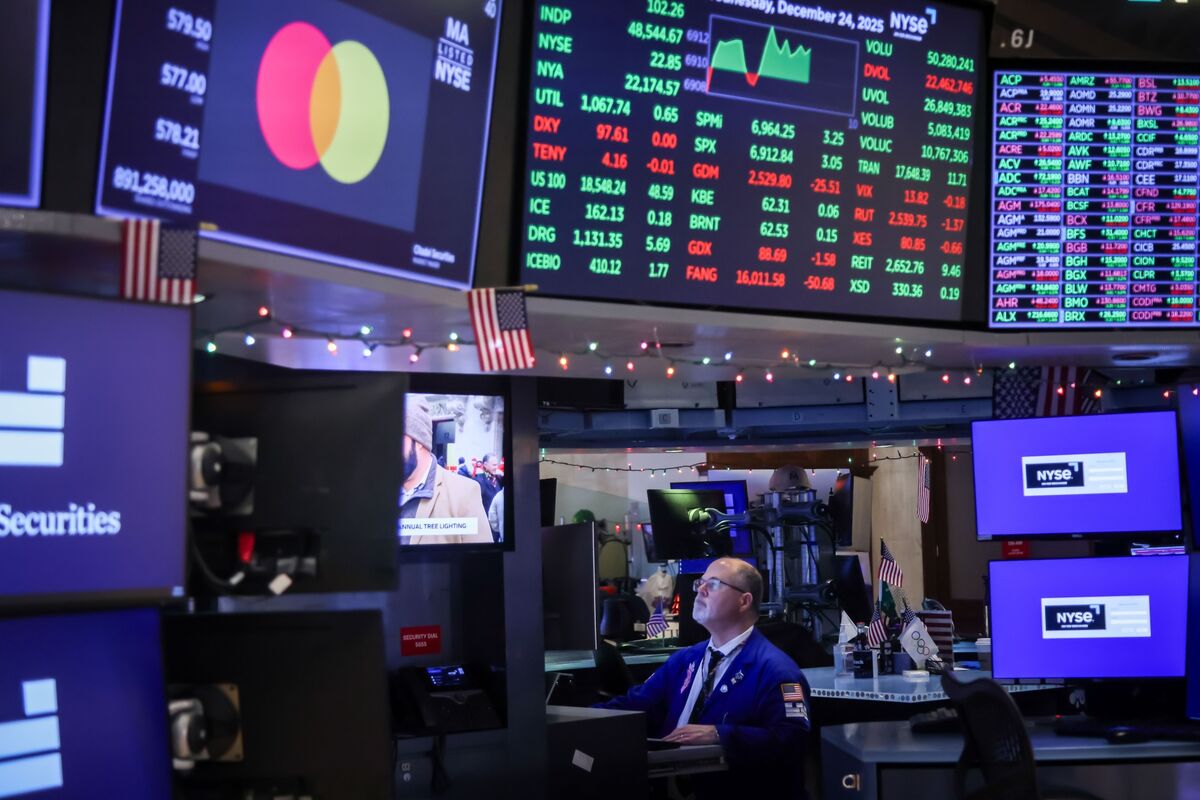
NEW YORK — In a stark reminder of the fragile nexus between global energy security and domestic equity valuations, Wall Street endured a punishing session on Friday, October 23, 2026. The Dow Jones Industrial Average retreated significantly, dragged down by an aggressive spike in crude oil prices that touched five-month highs. As geopolitical tensions in key producing regions compounded inventory tightness, institutional trading desks executed a synchronized defensive rotation, reassessing corporate capital allocation strategies against a backdrop of escalating input costs.
The market action underscores a renewed anxiety among portfolio managers and corporate treasurers. For months, equity bulls had priced in a soft-landing scenario characterized by resilient consumer spending and moderating inflation. However, the sudden surge in energy commodities acts as a classic macroeconomic tax, eroding corporate operating margins, threatening infrastructure scalability, and forcing executive boards to re-evaluate their fiscal year guidance. As trading volumes spiked across major exchanges, liquidity conditions grew increasingly erratic, signaling heightened volatility heading into the final stretch of the fourth quarter.
The Catalysts Driving the October 23 Energy Surge
The immediate catalyst behind Friday’s equity pullback was an unyielding upward trajectory in international benchmark crude prices. West Texas Intermediate (WTI) and Brent futures both advanced past critical psychological resistance levels, settling at their highest marks since late spring. Market intelligence reports point to a confluence of supply-side constraints, including unexpected maintenance outages at major offshore production facilities and persistent geopolitical friction along vital maritime trade corridors.
For corporate America, the translation of these commodity spikes into operational reality is immediate and severe. Energy-intensive sectors—ranging from global logistics and freight carriers to chemical manufacturers and heavy industrial producers—saw their projected operating expenses surge. Wall Street analysts rushed to update their financial models, warning that the cascading effect of higher fuel surcharges and petrochemical feedstock costs will inevitably compress profit margins. Consequently, equity valuation multiples, particularly for companies with high capital intensity and stretched balance sheets, faced aggressive downward revisions.
Furthermore, the bond market reflected mounting apprehension. Treasury yields fluctuated as fixed-income investors weighed the inflationary implications of dearer oil. A persistent energy shock threatens to unanchor inflation expectations, complicating the Federal Reserve’s monetary policy trajectory. While central bankers have increasingly emphasized data-dependent risk mitigation, a resurgence in headline inflation driven by energy inputs severely limits the central bank’s capacity to lower interest rates further without risking wage-price spirals.
Market Metrics & Index Performance Breakdown
A closer examination of Friday’s tape reveals broad-based weakness across major indices, though cyclical and consumer-facing sectors bore the brunt of the institutional sell-off.
| Market Index / Asset | Closing Level (Oct. 23, 2026) | Daily Net Change | Key Driver / Narrative |
|---|---|---|---|
| Dow Jones Industrial Average | 42,815.40 | -385.20 (-0.89%) | Heavy industrials and energy-dependent blue chips weighed down by cost pressures. |
| S&P 500 Index | 5,810.12 | -52.40 (-0.89%) | Broad contraction led by consumer discretionary and tech valuation compression. |
| NASDAQ Composite | 18,340.50 | -198.10 (-1.07%) | High-multiple cloud and semiconductor names pressured by rising risk-free yields. |
| WTI Crude Futures | $86.40 / bbl | +$2.85 (+3.41%) | Hit 5-month highs amid supply bottlenecks and heightened Middle East geopolitical tension. |
Industry & Market Implications: Winners and Losers
The intraday shift in market sentiment is already reshaping institutional asset allocation models. As portfolio managers recalibrate their risk exposure, the divergence between sectors benefiting from commodity inflation and those penalized by it has widened dramatically.
The Beneficiaries: Energy Majors and Defensive Yields
Unsurprisingly, integrated oil and gas producers emerged as relative outperformers, buoyed by expanding free cash flow yields and robust upstream profitability. Major exploration and production firms saw steady institutional inflows as portfolio managers sought direct hedges against energy-driven inflation. Additionally, defensive sectors such as regulated utilities and essential healthcare providers attracted conservative capital seeking stable dividend yields and robust regulatory compliance frameworks insulated from cyclical commodity shocks.
The Casualties: Consumer Discretionary and Tech Infrastructure
Conversely, consumer discretionary stocks faced aggressive liquidation. Higher fuel costs directly depress consumer disposable income, dampening spending forecasts for the upcoming holiday shopping season. At the same time, high-growth technology firms—particularly those heavily reliant on expansive cloud compute architecture and data center energy consumption—faced double headwinds. Not only do rising energy costs inflate infrastructure operational expenditures, but the corresponding upward pressure on bond yields directly undermines the net present value of future corporate cash flows, triggering valuation multiple compression.
Frequently Asked Questions (People Also Ask)
Why did the Dow Jones slide specifically on October 23, 2026?
The Dow Jones Industrial Average slid primarily due to a sharp escalation in global crude oil prices, which reached five-month highs. Investors feared that rising energy costs would squeeze corporate profit margins, escalate operating expenses across multiple sectors, and reignite inflationary pressures that could force the Federal Reserve to maintain restrictive monetary policies.
How do rising oil prices impact equity valuation multiples?
Higher oil prices act as a macroeconomic tax on corporations and consumers. For businesses, increased energy inputs drive up production and logistics costs, reducing net income. When corporate earnings forecasts are revised downward, equity valuation multiples (such as Price-to-Earnings ratios) contract because investors demand a higher risk premium to hold equities in an inflationary, high-cost environment.
Which stock sectors typically outperform during an energy price shock?
Energy sector equities—including integrated oil majors, exploration and production companies, and oilfield services providers—typically outperform because higher commodity prices directly boost their revenues and free cash flow. Additionally, defensive sectors like utilities and consumer staples often show greater resilience compared to consumer discretionary and high-growth technology stocks.
What are the broader macroeconomic risks of prolonged high oil prices?
Prolonged high oil prices can stall broader economic expansion by dampening consumer spending power and elevating production costs globally. For central banks, it complicates macroeconomic management by creating stagflationary pressures—where economic growth slows while inflation remains stubbornly elevated, limiting the flexibility of monetary policy.
Future Outlook & Strategic Milestones to Watch
As Wall Street closes the books on another volatile trading week, macroeconomic strategists are urging institutional clients to maintain rigorous risk mitigation protocols. The trajectory of equities over the coming weeks will depend heavily on three critical catalysts:
- Geopolitical Developments: Any diplomatic breakthroughs or further escalations in major oil-producing regions will dictate whether crude prices consolidate near five-month highs or break out toward triple digits.
- Corporate Earnings Guidance: As Q3 earnings season progresses, market participants will scrutinize executive commentary regarding forward-looking margin protection, pricing power, and the ability to absorb higher energy input costs without destroying end-user demand.
- Macroeconomic Data Releases: Upcoming prints on the Consumer Price Index (CPI) and the Personal Consumption Expenditures (PCE) price index will provide definitive guidance on whether energy inflation is beginning to bleed into core economic metrics, shaping expectations for the Federal Reserve’s upcoming policy meetings.
In this high-stakes environment, disciplined capital allocation, rigorous balance-sheet scrutiny, and agile risk management will separate top-tier institutional portfolios from vulnerable market participants.