Executive Takeaways
- Capital Allocation Shift: A landmark $2 billion foundry pact underscores aggressive enterprise risk-mitigation and supply-chain localization strategies amid surging AI-driven data center demand.
- инструментальные Breakthroughs: Hyper-NA EUV lithography and Canon’s commercial-ready nanoimprint technology are radically altering capital intensity models and valuation multiples for leading-edge manufacturers.
- Advanced Packaging Expansion: Strategic footprints by Lam Research and ASE highlight the critical bottleneck and market liquidity shifting toward 2.5D/3D integration and CoWoS-adjacent packaging ecosystems.
- Geographic and Architectural Shifts: China’s emergence of fully automated IC design systems alongside global PCIe 7.0 standardization signals an accelerated bifurcated roadmap for high-performance computing infrastructure.
The global semiconductor ecosystem is undergoing a generational reconfiguration. As the industry digests the final week of September 2025, capital allocation strategies are shifting decisively away from speculative volume expansion toward precision infrastructure scalability, yield optimization, and technological sovereignty. Driven by the unrelenting compute requirements of generative artificial intelligence and high-frequency cloud workloads, semiconductor boardrooms are committing unprecedented capital expenditures to secure next-generation manufacturing nodes.
From a staggering $2 billion foundry alliance that redefines outsourced manufacturing dependencies to the commercialization race between Hyper-NA EUV and nanoimprint lithography, this week’s developments signal a pivotal moment for institutional investors and tech strategists alike. This comprehensive investigative report analyzes the macro-financial drivers, engineering milestones, and structural market shifts shaping the global chip landscape.
The Macro Catalysts: Capital Allocation and the $2 Billion Foundry Pivot
At the center of this week's industry developments is a landmark $2 billion foundry pact designed to shore up resilient, geographically diversified manufacturing corridors. In an era marked by geopolitical friction and regulatory compliance burdens, Tier-1 fabless designers are no longer willing to concentrate their volume risk in single-jurisdiction manufacturing hubs. This capital commitment reflects a broader industry imperative: securing guaranteed wafer allocation at sub-2nm nodes while insulating supply chains from macroeconomic shocks.
Financial disclosures from industry bellwethers Taiwan Semiconductor Manufacturing Company (TSMC) and Samsung Electronics corroborate this capital-intensive trajectory. Both foundry giants report robust financial health, propelled by high-margin AI accelerator production and resilient automotive and consumer recovery. However, the cost of maintaining technology leadership has escalated dramatically. Cleanroom build-outs, specialized gas infrastructure, and advanced lithography tools are compressing free cash flow margins in the short term, yet generating exceptional enterprise ROI for firms that successfully capture high-end enterprise workloads.
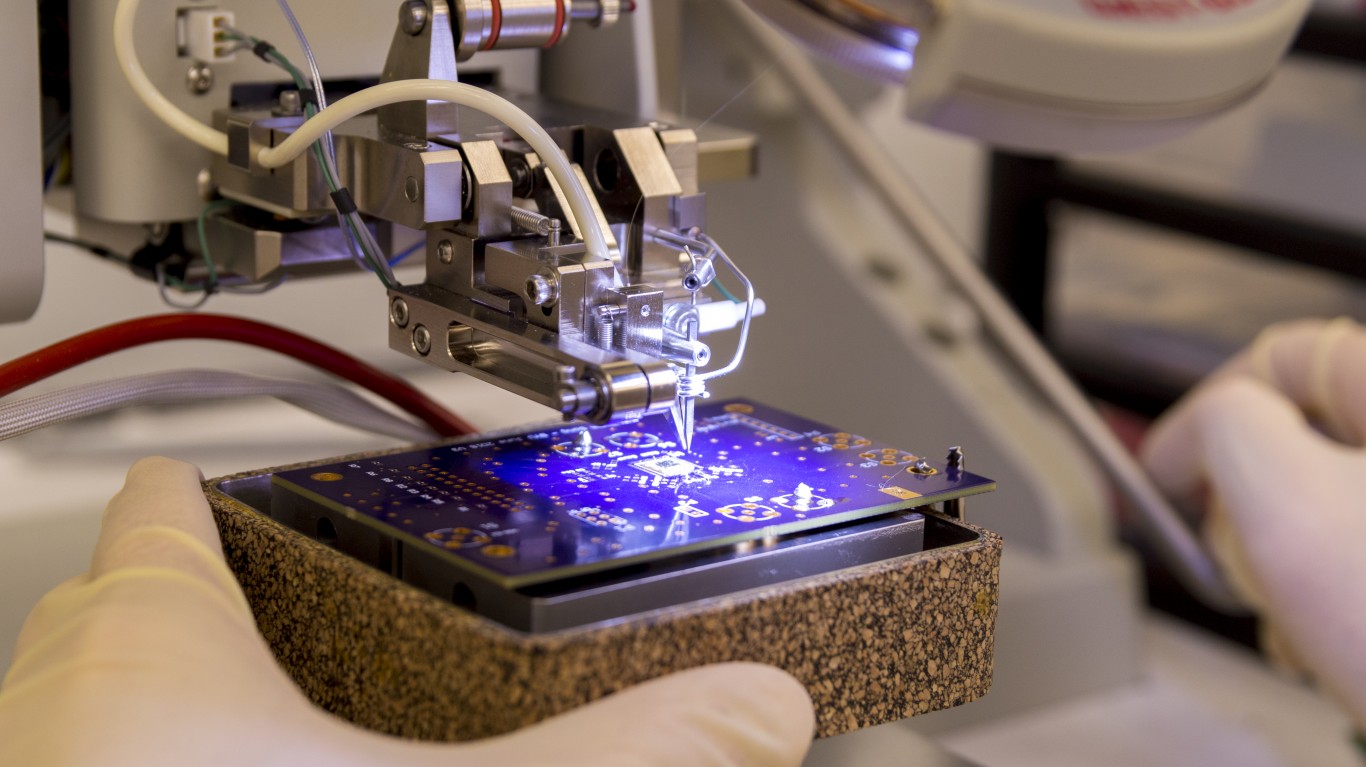
Concurrently, backend manufacturing is experiencing a renaissance. Major expansions by packaging pioneers Lam Research and ASE point directly to where the industry's toughest physics problems lie. As monolithic die scaling approaches theoretical limits, the economic value of semiconductors is migrating toward advanced packaging. CoWoS (Chip-on-Wafer-on-Substrate), hybrid bonding, and Chiplet architectures are no longer niche enterprise solutions; they are the primary determinants of yield, latency, and thermal performance in modern data center architecture.
Lithography Evolution: Hyper-NA EUV vs. Nanoimprint Breakthroughs

The manufacturing roadmap is splitting along two distinct technological axes. On one side, the industry is marching toward Extreme Ultraviolet (EUV) lithography evolution, with Hyper-NA systems dominating long-term roadmap discussions. These systems promise to push numerical apertures beyond current High-NA limits, enabling direct patterning of sub-1nm features without complex multi-patterning workarounds.
Conversely, Canon’s aggressive push into commercial-ready nanoimprint lithography (NIL) introduces a disruptive variable into traditional valuation multiples for equipment manufacturers. By mechanically stamping circuit patterns rather than projecting light through complex optical columns, nanoimprint technology offers a potentially low-cost alternative for specific memory and logic applications. While skeptics point to defect density and overlay challenges in high-volume manufacturing, the economic allure of bypassing multimillion-dollar optical scanners has captured the attention of cost-conscious fab executives seeking risk mitigation against spiraling tool amortization costs.
Data Center Architecture and Global Standards: PCIe 7.0 and Automated IC Design
Infrastructure scalability within the enterprise data center is hitting new bandwidth thresholds. The formalization and technical progression toward PCIe 7.0 underscore the insatiable demand for lower latency and higher throughput between accelerators, storage arrays, and network interface cards. Operating at blistering speeds, PCIe 7.0 requires rigorous signal integrity management, driving new innovations in retimers, active copper cables, and optical co-packaged (CPO) system architectures.
Speaking of optical integration, CPO system deployments are transitioning from academic proofs-of-concept to deployable enterprise architectures. By integrating optics directly onto the switch or processor package, data centers can circumvent the electrical bottleneck of traditional copper trace routing, drastically cutting power consumption—a critical metric for hyper-scalers facing corporate carbon-neutrality mandates and skyrocketing power bills.
Globally, the competitive landscape is diversifying. Recent global IC and AI rankings emphasize shifting regional capabilities, accentuated by reports of China deploying fully automated IC design systems. By leveraging machine learning models to handle floor-planning, placement, and routing, these automated frameworks threaten to compress chip development cycles from years to months, fundamentally altering the competitive dynamics of fabless design ecosystems.
Verified Data & Metrics Breakdown
To contextualize the scale of capital expenditure, technological transitions, and market positioning across the semiconductor supply chain, review the verified metric breakdown below:
| Metric / Initiative | Primary Stakeholders | Financial / Technical Scope | Strategic Market Implication |
|---|---|---|---|
| Foundry Strategic Pact | Tier-1 Fabless & Foundries | $2 Billion Capital Allocation | Mitigates supply chain disruption; secures sub-2nm capacity. |
| Advanced Packaging Expansions | Lam Research, ASE, TSMC | Multi-billion regional fab outlays | Relieves CoWoS bottlenecks; accelerates 3D IC adoption. |
| Next-Gen Lithography | ASML, Canon, Major Foundries | Hyper-NA EUV & Nanoimprint | Diverges tool investments; disrupts optical cost models. |
| Interconnect Standardization | PCI-SIG & Hyperscalers | PCIe 7.0 / CPO System Integration | Eliminates data center bandwidth and thermal bottlenecks. |
Industry & Market Implications: Winners and Losers
The structural transformation of the semiconductor industry inevitably produces clear economic victors and vulnerable incumbents:
- The Winners: Advanced equipment manufacturers specializing in lithography, etch, and deposition (such as ASML, Lam Research, and Applied Materials) retain strong pricing power. Furthermore, outsourced semiconductor assembly and test (OSAT) leaders like ASE capturing the packaging wave are positioned for exceptional revenue expansion.
- The Losers: Legacy fabless operations unable to absorb the surging costs of advanced node tape-outs risk marginalization. Additionally, semiconductor equipment suppliers lagging in hybrid bonding and advanced thermal management capabilities face margin erosion as customer demands shift toward integrated system-level solutions.
- Macroeconomic & Investor Impact: Semiconductors remain the core cyclical and secular growth engine for global technology portfolios. Investors must carefully evaluate capital discipline; firms balancing aggressive R&D with healthy free cash flow generation will command premium market valuations.
Frequently Asked Questions (People Also Ask)
What is the strategic significance of the $2 billion foundry pact?
The $2 billion foundry pact represents a coordinated effort between major design houses and manufacturing partners to secure dedicated production capacity at advanced nodes. It provides long-term supply visibility, mitigates geopolitical risks, and ensures predictable capital allocation for next-generation enterprise workloads.
How does Canon’s nanoimprint lithography threaten traditional EUV tools?
Nanoimprint lithography (NIL) bypasses complex optical projection systems by physically stamping circuit patterns onto wafers. If commercialized successfully at scale, it offers a drastically lower capital expenditure and operating cost profile compared to multimillion-dollar EUV scanners, particularly for specific memory and standardized logic devices.
Why are Lam Research and ASE expanding their packaging footprints?
As traditional 2D scaling slows down due to fundamental physical limits, the industry relies on 2.5D and 3D advanced packaging (like CoWoS and hybrid bonding) to combine multiple chiplets into high-performance processors. Expansions by Lam Research and ASE directly target the massive equipment and manufacturing bottlenecks in this sector.
What role do CPO systems play in modern data center architecture?
Co-Packaged Optics (CPO) integrate optical transceivers directly alongside silicon processors, replacing traditional electrical copper traces. This dramatically reduces signal attenuation, lowers latency, and cuts power consumption—addressing critical infrastructure and sustainability limits in hyperscale AI data centers.
Future Outlook and Key Milestones
As the industry looks past the current quarter, market participants must monitor several pivotal inflection points. First, the commercial deployment timelines for Hyper-NA EUV versus nanoimprint tools will dictate long-term capital expenditure efficiency across major foundries. Second, the execution of advanced packaging capacity additions by ASE and Lam Research will determine whether data center hardware can scale fast enough to meet AI compute demand without severe supply bottlenecks.
For institutional investors, semiconductor exposure requires a nuanced understanding of these technological shifts. Enterprises that successfully navigate regulatory compliance, master chiplet-based heterogeneous integration, and optimize cloud compute architecture will dominate the next decade of digital infrastructure growth.