Executive Takeaways
- Escalating Yields: The benchmark 10-year Treasury yield surged past critical resistance levels following a hotter-than-anticipated Consumer Price Index (CPI) report, triggering immediate portfolio reallocations.
- Tech Sector Compression: Nasdaq-listed mega-caps opened sharply lower as compressed valuation multiples met escalating capital costs, testing the resilience of high-growth equity portfolios.
- Fed Policy Shift: Markets are aggressively pricing out near-term Federal Reserve monetary easing, forcing institutional treasurers and asset managers to recalibrate risk mitigation frameworks.
- Capital Allocation Volatility: Corporate balance sheets with heavy debt exposure face heightened borrowing costs, compelling CFOs to prioritize liquidity preservation over aggressive enterprise expansion.
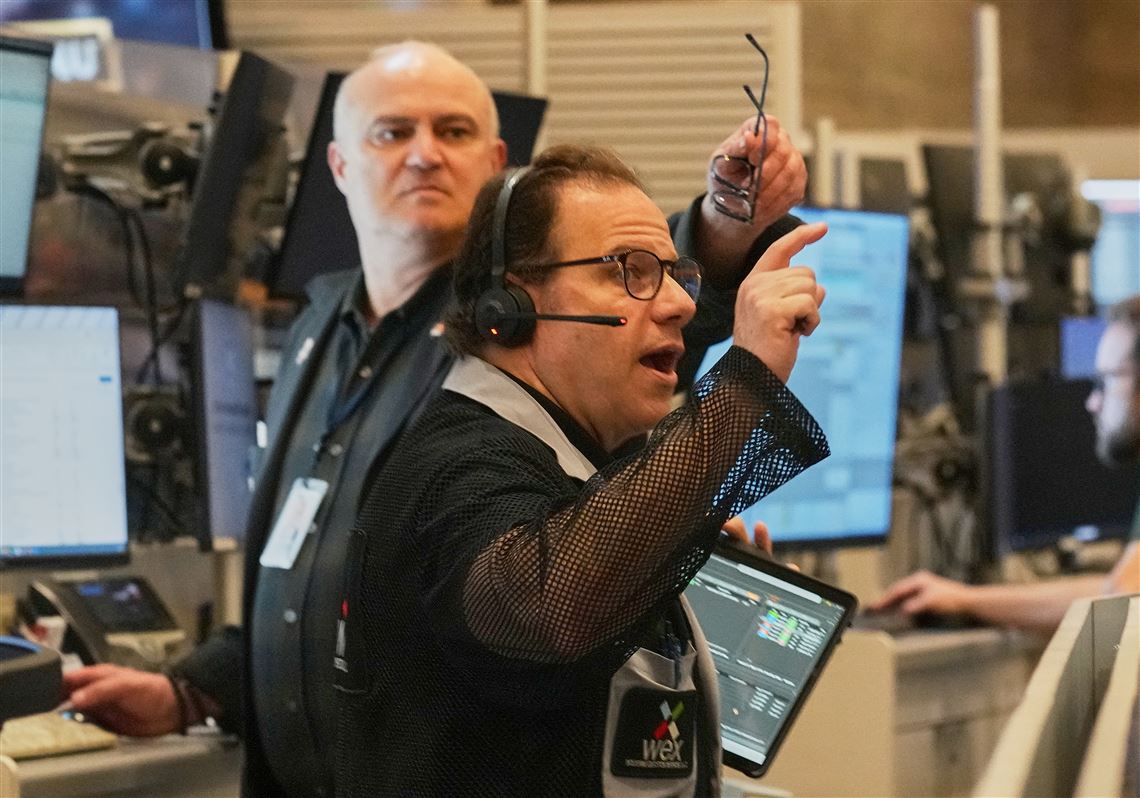
Global financial markets experienced a severe reality check this morning as macroeconomic indicators confirmed stubborn inflationary pressures. The latest Consumer Price Index (CPI) release came in above consensus estimates, invalidating the prevailing market narrative of an imminent, frictionless monetary pivot by the Federal Reserve. As bond yields climbed aggressively across the curve, risk assets faced immediate liquidation pressure. The technology-heavy Nasdaq Composite opened deeply in the red, dragging down high-multiple growth equities and sparking a broad-based repricing of risk across Wall Street.
For institutional investors, corporate executives, and wealth managers, this morning's volatility is not merely a transient data blip. It represents a structural realignment of capital costs. As fixed-income alternatives become increasingly attractive, equity risk premiums are compressing rapidly. Below is our comprehensive investigative breakdown of the macroeconomic catalysts, market mechanics, and strategic implications unfolding across global exchanges today.
The Macro Catalyst: Deconstructing the Hot CPI Print
The catalyst for today's market rout was a headline CPI print that outpaced consensus forecasts on both a monthly and annualized basis. Persistent stickiness in shelter costs, core services, and energy components underscored the structural challenges facing central bankers in their final leg of the battle against inflation. While goods deflation provided temporary relief throughout the previous two quarters, service-sector wage pressures and robust consumer demand have proven remarkably resilient.
In response to the hotter-than-expected data, federal funds futures markets underwent an immediate and violent repricing. Traders who had previously priced in aggressive monetary easing by mid-year are now rapidly unwinding those positions. The probability of a near-term rate cut has plummeted, pushing terminal rate expectations higher and forcing institutional asset allocators to abandon consensus trade models. This abrupt shift in monetary policy outlook has direct consequences for enterprise valuation multiples, which are highly sensitive to the discount rates applied to future cash flows.
Fixed Income Shock: Yields Break Out as Liquidity Reallocates

The fixed-income market bore the immediate brunt of the macroeconomic data release. Sovereign debt yields surged across the curve, with the benchmark 10-year U.S. Treasury yield punching through key technical thresholds that had held firm for weeks. Short-term yields, which are most directly tethered to the Federal Reserve's benchmark policy rate, also spiked as traders recalibrated terminal rate risks.
This rapid ascent in yields is triggering a massive re-allocation of capital out of equities and into fixed income. Institutional portfolio managers, constrained by mandates and risk-mitigation guidelines, are locking in attractive, risk-free yields in short-duration Treasuries and investment-grade corporate paper. This migration of capital is draining liquidity from risk-on asset classes, exacerbating the downward pressure on technology stocks and speculative growth sectors.
For corporate finance divisions, the implications of this yield surge are profound. Debt capital markets are effectively pricing in higher coupons for upcoming debt issuances. Companies with upcoming debt maturities or variable-rate credit facilities face escalating debt-service costs, which will directly impact net margins and force a rigorous re-evaluation of corporate capital allocation strategies.
Equities Under Siege: Nasdaq Opens Lower as Multiples Contract
The Nasdaq Composite bore the heaviest losses at the opening bell, reflecting the severe vulnerability of growth-oriented equities to rising discount rates. Companies characterized by high research and development spend, deferred profitability, and lofty valuation multiples experienced sharp downside revisions. In a high-yield environment, the present value of distant cash flows diminishes significantly, prompting algorithmic and discretionary sellers to reduce exposure.
Mega-cap technology leaders—often viewed as market barometers—saw early-session declines as institutional investors trimmed concentrated positions. However, the sell-off extended far beyond the headline tech giants. Small-cap indexes, highly reliant on short-term bank financing and floating-rate debt, also traded lower as credit conditions tightened. Sector rotation into defensive stalwarts such as utilities, healthcare, and consumer staples offered isolated pockets of stability, though overall market breadth remained decidedly negative.
Market Metrics & Economic Indicators Breakdown
The following data table outlines the key macroeconomic metrics, benchmark yields, and equity index movements driving today's market session:
| Indicator / Asset Class | Prior Reading / Close | Current Print / Level | Market Impact & Implication |
|---|---|---|---|
| Headline CPI (YoY) | 3.1% | 3.5% (Hotter than expected) | Invalidates Fed pivot narrative; drives bond sell-off. |
| U.S. 10-Year Treasury Yield | 4.32% | 4.58% (+26 bps) | Raises borrowing costs; compresses equity valuations. |
| Nasdaq Composite Opening | 16,280 | Down 1.8% in early trade | Severe multiple contraction in tech and growth sectors. |
| Fed Rate Cut Probability (June) | ~65% | Sub-35% | Aggressive repricing of monetary easing expectations. |
Industry & Market Implications: Winners and Losers
Market dislocations of this magnitude invariably create distinct bifurcations between corporate winners and losers. Understanding these structural shifts is essential for institutional investors navigating current volatility.
- The Losers: High-Multiple Growth & Leveraged Corporates. Technology firms, venture-backed startups, and companies with heavy short-term debt loads face intense headwinds. Enterprises relying on continuous debt refinancing or aggressive infrastructure scalability must now contend with dramatically higher cost-of-capital hurdles. Cloud compute architecture providers and enterprise SaaS firms may see slower IT budget growth as corporate clients tighten discretionary spending.
- The Winners: Net-Interest-Margin Banks & Fixed-Income Investors. Financial institutions with strong deposit moats and high cash reserves benefit from elevated lending rates. Furthermore, institutional asset managers and private wealth platforms offering high-yield fixed-income products are experiencing robust capital inflows as investors secure risk-free yield. Energy majors also find underlying support as persistent inflation metrics frequently correlate with commodity resilience.
Frequently Asked Questions (People Also Answer)
Why did stock markets open sharply lower following the inflation report?
Stock markets opened lower because the Consumer Price Index (CPI) came in hotter than economists anticipated. This persistent inflation reading forces the Federal Reserve to maintain higher interest rates for a longer duration. Higher interest rates increase borrowing costs for businesses and consumers, while raising the discount rate used to value future corporate earnings, which directly compresses equity valuation multiples—especially in the technology sector.
How do rising Treasury yields impact technology stocks?
Rising Treasury yields provide investors with an attractive, risk-free return on government debt, reducing the relative appeal of riskier equities. Furthermore, tech stocks are typically valued based on their projected future cash flows. When yields rise, the present value of those future earnings shrinks significantly under higher discount models, prompting institutional investors to sell high-multiple growth shares.
What does a "hot inflation reading" mean for upcoming Federal Reserve rate cuts?
A hot inflation reading signals that price stability has not yet been securely achieved within the parameters mandated by the central bank. Consequently, it drastically reduces the probability of near-term interest rate cuts. Futures markets quickly price out anticipated easing cycles, forcing investors and corporate treasurers to operate in a "higher-for-longer" interest rate environment.
How should corporate executives and CFOs respond to current market conditions?
In a high-rate, volatile inflationary environment, CFOs must prioritize balance sheet fortification, rigorous risk mitigation, and disciplined capital allocation. This includes locking in fixed-rate debt where possible, optimizing operational efficiency, deferring non-essential capital expenditures, and ensuring robust liquidity reserves to navigate potential macroeconomic softening.
Future Outlook: Strategic Milestones to Watch
As the market digests today's inflation print, attention turns rapidly toward upcoming macroeconomic data releases and central bank communications. Key milestones for institutional observers over the coming weeks include:
- Producer Price Index (PPI) and Retail Sales: Subsequent data releases will confirm whether wholesale price pressures are filtering downstream to retail consumers, providing further clarity on consumer resilience.
- Federal Reserve FOMC Minutes & Speeches: Market participants will parse upcoming commentary from regional Fed presidents and board governors for any shifts in policy stance or consensus regarding terminal rate projections.
- Corporate Q1 Earnings Season: As major financial institutions and multinational corporations kick off earnings reports, executive guidance regarding margin protection, pricing power, and capital expenditure adjustments will dictate near-term market direction.
Ultimately, today's market reaction serves as a powerful reminder that monetary normalization is rarely linear. As asset allocators re-evaluate risk models and enterprise leaders adapt to tighter credit conditions, financial market volatility is likely to remain elevated in the near term.