Executive Takeaways
- Unprecedented Capital Allocation: Alphabet has dramatically increased its 2026 capital expenditure (capex) forecast to a staggering $205 billion, vastly outpacing consensus Wall Street expectations.
- Infrastructure Scalability Over Short-Term Margins: The aggressive cash burn highlights Google's desperate race to secure proprietary cloud compute architecture, custom Tensor Processing Units (TPUs), and next-generation data center real estate.
- Enterprise ROI Under Scrutiny: As hardware and energy expenditures balloon, institutional investors are increasingly demanding clear paths to monetization and measurable enterprise efficiency gains.
- Market Liquidity & Valuation Multiples: The massive outlays risk compressing near-term free cash flow, forcing a profound reassessment of valuation multiples across the broader mega-cap technology index.
SAN FRANCISCO — In the high-stakes theater of generative artificial intelligence, the ante has just been raised to astronomical levels. Alphabet Inc., Google’s parent company, has sent shockwaves through global financial markets by revising its 2026 capital expenditure forecast upward to an astonishing $205 billion. For months, institutional asset managers, equity research analysts, and venture capitalists had debated the terminal velocity of Big Tech's infrastructure spending. Yet, this new baseline shatters previous projections, cementing an era of capital deployment unseen since the buildout of the transcontinental railroads or the dot-com-era fiber-optic grid.
As chief technology officers and financial pundits digest the numbers, the overarching question remains: Is Google engineering a masterstroke of monopolistic infrastructure foresight, or is it sliding down a slippery slope of diminishing marginal returns in a hyper-competitive arms race?
The Catalyst: Why Google Is Accelerating Its Cash Burn
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the mechanics behind this unprecedented financial pivot, one must examine the shifting sands of enterprise AI adoption and cloud compute architecture. Throughout late 2024 and 2025, the bottleneck in artificial intelligence shifted away from algorithmic breakthrough toward raw silicon availability, electrical grid interconnects, and advanced cooling systems. Alphabet’s executive leadership, spearheaded by CEO Sundar Pichai and Chief Financial Officer Anat Ashkenazi, recognized that future market dominance belongs strictly to those who control the physical supply chain of intelligence.
Google’s aggressive posture is driven by three intersecting realities:
- The Demand for Low-Latency Inference: As consumer-facing applications like Gemini and enterprise-grade APIs scale to billions of daily queries, standard cloud compute architectures prove inadequate. Real-time reasoning requires localized, hyper-dense clusters of accelerated hardware.
- Silicon Independence: Beyond reliance on traditional merchant silicon, Google is aggressively manufacturing and deploying its custom-designed Tensor Processing Units (TPUs) alongside leading-edge GPUs, insulating itself partially from external supply shocks while commanding immense upfront fabrication costs.
- Defensive Moat Building: With fierce rivalry from Microsoft-backed OpenAI, Amazon Web Services (AWS), and nimble open-source ecosystems, stalling infrastructure expansion is viewed internally as an existential threat to search dominance and cloud market share.
Yet, this relentless expansion without a localized breakdown in execution comes with a severe ledger penalty. Wall Street, accustomed to the disciplined capital allocation models of the post-pandemic correction, is now forced to re-model risk mitigation strategies and recalculate discounted cash flow (DCF) valuations across the board.
Deconstructing the Numbers: A Financial and Operational Overview

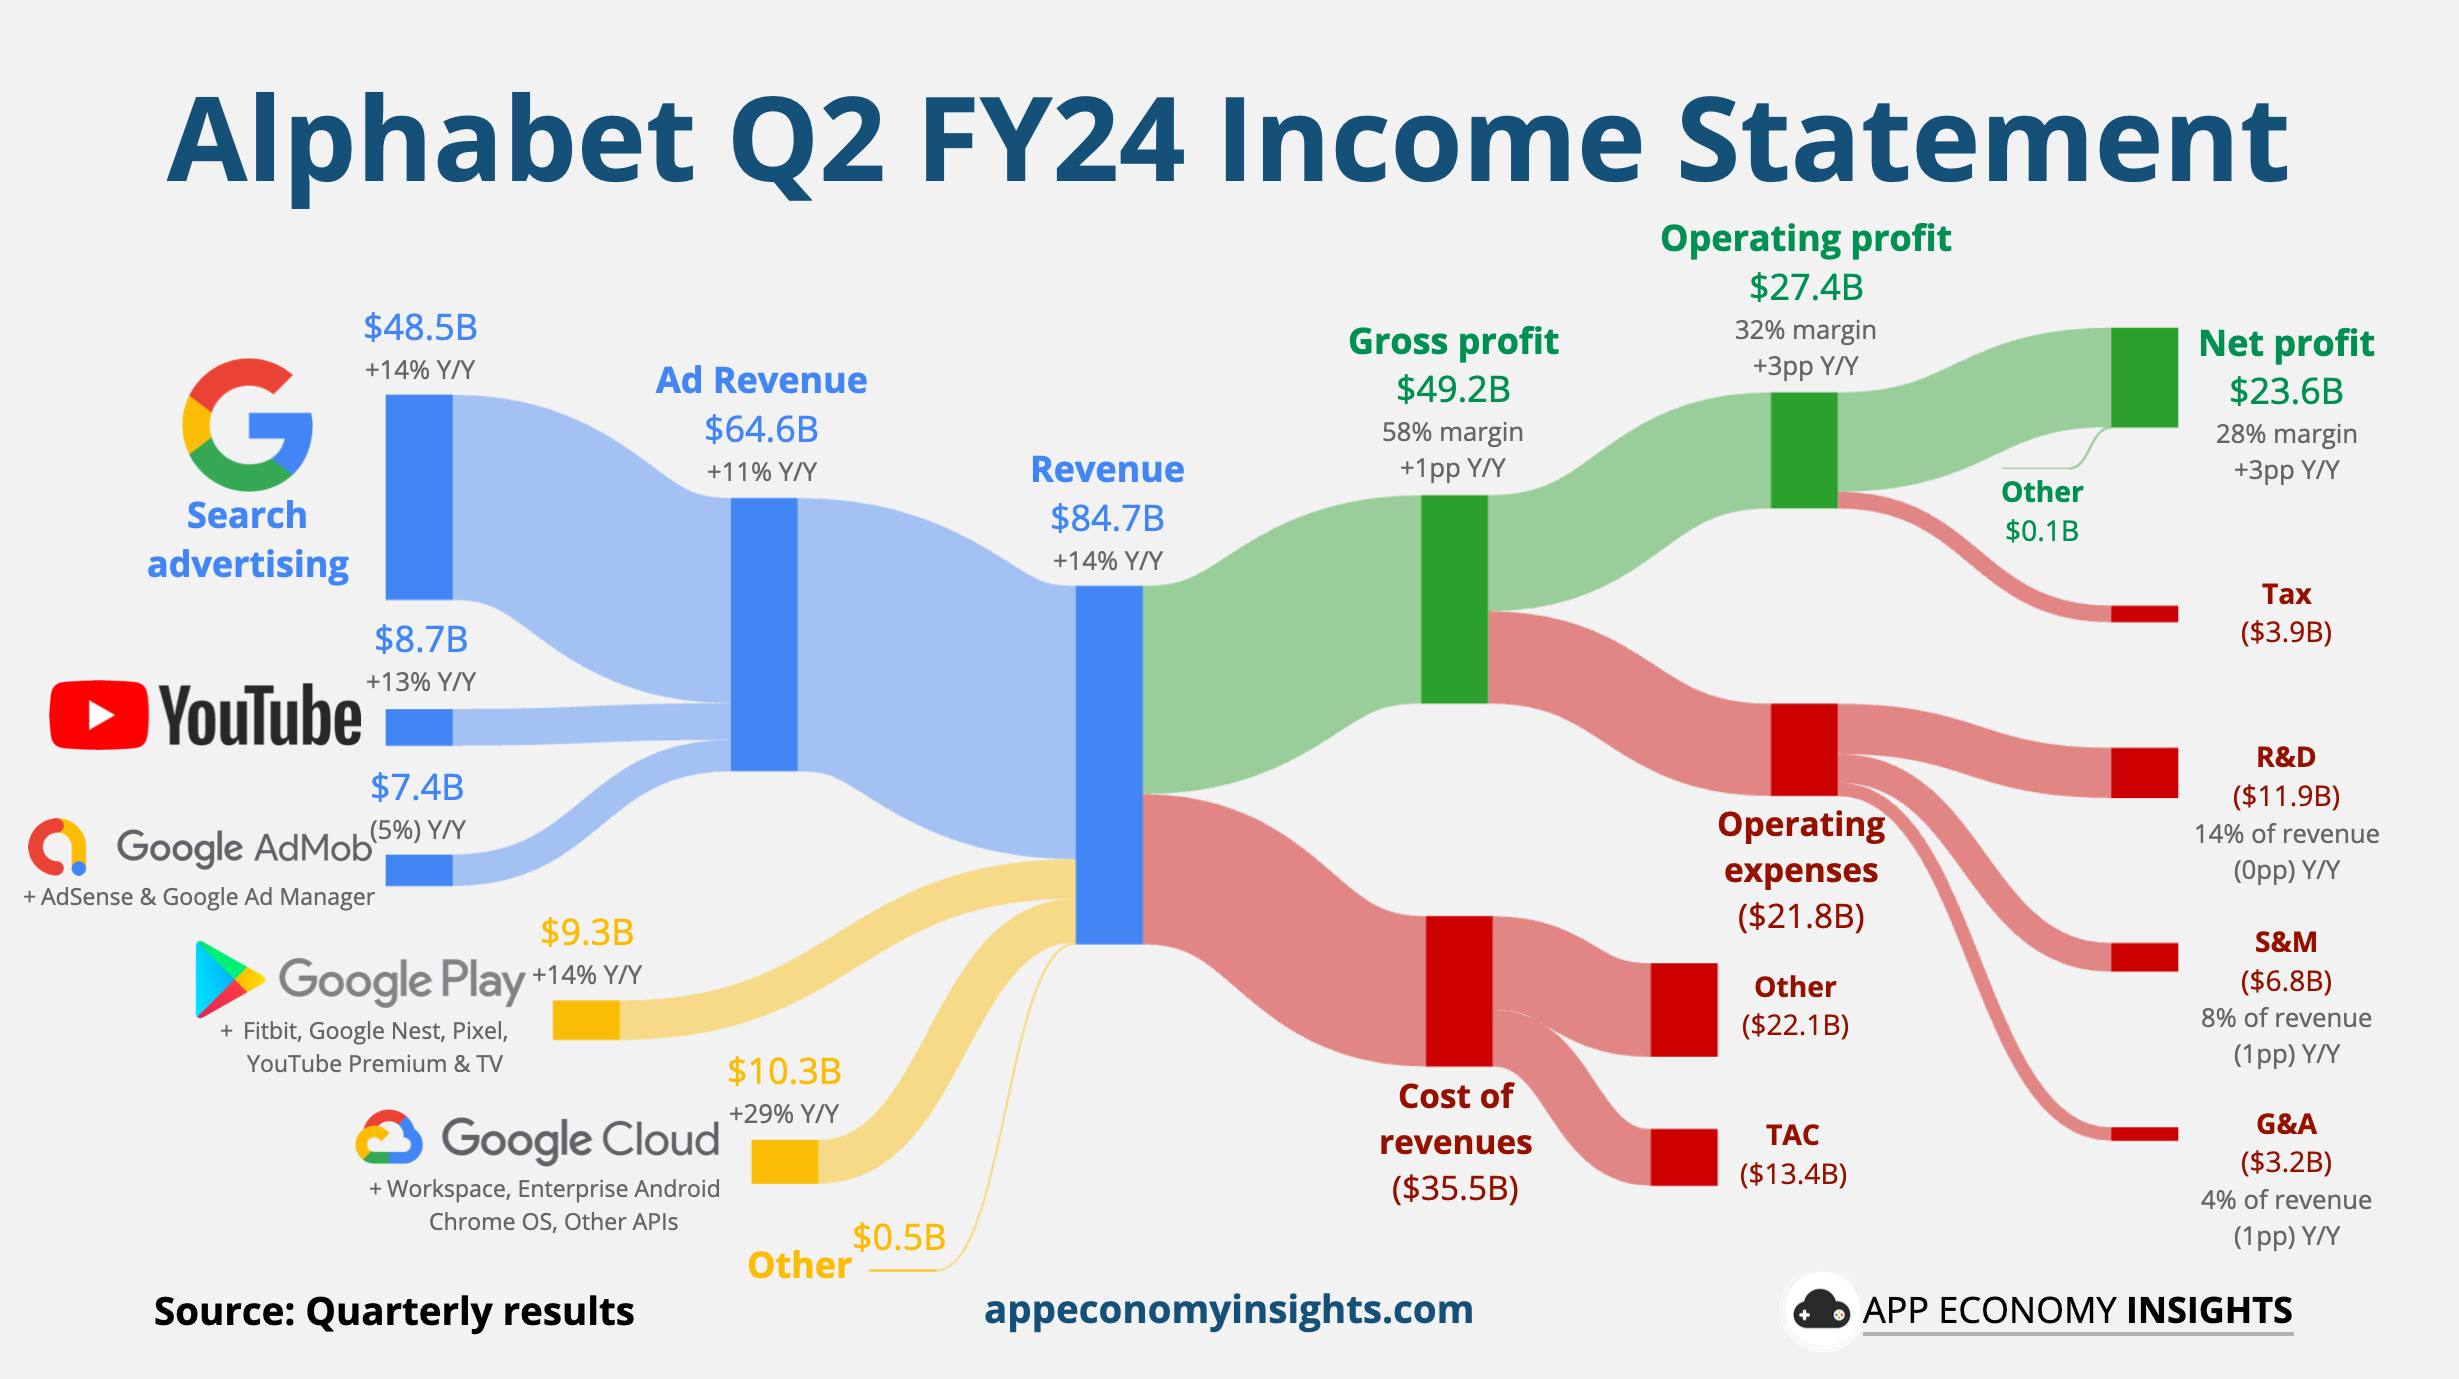
The sheer magnitude of a $205 billion annual capex budget defies historical precedent for a software and services conglomerate. To contextualize this outlay, it rivals the annual GDP of small-to-midsize sovereign nations and exceeds the total capital expenditures of entire traditional industrial sectors combined.
| Metric / Indicator | Previous Consensus | Revised 2026 Projection | Strategic Impact |
|---|---|---|---|
| Annual Capital Expenditure | $140B – $160B | Up to $205 Billion | Intensifies cash burn; compresses near-term free cash flow yields. |
| Data Center Power Capacity | Incremental scaling | Gigawatt-scale greenfield sites | Drives long-term power purchase agreements (PPAs), including nuclear and renewables. |
| Hardware Procurement | Balanced merchant silicon | Massive TPU & GPU clusters | Secures hardware sovereignty against global semiconductor supply bottlenecks. |
| Depreciation Headwinds | Moderate amortization | Accelerated depreciation cycles | Puts structural pressure on operating margins over the next 36 to 48 months. |
Industry & Market Implications: Winners and Loses in the AI Supercycle
The ripple effects of Google’s capital expenditure escalation extend far beyond Mountain View, altering competitive dynamics across global financial markets and technology ecosystems.
The Winners: Infrastructure, Energy, and Semiconductor Enablers
While Alphabet shareholders absorb short-term valuation multiple contractions, a distinct cohort of industrial and technological suppliers stands to reap historic windfalls. Semiconductor foundries, advanced packaging specialists, networking equipment manufacturers, and specialized cooling vendors are primary beneficiaries. Furthermore, because next-generation AI data centers demand unprecedented electrical loads, energy conglomerates—particularly those pioneering modular nuclear reactors and stable renewable grids—are finding unprecedented long-term enterprise contracting opportunities with Google.
The Losers: Near-Term Margin Purists and Smaller Competitors
On the opposing side, institutional investors who prize pristine operating margins and predictable free cash flow generation are rotating away from mega-cap tech assets. Furthermore, venture-backed startups and mid-tier cloud providers face an increasingly insurmountable barrier to entry. When a single player can deploy $205 billion in a single fiscal year purely on infrastructure, the capital barrier required to train frontier foundational models becomes an impenetrable moat.
Frequently Asked Questions (People Also Ask)
Why is Google increasing its 2026 capital expenditure to $205 billion?
Google is aggressively expanding its infrastructure footprint to secure long-term leadership in artificial intelligence. This includes scaling proprietary cloud compute architecture, building gigawatt-capacity data centers, procuring next-generation AI silicon (including custom TPUs and advanced GPUs), and securing dedicated clean energy sources to power intensive machine-learning workloads.
How does this massive spending impact Google's financial health and stock valuation?
While this level of capital allocation signals immense confidence in long-term AI monetization, it places near-term pressure on free cash flow and operating margins due to accelerated depreciation and high upfront cash burn. Wall Street analysts are currently re-evaluating valuation multiples, weighing long-term enterprise ROI potential against short-term margin compression.
What are the primary bottlenecks Google faces with this capital rollout?
The primary constraints facing Google are not purely financial, but physical. Securing electrical grid interconnects, sourcing adequate cooling infrastructure, and managing semiconductor supply chain logistics remain critical hurdles in translating capital commitments into operational data center capacity.
Future Outlook: Critical Milestones to Watch
As the market digests Google’s historic capital pivot, attention pivots immediately to execution. Over the next four to eight quarters, financial analysts will scrutinize three core performance indicators to validate whether this $205 billion bet is generating appropriate enterprise ROI:
- Cloud Revenue Acceleration: Google Cloud must demonstrate that its specialized AI infrastructure translates directly into accelerating top-line cloud growth, outperforming competing offerings from Microsoft Azure and Amazon Web Services.
- Monetization of Core Products: Clear evidence that generative AI features integrated into Search, Workspace, and Android are driving measurable incremental ad revenue and high-margin subscription models rather than merely inflating serving costs.
- Power and Facility Operationalization: The speed at which planned greenfield data centers transition from blueprint to active compute nodes, avoiding regulatory delays or electrical grid bottlenecks.
Ultimately, Google’s willingness to sacrifice short-term margin purity for absolute infrastructure supremacy is a defining gamble of the modern corporate era. Whether this bold expenditure cements a generational technological monopoly or serves as a cautionary tale of overzealous capital allocation will define the trajectory of global technology markets for the next decade.