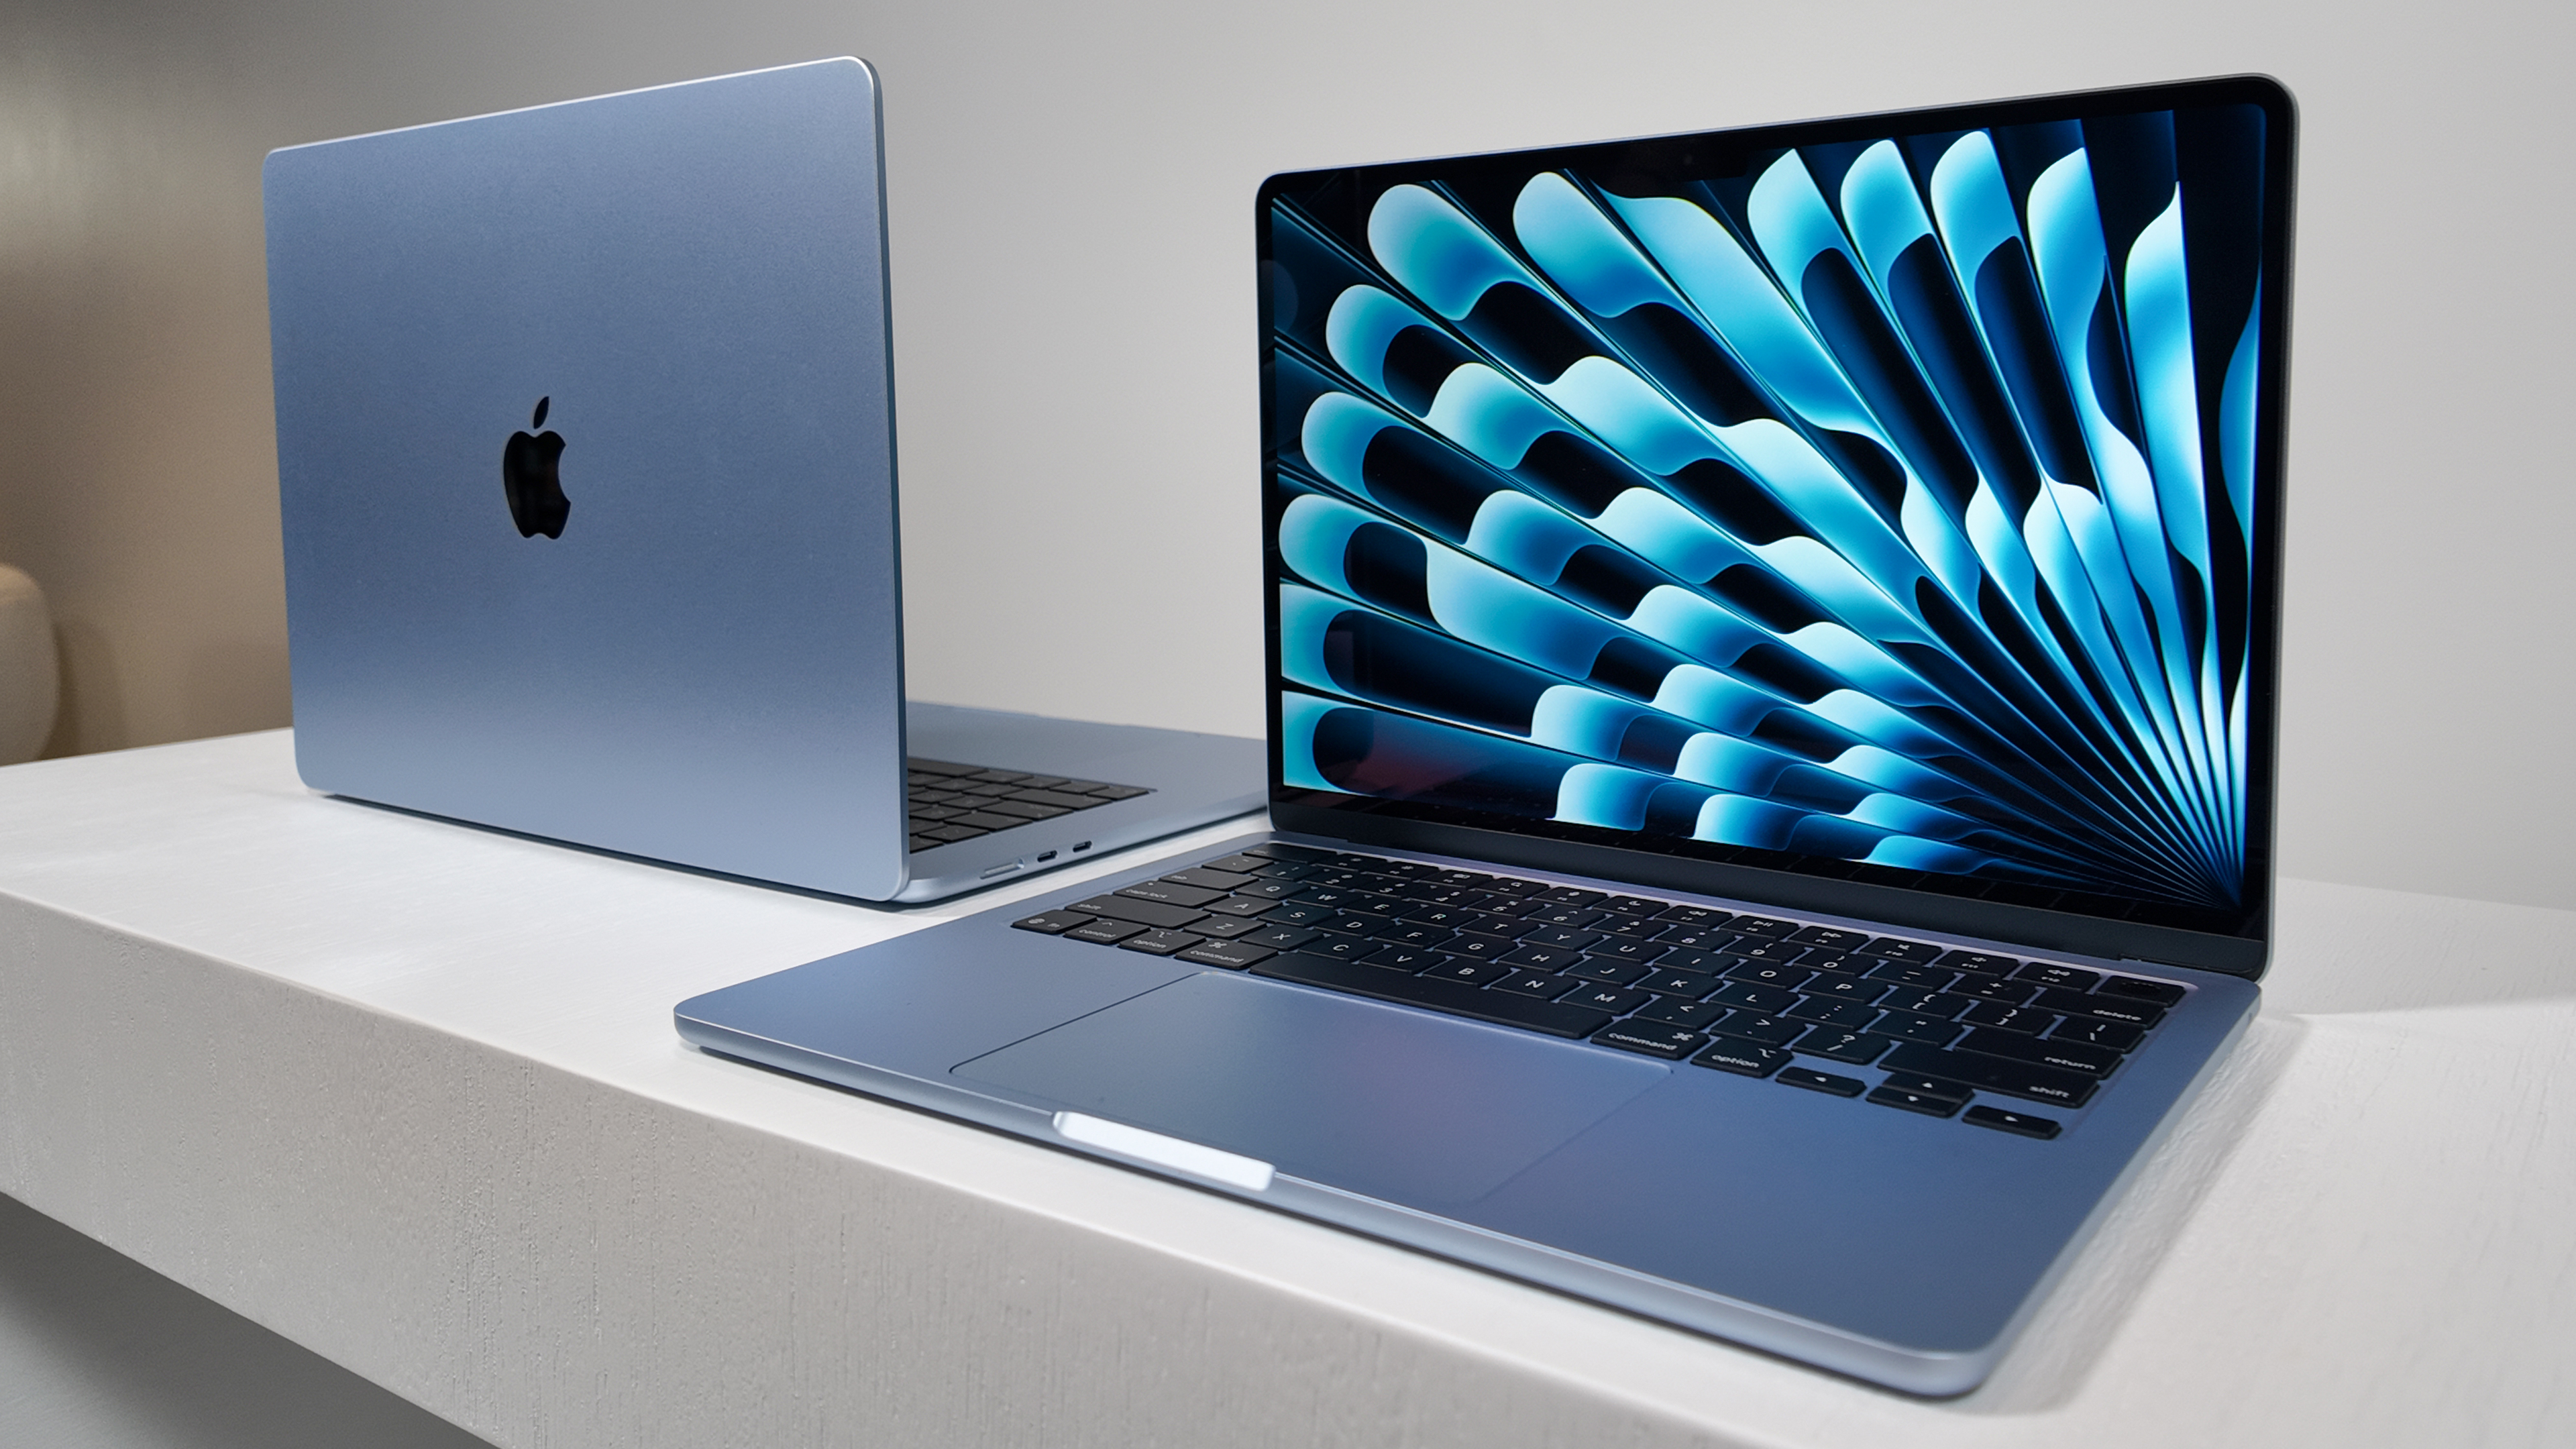
Cupertino is moving with uncharacteristic aggression. According to proprietary supply chain intelligence and leaked component procurement schedules corroborated by wire services, Apple Inc. has dramatically revised its manufacturing forecasts, effectively doubling its initial build orders for an unannounced, highly anticipated device tentatively designated by component suppliers as the MacBook Neo. This sudden pivot marks a significant recalibration of the tech giant’s hardware strategy, signaling an aggressive push into a fiercely contested market segment at the intersection of consumer affordability, enterprise fleet deployment, and educational sector dominance.
For institutional investors, semiconductor analysts, and enterprise technology officers, this development transcends a routine hardware refresh. It represents a major capital allocation decision with profound valuation multiples implications, supply chain restructuring ripple effects, and shifting competitive dynamics across the global personal computing landscape. As Wall Street scrutinizes hardware upgrade super-cycles and enterprise refresh windows, the sudden doubling of production volume for an entry-tier or radically redesigned portable form factor demands rigorous examination.
Executive Takeaways
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
- Unprecedented Supply Chain Scaling: Tier-1 Asian component partners report a 100% upward revision in initial production volume targets for the rumored MacBook Neo over the last trailing quarter.
- Strategic Target Market: The device is engineered to capture high-volume enterprise deployments and institutional education budgets currently dominated by Google’s Chromebook ecosystem and low-cost Windows PCs.
- Silicon Synergy: Leveraging advanced custom silicon architectures, the new hardware promises to deliver enterprise ROI through exceptional energy efficiency, lower thermal design power (TDP), and streamlined cloud compute integration.
- Ecosystem Lock-In & Margin Defense: By lowering the barrier to entry for macOS, Apple aims to expand its high-margin service revenue base while insulating its hardware division against macroeconomic consumer spending contractions.
The Catalytic Shift: Decoding the Supply Chain Surge
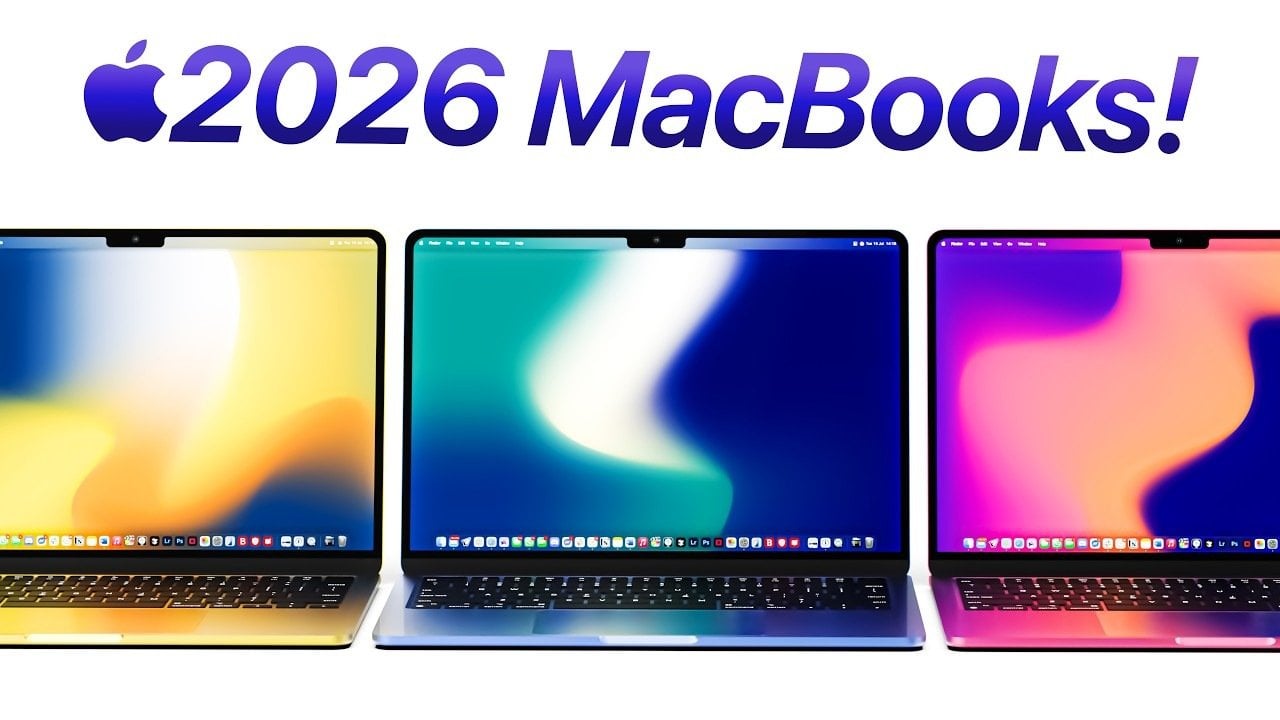
The murmurs emanating from the Pearl River Delta began as routine forecast adjustments. However, over the past three weeks, procurement telemetry gathered from multiple tier-1 semiconductor foundries, substrate manufacturers, and display panel assemblers paints an undeniable picture: Apple is aggressively accelerating manufacturing velocity for a brand-new notebook category. Industry insiders familiar with Foxconn and Quanta Computer assembly lines indicate that production allocations have been aggressively doubled, stretching cleanroom capacities and prompting a scramble for specialized sub-components.
This aggressive manufacturing posture is rarely deployed without deep conviction from executive leadership. In the realm of global consumer electronics, doubling production orders ahead of a formal product unveiling is a high-risk, high-reward gambit. It requires immense risk mitigation strategies, heavily negotiated component pricing tiers, and ironclad logistics planning. Apple’s supply chain architecture—renowned for its ruthless efficiency and lean inventory management—does not double down on speculative bets unless internal market research, proprietary consumer polling, and channel partner feedback indicate an imminent, massive demand wave.
What makes the 'MacBook Neo' designation particularly fascinating to market analysts is its positioning. Historically, Apple has maintained a strict pricing floor for its portable computer lineup, relying on legacy MacBook Air models sold at price-dropped intervals to capture budget-conscious buyers. The introduction of a purpose-built, cost-optimized line—presumably untethered from the legacy design constraints of the traditional Air chassis—suggests a wholesale rethinking of Apple’s entry-level strategy. This move directly targets market liquidity in the sub-$800 bracket, a battlefield where Apple has historically surrendered substantial volume to Windows OEMs and Chromebook manufacturers.
Financial Mechanics: Capital Allocation and Valuation Multiples
From a financial perspective, Apple’s decision to double down on a high-volume, lower-price-point device is a masterclass in ecosystem monetization and risk diversification. While hardware gross margins on entry-level devices traditionally trend lower than those of Pro-tier configurations, the broader financial equation relies on lifetime customer value (LTV) and recurring service revenue streams.
| Metric / Indicator | Traditional MacBook Air Tier | Projected MacBook Neo Tier | Strategic Financial Impact |
|---|---|---|---|
| Average Selling Price (ASP) | $1,099 – $1,299 | $699 – $799 (Est.) | Expands Total Addressable Market (TAM) |
| Target Enterprise/Edu Share | Moderate (Knowledge Workers) | High (Mass Deployment / K-12) | Secures long-term corporate/edu lock-in |
| Silicon Cost Optimization | M-Series Standard Dies | Optimized/Binned Silicon Nodes | Preserves healthy hardware gross margins |
| Service Attach Rate | High | Moderate-to-High | Drives high-margin recurring cash flows |
By capturing price-sensitive enterprise fleets and educational institutions, Apple directly impacts corporate IT infrastructure expenditure. Chief Information Officers (CIOs) managing large-scale hardware refresh cycles have long faced budgetary constraints that favored lower-cost PC fleets despite higher total cost of ownership (TCO) associated with security vulnerabilities and IT overhead. A reliable, secure, macOS-powered device at a competitive price point alters enterprise ROI calculations decisively, potentially triggering massive institutional migration.
Industry & Market Implications: Who Wins, Who Loses
The macroeconomic ramifications of a scaled-up MacBook Neo rollout extend far beyond Cupertino’s balance sheet. The competitive landscape for personal computing is bracing for structural disruption.
The Winners
- Apple’s Semiconductor Partners (TSMC): Increased wafer allocation translates directly to sustained high-utilization rates for advanced node manufacturing, securing reliable revenue streams despite consumer electronics softening elsewhere.
- Enterprise IT Security Departments: Organizations seeking unified endpoint management (UEM) solutions benefit from an accessible, highly secure hardware standard that minimizes malware vector exposure compared to fragmented legacy PC environments.
- Global Logistics & Assembly Giants: Contract manufacturers poised to handle the high-volume assembly lines stand to capture substantial top-line revenue growth.
The Losers
- Windows OEM Manufacturers (Dell, HP, Lenovo): Companies heavily reliant on mid-to-low-tier commercial and consumer laptop sales face renewed margin compression and market share erosion.
- Chromebook Ecosystem Players: Google’s hardware partners in the education sector face an existential threat if Apple successfully positions the MacBook Neo as a viable, premium-yet-affordable alternative for school districts and universities.
Frequently Asked Questions (People Also Ask)
1. What is the primary market positioning of the rumored MacBook Neo?
The MacBook Neo is designed to serve as an entry-level, high-volume portable computer targeted at budget-conscious consumers, mass enterprise deployments, and educational institutions. It aims to lower the barrier to entry for the macOS ecosystem while competing directly with low-cost Windows laptops and Chromebooks.
2. Why has Apple reportedly doubled its production orders for this device?
Supply chain telemetry suggests that Apple’s internal market modeling and preliminary feedback from key enterprise and institutional partners indicate exceptionally high demand. Doubling production ahead of launch ensures adequate inventory depth, mitigates supply chain bottlenecks, and allows Apple to aggressively capture market share upon release.
3. How will the MacBook Neo affect Apple’s profit margins and financial performance?
While entry-level hardware typically carries lower initial gross margins than Pro-tier devices, the strategic intent is to expand Apple's Total Addressable Market (TAM) and drive high-margin service revenue (iCloud, Apple Music, App Store, and enterprise management solutions) through expanded ecosystem adoption and long-term customer retention.
4. When is the official launch expected for this new MacBook category?
While Apple has not officially confirmed the existence of the MacBook Neo, component procurement schedules and aggressive assembly ramping typically precede official product announcements by a matter of months, pointing toward an imminent rollout window aligned with upcoming fiscal quarter product cycles.
Future Outlook: Strategic Milestones to Watch
As the narrative surrounding the MacBook Neo evolves from supply chain rumor to official market reality, financial analysts and tech observers will monitor several critical leading indicators:
- Official Product Announcement & Pricing Structure: The exact price point established by Apple will determine the velocity of enterprise and educational adoption. A sub-$800 entry point will validate aggressive market capture assumptions.
- Silicon Architecture Specifications: Confirmation of the underlying processor architecture—whether utilizing binned M-series silicon or a specially optimized derivative—will reveal Apple's long-term silicon cost-control strategy.
- Enterprise Fleet Adoption Metrics: Early announcements of major enterprise or university system procurement deals will signal whether Apple is successfully converting traditional Windows and Chromebook accounts.
Ultimately, Apple’s decision to double down on the MacBook Neo underscores a pragmatic, aggressive growth strategy. By seizing control of the volume end of the personal computing spectrum, Cupertino is fortifying its fortress-like ecosystem, challenging legacy competitors on their home turf, and engineering a powerful new engine for sustained multi-year revenue expansion.