Executive Takeaways
- Capital Allocation Shift: Global semiconductor giants including Micron Technology, Infineon Technologies, and India’s diversified Tata Group have unveiled accelerated operational timelines and infrastructure scalability plans at Semicon India 2026.
- De-risking global supply chains and capturing high-margin South Asian enterprise demand have catalyzed billions in foreign direct investment, fundamentally reshaping capital allocation strategies across the Indo-Pacific tech corridor.
- State-level incentives, combined with aggressive federal subsidies under the modified Semicon India program, are shrinking operational breakeven timelines and driving aggressive valuation multiples for domestic ecosystem suppliers.
- Despite robust infrastructure scalability and robust government backing, acute talent shortages in advanced packaging, cleanroom engineering, and lithography maintenance pose near-term operational risk mitigation challenges.
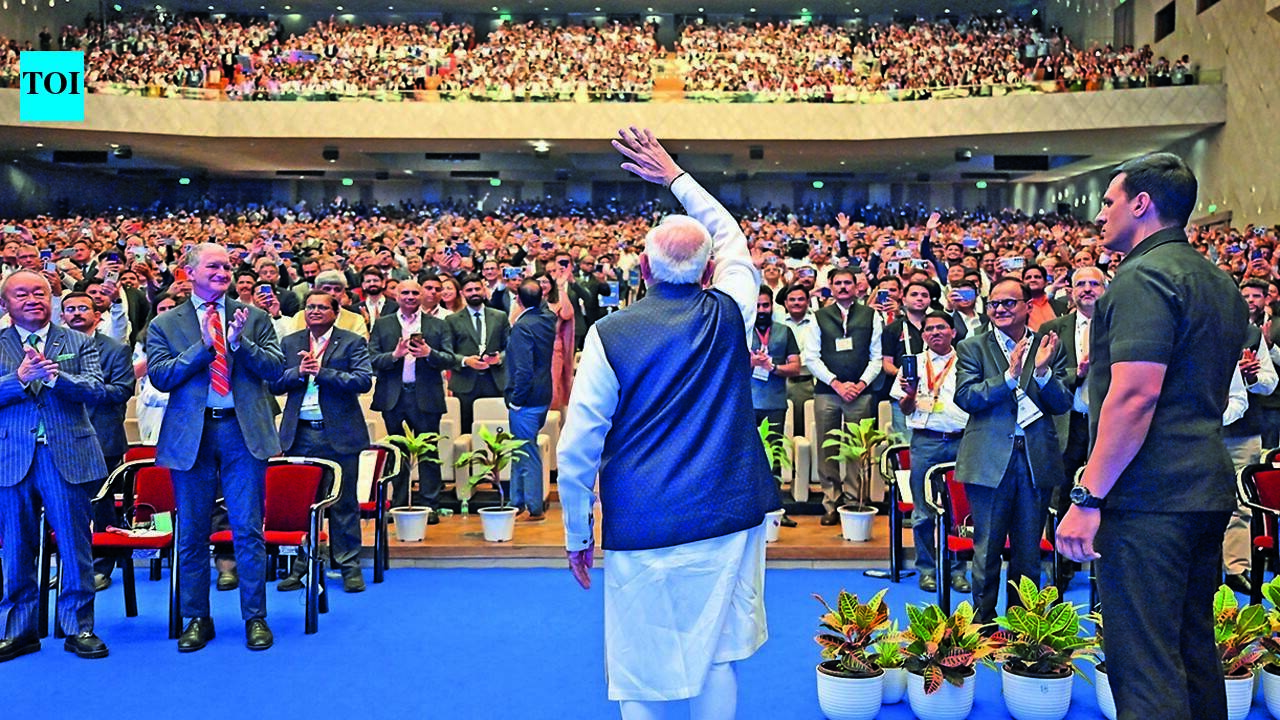
NEW DELHI and GANDHINAGAR — Against a backdrop of shifting geopolitical alliances and escalating enterprise demand for resilient supply chain architecture, the curtains have risen on Semicon India 2026. For institutional investors, sovereign wealth funds, and enterprise technology leaders, this year’s summit is not merely a ceremonial showcase; it represents the definitive transition of the subcontinent from an aspirational silicon frontier into an operational cornerstone of global semiconductor manufacturing.
During high-stakes keynote addresses and closed-door roundtable sessions four weeks ago, C-suite executives from Micron Technology, Tata Electronics, and Infineon Technologies outlined their next-generation expansion roadmaps. These announcements signal a structural maturation of India’s nascent semiconductor ecosystem. By fusing Western and Asian semiconductor intellectual property with domestic capital liquidity and aggressive state-level support, these titans are laying the groundwork for a multi-decade transformation of enterprise ROI and regional manufacturing footprints.
The Catalytic Shift: Moving from Memorandum to Mass Production
The narrative surrounding India’s semiconductor ambitions has evolved dramatically over the past 36 months. Initial skepticism from international analysts—born of past industrial policy missteps and infrastructure bottlenecks—has been systematically dismantled by concrete capital expenditure (CapEx) execution. Micron’s $2.75 billion assembly, test, marking, and packaging (ATMP) facility in Sanand, Gujarat, has transitioned from blueprint to structural reality, serving as the vanguard for foreign direct investment in the region.
At Semicon India 2026, Micron leadership detailed the acceleration of phase-two deployment metrics. The initial facility, designed to integrate cutting-edge dynamic random-access memory (DRAM) and NAND flash memory packaging, is scaling its cloud compute architecture and cleanroom automation ahead of schedule. Crucially, Micron’s integration into the local industrial base has triggered a gravitational pull for auxiliary component manufacturers, chemical suppliers, and precision tooling vendors.
Simultaneously, the Tata Group—acting through Tata Electronics—cemented its position as India’s premier domestic silicon champion. Having broken ground on its flagship semiconductor fab in Dholera, Gujarat, in partnership with Taiwan’s Powerchip Semiconductor Manufacturing Corp (PSMC), Tata executives utilized the 2026 summit to outline aggressive capacity targets. The conglomerate’s multi-billion-dollar capital allocation strategy is engineered to capture surging demand across automotive, consumer electronics, and industrial automation sectors.
Infineon Technologies, a global leader in power semiconductors and automotive microcontrollers, also used the platform to articulate its localized expansion strategy. Recognizing the explosive growth of electric vehicles (EVs) and renewable energy infrastructure across South Asia, Infineon is deepening its engineering footprint and supply chain integration within India. The German chipmaker’s roadmap focuses heavily on silicon carbide (SiC) and gallium nitride (GaN) technologies, aligning perfectly with India’s aggressive decarbonization and net-zero industrial mandates.
Verified Data & Metrics Breakdown Table

| Company / Entity | Project Focus & Technology Node | Estimated CapEx (USD) | Primary Operational Milestone |
|---|---|---|---|
| Micron Technology | ATMP (Assembly, Test, Marking, Packaging) for DRAM/NAND | $2.75 Billion | Phase-2 scaling & high-volume commercial output by late 2026 |
| Tata Electronics (with PSMC) | Logic Foundry (28nm to mature nodes) in Dholera, Gujarat | $11 Billion+ | Structural construction completion & tool-in phases accelerating |
| Infineon Technologies | Power Semiconductors, Automotive ICs, SiC/GaN integration | Undisclosed Strategic Direct Investment | Ecosystem partnerships & R&D engineering hub expansion |
Industry & Market Implications: Winners, Losers, and Economic Realities
The strategic roadmaps laid out at Semicon India 2026 carry profound macroeconomic and corporate valuation consequences. As global enterprises grapple with structural vulnerabilities exposed by historical supply chain shocks, geographic diversification has transformed from a corporate social responsibility talking point into an absolute board-level imperative.
Who Wins?
Domestic Engineering Talent and Specialized Universities: The acute demand for domestic semiconductor engineers, materials scientists, and cleanroom technicians has driven compensation packages higher, sparking a massive influx of specialized curriculum development across Indian Institutes of Technology (IITs).
Industrial Real Estate and Infrastructure Developers: Gujarat and neighboring states are experiencing an unprecedented boom in industrial park development, logistics corridors, and high-capacity power grid upgrades designed to support ultra-reliable cleanroom environments.
Global Equipment and Material Providers (ASML, Applied Materials, Tokyo Electron): As new fabs break ground and existing facilities scale, equipment makers secure lucrative, recurring service contracts and machinery orders.
Who Loses?
Traditional single-source manufacturing hubs that fail to offer competitive regulatory compliance incentives or robust infrastructure scalability are steadily losing marginal market share. Furthermore, legacy electronic system design and manufacturing (ESDM) players that rely entirely on imported un-packaged silicon face compressed margins as localized ecosystems mature and offer superior tax advantages and logistical efficiencies.
Frequently Asked Questions (People Also Ask)
What was the primary focus of Semicon India 2026?
Semicon India 2026 centered on the execution phase of India's semiconductor mission. Rather than securing initial memorandums of understanding, industry leaders like Micron, Tata, and Infineon focused on concrete capital deployment timelines, supply chain localization, advanced packaging scaling, and infrastructure readiness.
How much is Micron investing in its Gujarat facility?
Micron Technology is committing approximately $2.75 billion toward its state-of-the-art Assembly, Test, Marking, and Packaging (ATMP) facility located in Sanand, Gujarat, with active expansions targeting advanced memory packaging to meet global enterprise demand.
What role does the Tata Group play in India’s semiconductor push?
Through Tata Electronics, the conglomerate is spearheading India's entry into logic foundry manufacturing. In partnership with Taiwan's Powerchip Semiconductor Manufacturing Corp (PSMC), Tata is constructing a multi-billion-dollar fabrication plant in Dholera, Gujarat, aimed at producing mature and specialized nodes for automotive and consumer markets.
What are the primary risk mitigation challenges facing India's chip expansion?
Key hurdles include mitigating potential talent shortages in advanced lithography and cleanroom engineering, ensuring uninterrupted ultra-pure water and high-voltage power supplies, and navigating complex regulatory compliance frameworks across federal and state jurisdictions.
Future Outlook: Milestones and Market Trajectory
As Semicon India 2026 recedes into the rearview, attention shifts immediately to execution velocity. For institutional investors monitoring the sector, the next 12 to 18 months will be defined by three critical inflection points: the successful tool-in and first-silicon rollouts from major fabrication sites, the speed at which domestic auxiliary supply chains reach commercial density, and the efficacy of government-backed workforce development initiatives.
Ultimately, India’s semiconductor trajectory is no longer a question of if, but how fast. With multinational balance sheets aligned with sovereign industrial policy, the nation is steadily cementing its status as an indispensable pillar of the twenty-first-century digital economy.