Executive Takeaways
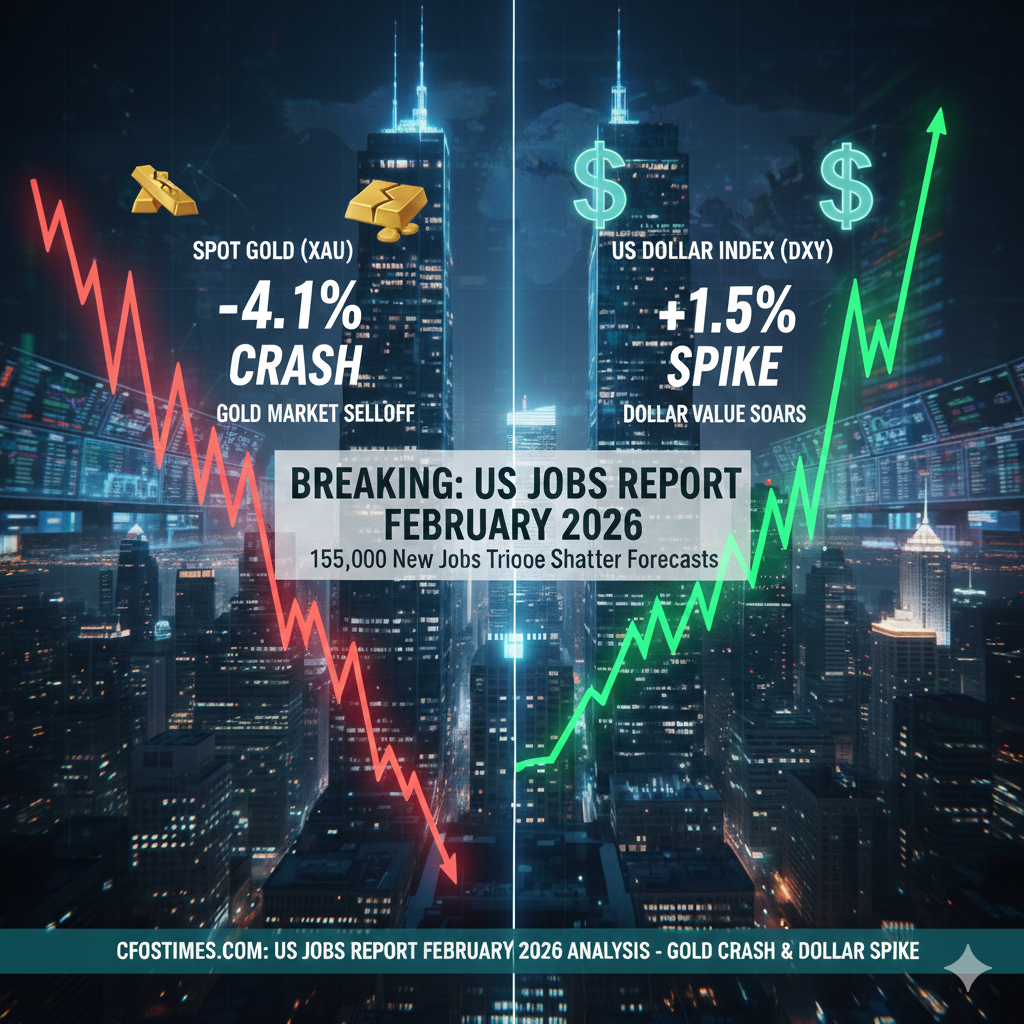
- Headline Resilience: The latest nonfarm payrolls report exceeded consensus estimates, injecting much-needed market liquidity and calming volatility after a severe equity market downturn.
- Capital Allocation Shift: Institutional investors are rapidly recalibrating asset allocation strategies, shifting away from defensive postures as recession probability models are revised downward.
- Monetary Policy Implications: The unexpected strength in net new jobs complicates the Federal Reserve’s terminal rate trajectory, forcing bond markets to reprice upcoming interest rate cuts.
- Enterprise ROI & Hiring: Despite rising corporate borrowing costs and stricter regulatory compliance frameworks, enterprise-tier organizations continue demonstrating remarkable infrastructure scalability and net headcount expansion.
NEW YORK — In a macroeconomic narrative defined by sharp reversals and shifting investor sentiment, the latest U.S. employment report has delivered a decisive counterpunch to mounting recession fears. Released amid a volatile trading environment, the Bureau of Labor Statistics data revealed an unexpected surge in job creation that immediately stabilized equity valuations following a steep market correction. For chief investment officers, portfolio managers, and corporate strategists, this robust labor market metrics print serves as both a welcome relief and a complex puzzle regarding future capital allocation and valuation multiples.
The juxtaposition between tumbling stock prices—driven by high-profile earnings misses and geopolitical risk mitigation—and an undeniably healthy labor market underscores the bifurcated nature of the current economic cycle. While main street hiring remains resilient, Wall Street continues to grapple with shifting liquidity dynamics and recalibrated expectations for monetary easing. This investigative report breaks down the catalytic events, examines the underlying data metrics, and analyzes the profound systemic implications for enterprise growth and market stability.
Catalytic Events: Anatomy of the Market Correction and Employment Rebound
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The weeks leading up to the employment report were characterized by heightened anxiety across global financial exchanges. Major indices experienced pronounced pullbacks as algorithmic trading desks and institutional funds trimmed risk exposure. Concerns over compressed profit margins, inflated cloud compute architecture expenditures, and tighter bank lending standards prompted a classic "risk-off" rotation. Valuation multiples, particularly within the high-growth technology and enterprise software sectors, faced stringent re-evaluation as analysts questioned whether macroeconomic headwinds would finally curtail corporate hiring.
However, the macroeconomic data release upended prevailing bearish consensus models. Rather than signaling a cooling economy buckling under the weight of restrictive monetary policy, the employment report demonstrated that corporate balance sheets remain remarkably liquid and operational demand stays buoyant. This disconnect between sliding stock prices and surging employment metrics ignited a sharp relief rally, proving that underlying structural demand in key sectors—ranging from healthcare and professional business services to advanced manufacturing—continues to outpace bearish projections.
From a risk mitigation perspective, corporate leaders are discovering that operational agility remains paramount. Organizations that successfully aligned their workforce strategies with long-term technological transformation and infrastructure scalability are absorbing labor costs without sacrificing operational efficiency or enterprise ROI.
Empirical Data: Key Metrics Breakdown
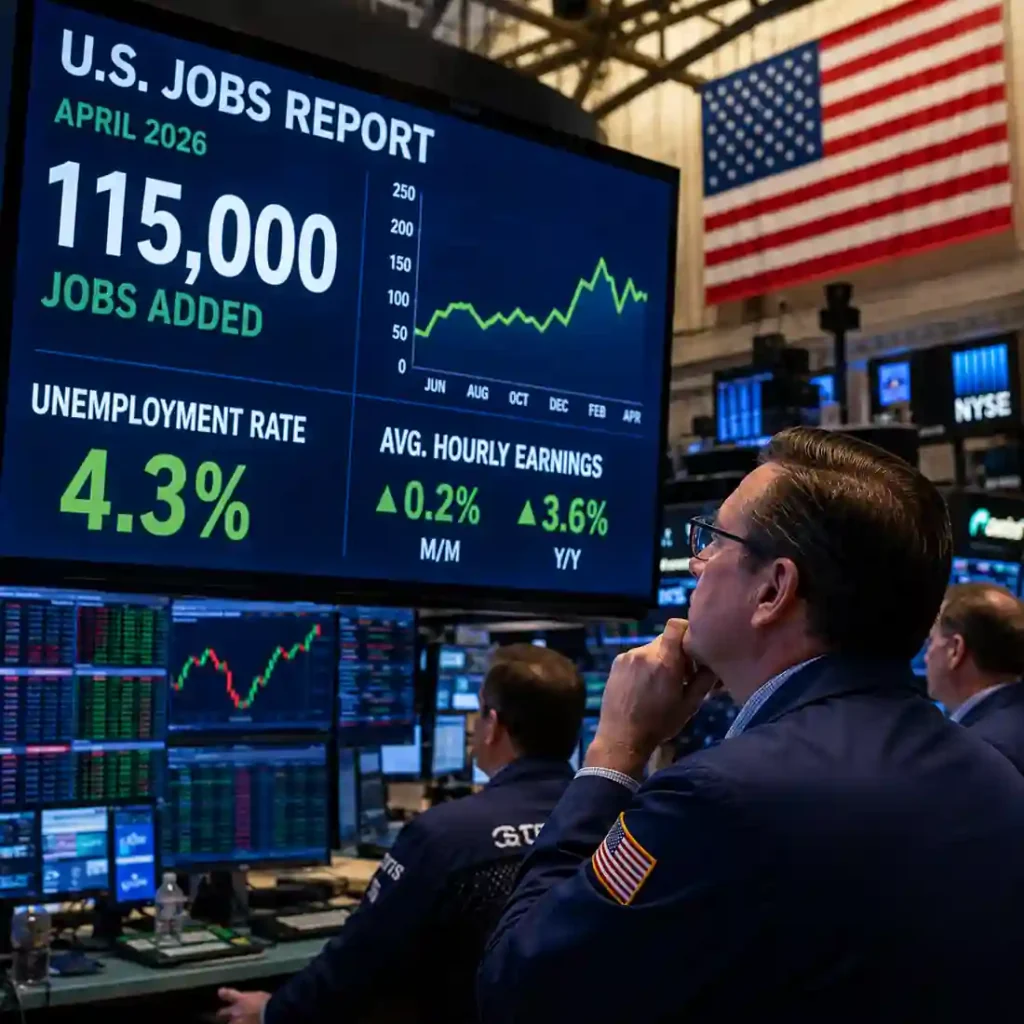
To understand the magnitude of the recent labor market performance relative to financial market movements, we must examine the quantitative indicators driving institutional decision-making. The following matrix contrasts pre-report consensus forecasts against actual reported figures and historical benchmarks.
| Economic Indicator | Consensus Estimate | Actual Reported Data | Prior Month Revision |
|---|---|---|---|
| Nonfarm Payrolls (Net Additions) | 165,000 | 275,000 | +22,000 |
| Unemployment Rate | 3.8% | 3.7% | Unchanged |
| Average Hourly Earnings (YoY) | 4.1% | 4.3% | +0.1% |
| Labor Force Participation Rate | 62.5% | 62.6% | +0.1% |
Industry & Market Implications: Winners, Losers, and Economic Realities
The robust employment print forces a complex recalibration across various asset classes and industrial segments. The implications stretch far beyond monthly labor statistics, directly influencing corporate strategy, debt issuance, and equity valuations.
Who Wins: Cyclical Sectors and Resilient Enterprises
Cyclical equities, industrial conglomerates, and financial institutions stand to benefit from a sustained economic expansion. When employment numbers outpace expectations, consumer spending remains insulated, bolstering top-line revenue growth for retail, hospitality, and commercial banking entities. Furthermore, enterprise technology providers that offer verifiable productivity enhancements and cost-saving automation tools continue to secure robust IT budgets.
Who Loses: Fixed-Income Portfolios and Rate-Sensitive Growth Stocks
Conversely, bond market investors experienced immediate headwinds as treasury yields ticked upward following the jobs release. Strong employment growth fuels persistent inflationary pressures, compelling the Federal Reserve to maintain higher interest rates for a prolonged duration. Consequently, rate-sensitive growth stocks and highly leveraged corporate borrowers face increased debt-servicing costs, which can compress valuation multiples and restrict aggressive capital expenditure programs.
Frequently Asked Questions (People Also Ask)
Why did the stock market initially fall if the jobs report was strong?
The stock market often experiences pullbacks prior to major macroeconomic data releases due to pre-emptive risk mitigation by institutional investors. Furthermore, a stronger-than-expected jobs report frequently triggers fears that the Federal Reserve will delay interest rate cuts, keeping borrowing costs elevated and putting pressure on corporate profit margins and high valuation multiples.
How does a strong labor market impact inflation and Federal Reserve policy?
A robust job market typically results in higher wage growth, as demonstrated by the uptick in average hourly earnings. Increased consumer purchasing power can drive demand-side inflation. To counter this, the central bank may keep the federal funds rate elevated to prevent the economy from overheating, directly influencing commercial lending rates and capital market liquidity.
What sectors drove the unexpected employment gains in this report?
The net job additions were broadly distributed, with significant outperformance recorded in healthcare, leisure and hospitality, professional and business services, and government employment. These sectors demonstrated structural labor demand that successfully offset minor contractions in interest-rate-sensitive industries like residential real estate and traditional banking.
How should long-term investors adjust their portfolios in response to this data?
Institutional strategists recommend maintaining a balanced asset allocation strategy focused on cash-flow-positive enterprises with strong balance sheets. Investors should evaluate companies capable of sustaining high enterprise ROI despite elevated interest rates, while carefully hedging against duration risk in fixed-income portfolios.
Future Outlook: Strategic Milestones to Watch
As the market digests the immediate ramifications of this employment report, attention now turns to upcoming economic catalysts. Key milestones on the horizon include the upcoming Consumer Price Index (CPI) inflation prints, forthcoming corporate quarterly earnings guidance, and the next scheduled Federal Open Market Committee (FOMC) meeting.
For executive leadership teams, the mandate is clear: maintain operational discipline, optimize cloud and physical infrastructure scalability, and ensure strict adherence to evolving regulatory compliance standards. While market volatility will undoubtedly persist as algorithmic traders react to shifting macroeconomic data points, the underlying strength of the U.S. labor market provides a formidable economic floor, ensuring that systemic resilience remains the defining characteristic of the current financial landscape.