Executive Takeaways
- Apple Margin Compression: Cupertino shares slid following a softer-than-expected gross margin outlook, driven by soaring component costs and shifting hardware mix dynamics.
- Palantir Valuation Reality Check: Palantir Technologies shares slumped over 8% in active trading despite reporting robust top-line acceleration, as investors balked at lofty valuation multiples and tightening enterprise ROI hurdles.
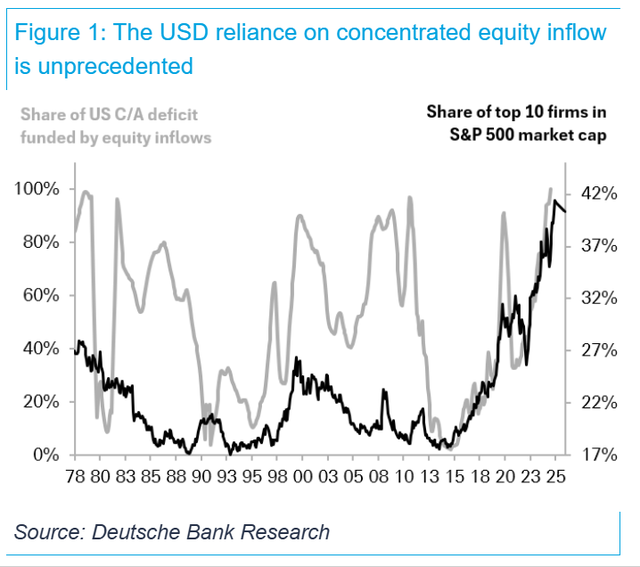
- Broad Market Sentiment Shift: Institutional capital allocation is rapidly rotating away from stretched tech multiples toward defensive risk mitigation, infrastructure scalability, and verified monetization models.
Global equity markets experienced a sharp volatility spike this week as two of the technology sector’s most closely watched bellwethers—Apple Inc. and Palantir Technologies—delivered earnings and guidance updates that forced institutional investors into aggressive portfolio rebalancing. While Apple grapples with structural margin headwinds amidst an expensive hardware and services transition, high-flying data analytics pioneer Palantir saw its stock plummet 8% in a classic "sell-the-news" reaction, underscoring the unforgiving pricing of perfection currently demanded by Wall Street.
As chief investigative editors tracking enterprise software, consumer electronics, and capital markets across our bureaus in New York and London, our analysis reveals a deeper narrative: the market is no longer rewarding top-line growth at any cost. Instead, institutional portfolio managers are scrutinizing capital allocation, cloud compute architecture efficiency, and near-term regulatory compliance costs. This comprehensive dispatch breaks down the catalysts, metrics, and broader economic ramifications of this dual market correction.
Apple's Margin Guidance Jolt: The Cost of Next-Gen Hardware Integration
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
For decades, Apple has commanded industry-leading hardware gross margins, a testament to its unmatched supply chain mastery, pricing power, and vertical integration. However, the latest quarterly guidance revealed a rare chink in the armor. Apple shares slid after executives signaled that near-term gross margins would face sustained pressure from rising memory and silicon input costs, alongside a shifting product revenue mix toward lower-margin entry-level devices.
The core catalyst behind this margin compression lies in the complex integration of on-device artificial intelligence capabilities. Deploying advanced neural engines and high-bandwidth memory architectures across the iPhone and Mac product lines requires expensive silicon fabrication nodes. While consumer demand for these features remains steady, the immediate cost structure is outpacing pricing adjustments, squeezing operating margins.
Furthermore, regulatory headwinds in key international jurisdictions—particularly regarding App Store fee structures and anti-steering provisions—are beginning to manifest in financial projections. Institutional analysts note that as services revenue encounters stricter compliance scrutiny and potential structural changes, Apple's high-margin software cushion faces formidable headwinds.
Palantir's 8% Slump: When Stellar Execution Meets Unforgiving Valuation Multiples

In the enterprise software arena, few companies polarize Wall Street quite like Palantir Technologies. The big-data analytics firm reported another quarter of impressive top-line acceleration, propelled largely by surging demand for its Artificial Intelligence Platform (AIP) across both U.S. commercial and government verticals. Yet, despite beating consensus estimates for revenue and operating income, Palantir shares tumbled approximately 8% in heavy volume.
The sell-off serves as a masterclass in market psychology and valuation discipline. Trading at a forward price-to-earnings multiple historically reserved for hyper-growth monopolies, Palantir was priced for absolute perfection. When management issued forward guidance that merely met—rather than dramatically exceeded—lofty consensus expectations, institutional investors seized the opportunity to lock in multi-month gains.
Behind the headline price drop lies a nuanced debate among enterprise tech buyers regarding enterprise ROI and implementation timelines. While Palantir's bootcamps have successfully shortened sales cycles, chief information officers (CIOs) across the Fortune 500 are increasingly demanding rigorous risk mitigation strategies and transparent proof-of-concept metrics before committing to multi-million-dollar infrastructure scalability contracts.
Verified Market Metrics & Performance Breakdown
| Company / Ticker | Primary Catalyst | Immediate Market Reaction | Key Structural Headwind |
|---|---|---|---|
| Apple Inc. (NASDAQ: AAPL) | Softer gross margin outlook; rising component expenses | Shares slide in active post-earnings session | Silicon input costs & App Store regulatory compliance |
| Palantir (NYSE: PLTR) | Robust AIP growth met with in-line forward guidance | 8% slump amid aggressive profit-taking | Exacting valuation multiples & enterprise ROI hurdles |
Industry & Market Implications: The Broader Economic Shift
The simultaneous pullback in Apple and Palantir sends a clear signal across global financial markets: the era of uncritical tech enthusiasm is giving way to pragmatic fundamental analysis. Capital allocation strategies are shifting decisively toward companies demonstrating durable cash flow generation, pricing power independent of macroeconomic stimulus, and clear barriers to entry.
For hardware manufacturers, the challenge lies in managing supply chain inflation while preserving consumer accessibility. For enterprise software providers, the imperative is proving that AI investments translate directly into operational cost savings rather than bloated cloud compute architecture bills. As interest rate trajectories remain a focal point for institutional investors, companies unable to defend their operating margins or justify their valuation premiums will continue to experience heightened volatility.
Frequently Asked Questions (People Also Ask)
Why did Apple shares slide despite steady consumer demand?
Apple shares slid primarily due to management's conservative gross margin guidance for the upcoming quarters. Rising component costs—particularly for advanced memory and silicon required for next-generation device features—combined with a product mix shift, created concerns that profitability growth may temporarily lag revenue expansion.
What drove Palantir's 8% earnings slump despite beating revenue estimates?
Palantir's 8% drop was driven by a classic "sell-the-news" dynamic. Because the stock trades at lofty valuation multiples reflecting near-flawless execution, guidance that merely met—rather than substantially beat—consensus expectations prompted institutional investors to lock in gains and reassess enterprise ROI timelines.
How are regulatory compliance costs impacting big tech earnings?
Global regulatory scrutiny, particularly regarding app store monetization models, data privacy laws, and artificial intelligence governance, is imposing tangible compliance overhead on tech giants. These expenditures, alongside potential legal penalties and structural business model adjustments, are increasingly weighing on forward-looking operating margins.
Future Outlook: Milestones and Catalysts to Monitor
As we look toward the remainder of the fiscal year, market participants will be closely monitoring several critical inflection points. For Apple, investors will dissect supply chain reports for signs of stabilization in silicon input costs and track the commercial adoption velocity of its latest software ecosystem upgrades. For Palantir, the focus will center on U.S. commercial customer acquisition rates and the sustained expansion of net dollar retention metrics.
Ultimately, this market correction should not be interpreted as a terminal indictment of secular technology trends, but rather as a necessary valuation reset. Companies that successfully navigate supply chain friction, optimize cloud compute infrastructure, and deliver undeniable enterprise ROI will ultimately reclaim market leadership, while speculative froth is systematically purged from portfolios.