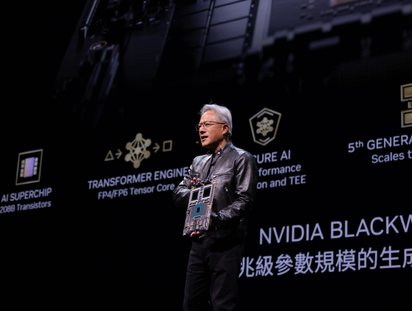
Executive Takeaways
- Record-Breaking Top Line: Nvidia posted Q4 FY2025 revenue of US$39.3 billion, marking a staggering 78% year-over-year increase and a 12% sequential bump from the previous quarter.
- The Blackwell Inflection: The newly commercialized Blackwell architecture transitioned from fabrication lines to hyperscale data centers at unprecedented velocity, generating billions in its inaugural commercial quarter.
- Consumer & Edge Expansion: Alongside enterprise AI supercomputers, Nvidia launched the GeForce RTX 50 Series graphics cards and laptops, targeting a 2x performance leap over prior-generation architectures.
- Infrastructure Scalability: Capital allocation by major cloud service providers continues unabated, underscoring high enterprise ROI despite tightening regulatory compliance and supply chain complexities.
NEW YORK & SANTA CLARA — In what financial analysts are already calling a defining chapter for the modern technology landscape, NVIDIA Corporation (NASDAQ: NVDA) has once again rewritten the playbook for corporate financial growth. Reporting its fiscal fourth-quarter earnings for the period ending January 26, 2025, the silicon titan announced a jaw-dropping revenue of $39.3 billion. The figure not only obliterates Wall Street consensus estimates but also signals that the generative AI super-cycle is transitioning from speculative infrastructure buildout to entrenched, high-yield commercial deployment.
The catalyst behind this monumental surge is the commercial debut and rapid scaling of Nvidia's next-generation Blackwell architecture. Far from suffering from the production bottlenecks or thermal management hurdles whispered about in supply chain corridors last year, Nvidia orchestrated a masterclass in manufacturing execution. By seamlessly moving massive-scale production of Blackwell AI supercomputers from foundry partners to customer data racks, the company unlocked billions of dollars in revenue within a single, fiercely compressed reporting window.
The Anatomy of a $39.3 Billion Quarter: Catalysts and Mechanics
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
To understand the sheer magnitude of Nvidia’s $39.3 billion quarter—up 78% year-on-year and 12% sequentially from the third quarter—one must examine the structural shift occurring within global enterprise IT budgets. Chief Information Officers across Fortune 500 boardrooms are no longer debating whether to integrate artificial intelligence into their operational workflows; they are aggressively pricing infrastructure scalability to secure competitive moats.
Nvidia’s Blackwell architecture has become the undisputed linchpin of this macro-shift. Designed specifically to accelerate trillion-parameter large language models (LLMs), real-time generative inference, and complex scientific simulation, Blackwell chips have effectively shortened training cycles while lowering the total cost of ownership for cloud service providers (CSPs). This enterprise ROI proposition has compelled hyperscalers—such as Microsoft Azure, Amazon Web Services, Google Cloud, and Oracle Cloud Infrastructure—to maintain aggressive capital expenditure programs, directly fueling Nvidia’s balance sheet.
However, the narrative of this quarter extends far beyond enterprise data centers. During the same reporting period, Nvidia unleashed its consumer-facing ecosystem with the rollout of the GeForce RTX 50 Series graphics cards and specialized laptops. Powered by the architectural efficiency of Blackwell derivatives, these consumer GPUs deliver up to a 2x performance improvement over the prior-generation Ada Lovelace architecture. This dual-pronged assault on both the enterprise datacenter and the consumer gaming/AI PC market ensures that Nvidia’s revenue streams remain diversified across high-margin silicon verticals.
Verified Data & Metrics Breakdown

A rigorous examination of Nvidia’s financial trajectory underscores the unprecedented velocity of its expansion. The following metrics outline the structural performance of the company during the quarter ended January 26, 2025:
| Financial / Operational Metric | Q4 FY2025 Result | Quarter-over-Quarter (QoQ) Growth | Year-over-Year (YoY) Growth |
|---|---|---|---|
| Total Quarterly Revenue | $39.3 Billion | +12% | +78% |
| Core Growth Driver | Blackwell AI Supercomputers & Next-Gen Datacenter Infrastructure | ||
| Consumer Hardware Launch | GeForce RTX 50 Series GPUs & AI Laptops (Up to 2x Performance Gain) | ||
| Fiscal Period Ending | January 26, 2025 | ||
Industry & Market Implications: Winners, Losers, and Economic Ripples
Nvidia’s blowout earnings report reverberates far beyond the company’s Santa Clara headquarters, creating distinct ripple effects across the global technology ecosystem, financial markets, and geopolitical trade routes.
The Winners: Hyperscalers, Foundry Partners, and AI Pioneers
The primary beneficiaries of Nvidia’s dominance are the Tier-1 cloud providers and specialized AI infrastructure funds that secured early allocation of Blackwell systems. Companies capable of deploying these systems immediately are realizing dramatic efficiency gains in model inference, cutting operational expenses associated with power consumption and rack space. Furthermore, foundry partners—most notably Taiwan Semiconductor Manufacturing Company (TSMC)—reap the rewards of record fabrication volumes, cementing a symbiotic industrial alliance.
The Losers: Legacy Silicon and Laggard Enterprises
Conversely, legacy enterprise hardware vendors and alternative chipmakers struggling to match Nvidia's integrated hardware-software ecosystem (CUDA) face widening competitive gaps. Enterprises slow to adopt AI infrastructure risk structural obsolescence as nimble market entrants leverage Blackwell-powered computational dominance to disrupt traditional business models.
Macroeconomic and Regulatory Pressures
Despite the celebratory mood on Wall Street, institutional investors remain vigilant regarding risk mitigation. Regulatory compliance—particularly concerning export controls on high-performance computing to restricted geopolitical zones—remains a persistent variable. Moreover, supply chain vulnerabilities, raw material costs, and power grid constraints for massive data center installations pose challenges that require sophisticated capital allocation and strategic foresight from Nvidia’s executive leadership.
Frequently Asked Questions (People Also Ask)
What was Nvidia's revenue for the fourth quarter of fiscal 2025?
Nvidia reported a record-breaking quarterly revenue of US$39.3 billion for the period ending January 26, 2025. This represents a 78% increase year-over-year and a 12% increase from the previous quarter.
What role did the Blackwell architecture play in Nvidia's earnings?
The Blackwell architecture was the primary growth engine for the quarter. Nvidia successfully scaled mass production of Blackwell AI supercomputers, enabling the company to generate billions of dollars in sales from the platform during its very first commercial quarter.
What consumer hardware did Nvidia announce alongside its enterprise products?
Alongside its enterprise data center offerings, Nvidia introduced the GeForce RTX 50 Series graphics cards and AI-powered laptops, which utilize the Blackwell architecture to deliver up to a 2x performance improvement over previous-generation hardware.
How is Nvidia maintaining its market dominance against rising competition?
Nvidia maintains its competitive moat through its deeply entrenched CUDA software ecosystem, rapid hardware innovation cycles, and deep collaborative partnerships with global cloud service providers and original equipment manufacturers (OEMs).
Future Outlook: Strategic Milestones to Watch
As Nvidia looks toward the remainder of fiscal 2026, the critical question facing equity markets is sustainability. Can a company generating nearly $40 billion a quarter continue to compound at rates that justify its lofty valuation multiples?
Executive leadership will need to navigate several pivotal milestones in the coming quarters. First, the ongoing deployment velocity of Blackwell follow-on architectures and liquid-cooling data center integrations will dictate whether hardware margins remain resilient. Second, software monetization—specifically enterprise subscriptions for AI foundry services and autonomous driving platforms—will serve as a crucial secondary revenue pillar. Finally, navigating evolving international trade policies and maintaining supply chain elasticity will remain top priorities for safeguarding market liquidity and investor confidence.
For now, Nvidia has silenced the skeptics. By successfully executing the Blackwell transition while simultaneously satisfying surging consumer and enterprise demand, the company has solidified its status not merely as a semiconductor manufacturer, but as the foundational architect of the global digital economy.