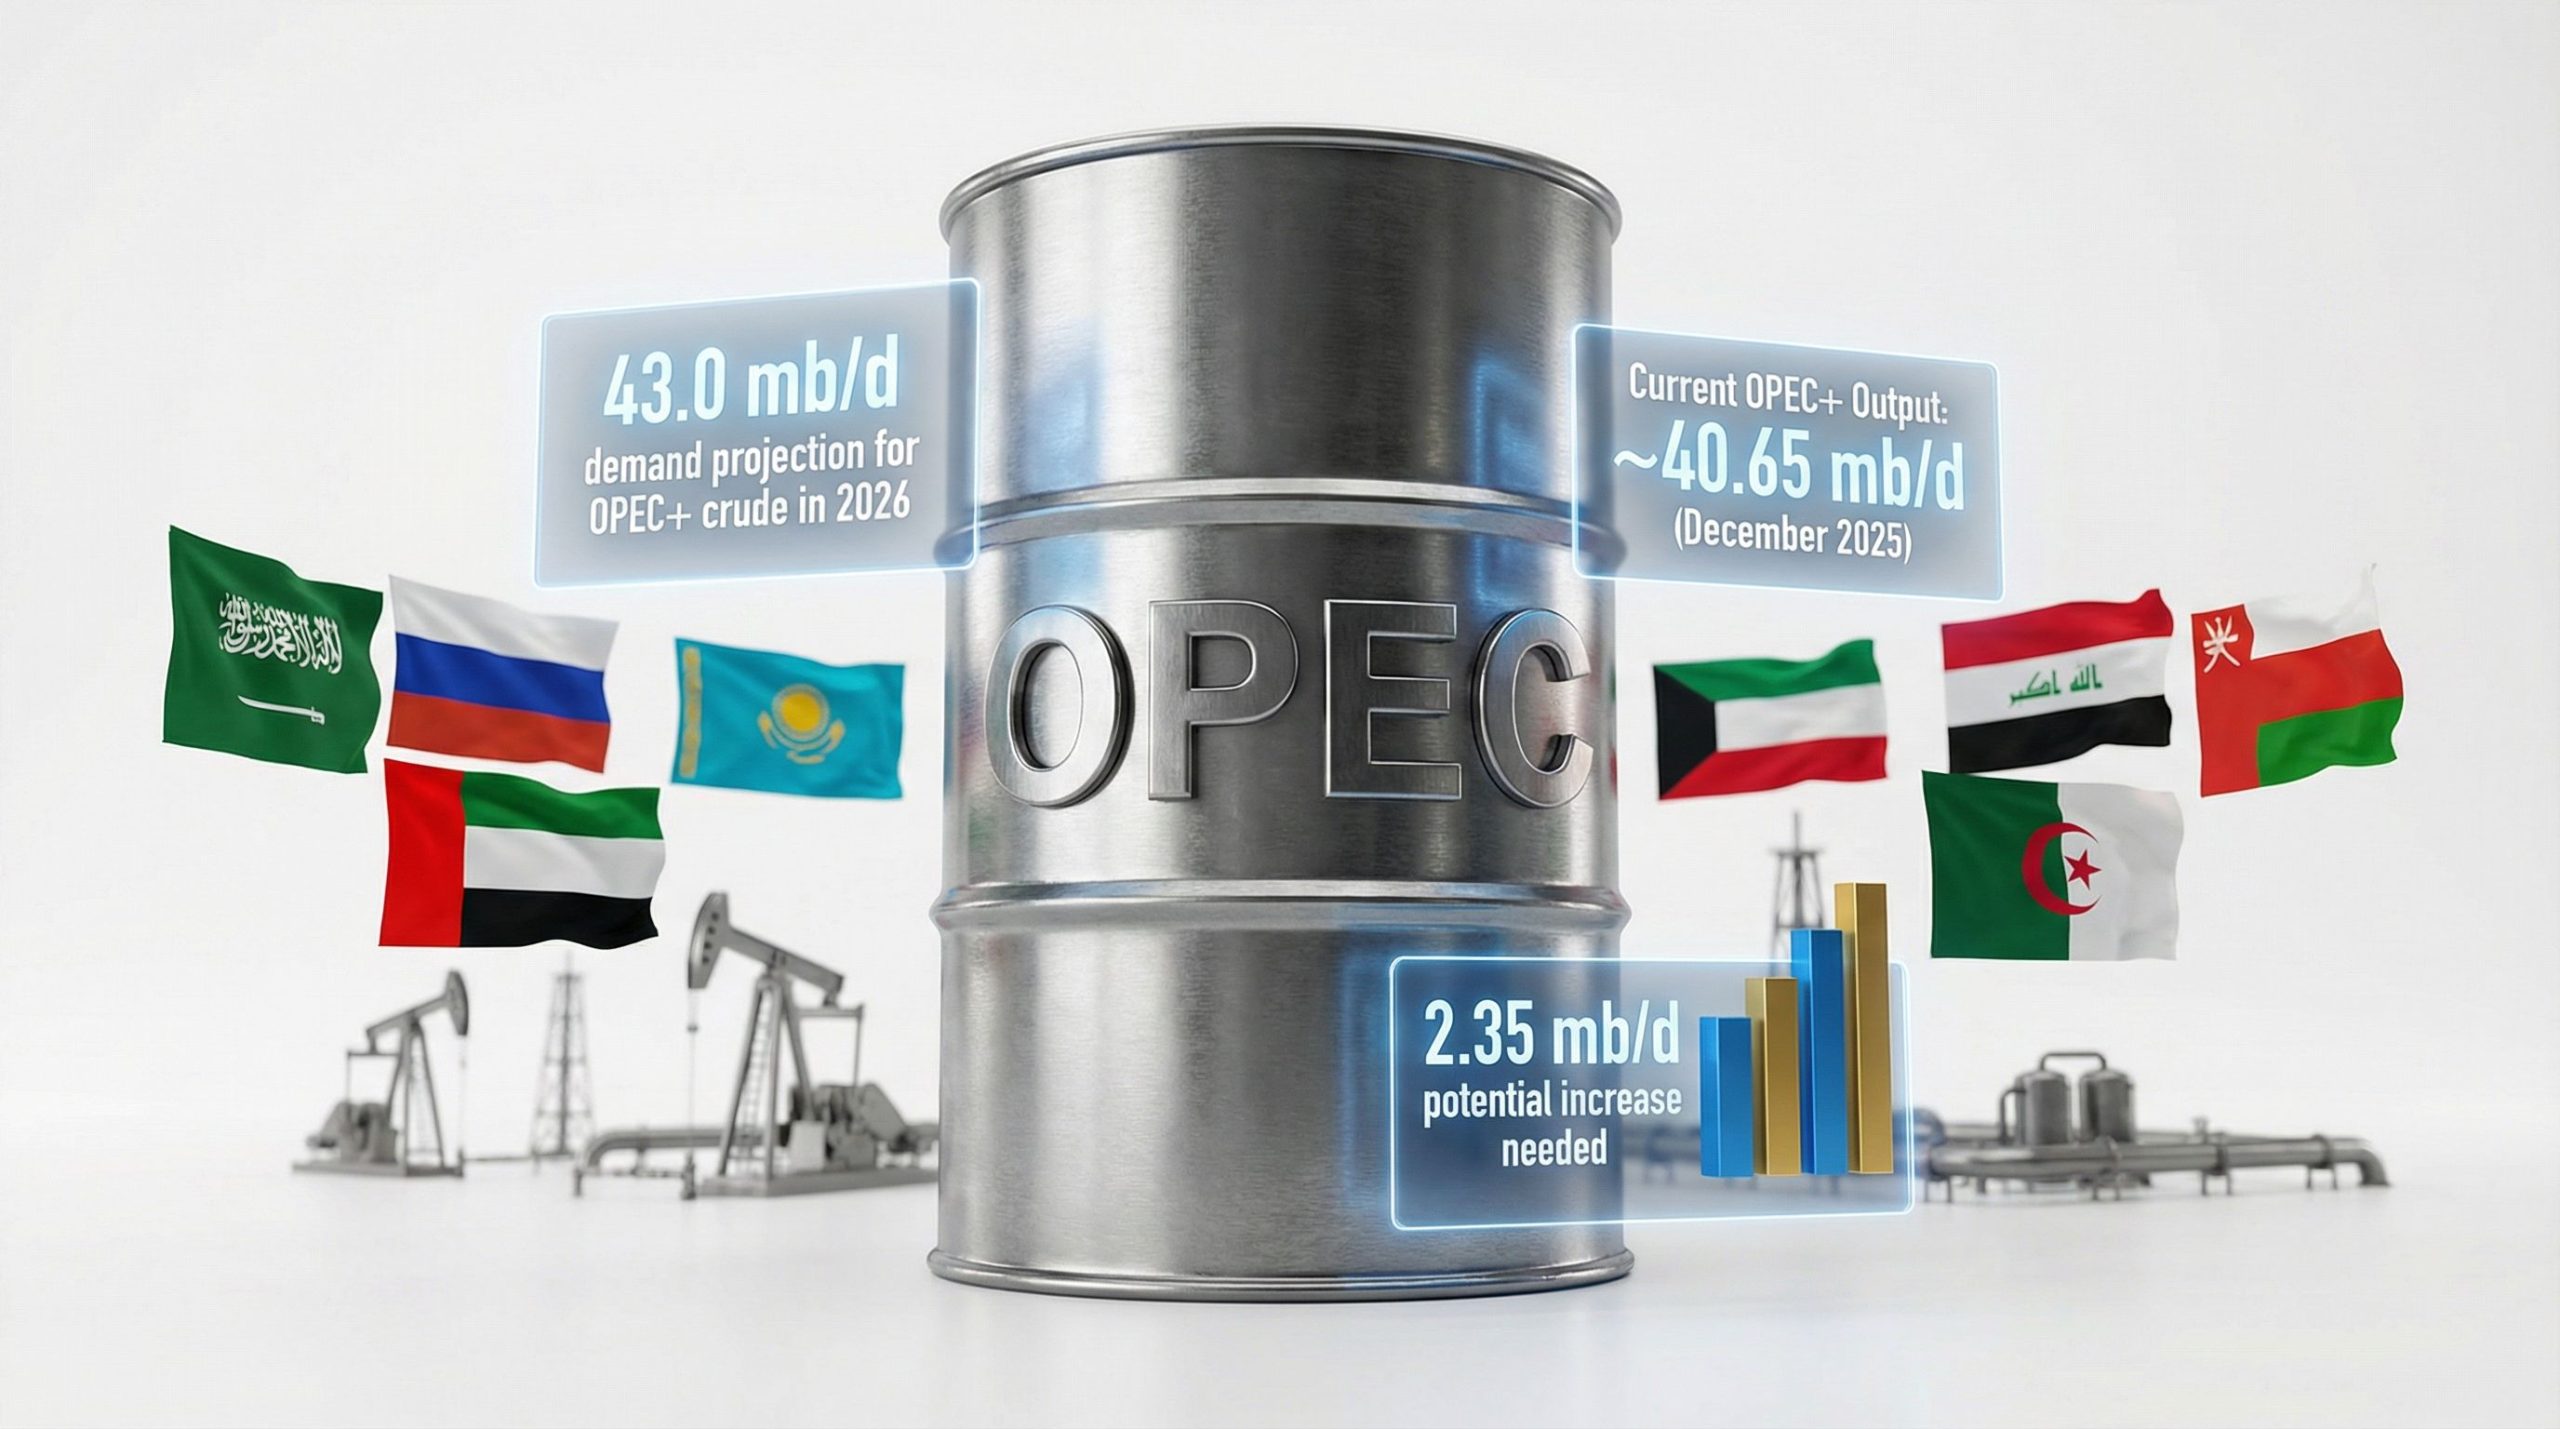
VIENNA / LONDON / NEW YORK — In a high-stakes display of cartel cohesion, OPEC+ ministers have formally agreed to keep December oil output targets steady, sidestepping immediate market panic while deferring a far more contentious structural reckoning. Behind closed doors in Vienna and across encrypted communication channels linking Riyadh, Moscow, and Abu Dhabi, energy ministers and sovereign wealth strategists are acutely aware that today's steady hand is merely a temporary reprieve. The real battleground lies just over the horizon, with the alliance bracing for a brutal, high-stakes structural renegotiation over baseline quotas and market share allocation slated for 2027.
For institutional investors, multinational energy conglomerates, and sovereign risk analysts, this policy continuity masks deep underlying anxieties. The decision to maintain current production curbs through the final quarter preserves near-term price stability, but it severely complicates capital allocation strategies and corporate valuation multiples for global exploration and production (E&P) firms. As enterprise ROI expectations shift in response to volatile macroeconomic indicators and fluctuating energy demand, the cartel's ability to orchestrate orderly risk mitigation is facing unprecedented stress tests from non-OPEC supply surges and structural shifts in global cloud compute architecture powering next-generation smart-grid optimization.
Executive Takeaways
- Policy Continuity: OPEC+ has officially maintained its December production targets, neutralizing immediate fears of a sudden supply glut heading into the winter heating season.
- The 2027 Horizon: The true catalyst for market volatility remains the upcoming 2027 structural review, where lagging members are expected to fiercely contest baseline production quotas.
- Capital Allocation Pressures: Upstream operators face complex risk mitigation challenges as deferred barrels constrain free cash flow generation and complicate long-term infrastructure scalability.
- Market Liquidity & Pricing: Brent and WTI benchmarks remain range-bound, but options markets are aggressively pricing in tail risks tied to potential quota compliance failures and shifting macroeconomic regulatory compliance mandates.
The Anatomy of a Stalemate: Why December Targets Matter
Test Our Free AI & Tech Utilities Suite
Calculate LLM API token costs, analyze article dwell-time, or simulate tech DCA returns.
The decision to freeze output targets for December was far from a foregone conclusion. Weeks of intense backchannel diplomacy preceded the ministerial gathering, driven by diverging internal economic imperatives among key alliance members. Saudi Arabia, bearing the brunt of the voluntary production cuts required to defend price floors above the $70–$80 per barrel threshold, has grown increasingly intolerant of persistent overproduction by select African and Eurasian member states.
Yet, pushing for aggressive volume restoration during a period of fragile global market liquidity could have triggered a catastrophic price correction. Energy economists note that Brent crude benchmarks have hovered within a tightening trading band, reflecting a delicate equilibrium between sluggish industrial demand in continental Europe and resilient, albeit slowing, consumption in North America and Asia.
By keeping the taps throttled through December, OPEC+ leadership has chosen to prioritize balance sheet preservation over aggressive market-share reclamation—at least for the moment. However, this strategy carries severe opportunity costs. Capital expenditure (CapEx) programs across major state-owned oil companies are being artificially constrained, leading to deferred maintenance and delayed deployment of advanced extraction technologies. For multinational service providers, this translates into stagnant project pipelines and a prolonged plateau in high-margin engineering contracts.
The 2027 Precipice: Quotas, Baselines, and Internal Friction

While December is secure, the structural architecture of OPEC+ is hurtling toward a major stress test in 2027. The core controversy centers on the contentious auditing of production baselines—the authorized maximum capacity numbers from which percentage cuts are calculated. Several nations, most notably the United Arab Emirates, have successfully lobbied for upward revisions to their baselines to reflect massive capital investments in upstream infrastructure expansion completed over recent years.
As these expanded capacities come fully online, keeping a lid on actual production will become mathematically and politically untenable for ambitious member states eager to monetize their subsurface assets. The 2027 framework will require a comprehensive recalibration of quotas that reconciles Riyadh’s desire for price defense with Abu Dhabi, Iraq, and Kazakhstan's demands for volume expansion. Failure to broker a sustainable consensus risks triggering a disruptive quota-busting free-for-all reminiscent of historical market share wars.
Macroeconomic Ripple Effects and Corporate Strategy
The reverberations of the OPEC+ strategy extend far beyond traditional energy markets, directly impacting global supply chains, industrial input costs, and corporate valuation multiples. Downstream sectors—including petrochemicals, aviation, and heavy manufacturing—must navigate persistent energy price volatility without the benefit of clear long-term hedging visibility.
| Strategic Metric | Current Status (December Targets) | Projected Outlook (2027 Framework) |
|---|---|---|
| Aggregate Production Cuts | Approximately 5.86 million bpd (inclusive of voluntary curbs) | Subject to systematic phase-out or baseline re-indexing |
| Compliance Monitoring | Independent audit panels tracking monthly overproduction | Expanded real-time satellite and algorithmic verification |
| Upstream CapEx Focus | Defensive maintenance, emissions reduction, efficiency | Capacity expansion, digital twin integration, automation |
| Market Volatility Index | Moderate, range-bound between $70–$85/bbl (Brent) | Elevated tail-risk pricing for potential quota collapse |
Concurrently, integrated energy majors are accelerating investments in digital transformation and cloud-compute architecture to optimize reservoir management. By leveraging predictive analytics and machine learning algorithms, producers are attempting to squeeze maximum enterprise ROI from mature fields while navigating stringent environmental and regulatory compliance mandates across Western jurisdictions.
Frequently Asked Questions (People Also Ask)
Why did OPEC+ decide to keep December oil output targets steady?
OPEC+ opted to maintain its current production targets through December to prevent seasonal inventory imbalances and protect price stability amid mixed global economic data. With demand growth in major industrial economies showing signs of softening, cartel leaders prioritized defending price floors over aggressively increasing volume.
What makes the upcoming 2027 OPEC+ policy pivot so critical for global markets?
The 2027 outlook represents a major structural inflection point because multiple member states—having invested heavily in expanding their upstream production capacity—will demand higher baseline quotas. Reconciling these competing volume ambitions with the global market's actual demand absorption capacity will test the alliance's unity and could trigger significant price volatility if consensus fails.
How do production quotas impact corporate capital allocation and valuation multiples?
Strict production curbs artificially cap top-line revenue growth for upstream operators, forcing management teams to focus intensely on operational efficiency, cost containment, and disciplined capital allocation. This dynamic directly influences equity valuation multiples, as institutional investors weigh restricted cash flow generation against the long-term asset value of vast, untapped reserves.
What role do independent audits and compliance mechanisms play in OPEC+ decisions?
Independent secondary sources and real-time verification panels monitor member compliance to ensure that no single nation cheats on its assigned quota. Strict enforcement is vital for maintaining cartel credibility; widespread non-compliance historically leads to oversupply, inventory accumulation, and severe price downturns.
Future Outlook: Navigating the Road to 2027
As the global energy landscape undergoes a profound, multi-decade transition, the decisions forged in Vienna carry immense weight. The immediate relief of steady December targets provides a temporary safety net for financial markets, but executive boards and sovereign planners must keep their eyes fixed on the longer-term horizon.
Over the next 12 to 36 months, market participants should monitor several critical milestones: quarterly compliance reports from key overproducing states, shifts in non-OPEC supply growth (particularly from American shale and offshore Latin American basins), and early diplomatic signals regarding the 2027 baseline negotiations. Ultimately, the ability of OPEC+ to manage its internal contradictions will dictate whether the cartel can successfully navigate the structural shifts of the late 2020s or succumb to the centrifugal forces of divergent national interests.