Wall Street delivered a defining performance on Thursday as institutional capital flooded into mega-cap technology equities, propelling the Dow Jones Industrial Average across the psychological 50,000-point threshold for the first time in financial history. The rally was characterized by massive institutional liquidity deployments into enterprise compute, cloud infrastructure, and semiconductor equipment leaders, even as trading desks globally shifted their strategic models toward high-stakes bilateral trade and technology negotiations commencing in Beijing.
Executive Takeaways
- Historic Threshold Crossed: The Dow Jones Industrial Average added 370.26 points, or 0.75%, to finish at an unprecedented 50,063.46, anchored by resilient balance sheets across enterprise tech and industrials.
- Broad Market Momentum: The S&P 500 and the Nasdaq Composite posted aggressive gains of 1.08% and 1.42% respectively, fueled by sovereign-scale cloud compute expenditure announcements and solid margin expansion across hyperscalers.
- Beijing Diplomatic Pivot: A high-level U.S. delegation arrived in Beijing for multi-day negotiations focusing on sub-2-nanometer semiconductor export controls, critical mineral supply-chain access (gallium, germanium, and refined lithium), and cross-border corporate compliance frameworks.
- Valuation Multiples Expand: Benchmark 10-year U.S. Treasury yields compressed by 4 basis points to 4.18%, easing cost-of-capital concerns and triggering quantitative re-allocation from cash reserves into high-beta equities.
The Anatomy of the Tape: Dow 50,000 and the Silicon Architecture Engine
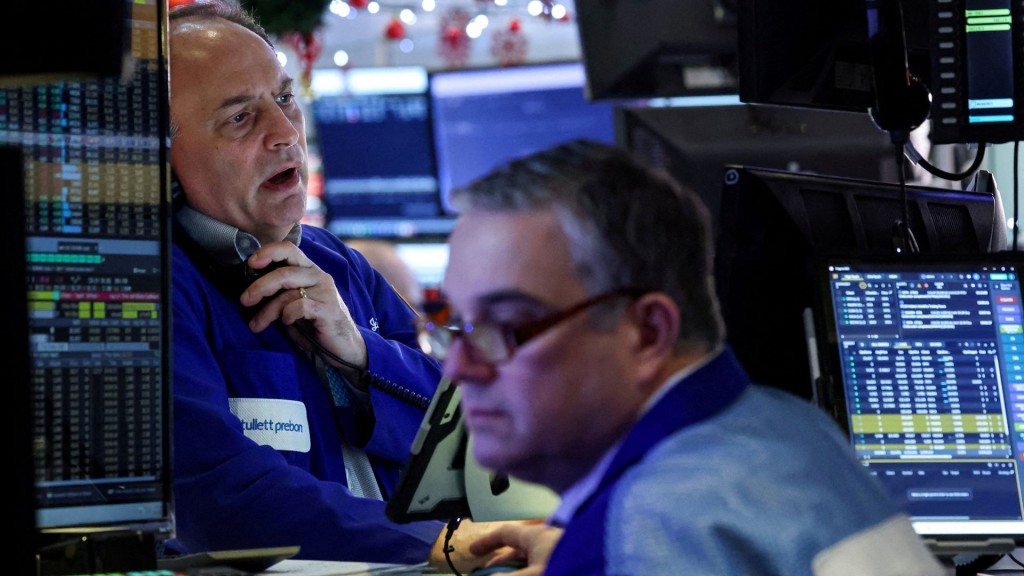
The closing bell on May 14, 2026, cemented a dramatic reallocation of institutional capital. The Dow Jones Industrial Average climbed 370.26 points (+0.75%) to settle at 50,063.46. Meanwhile, the S&P 500 advanced 68.90 points (+1.08%) to 6,432.10, and the tech-heavy Nasdaq Composite led trading desks higher, surging 298.15 points (+1.42%) to 21,245.30. Institutional volume across the New York Stock Exchange and Nasdaq exceeded 12.8 billion shares, roughly 14% above the 20-day trailing moving average.
The catalytic impulse behind the equity surge was not speculative retail volume, but an assertive re-rating of enterprise compute architecture. Following mid-quarter capital expenditure updates from global cloud hyperscalers, Wall Street revised forward earnings estimates upward. Corporate enterprises are demonstrating verifiable enterprise return on investment (ROI) from proprietary artificial intelligence deployments, moving beyond initial proof-of-concept spending into recurring balance-sheet monetization. Enterprise software vendors and advanced packaging foundries recorded intraday gains between 2.8% and 4.6%, directly pulling the capitalization-weighted indexes toward record territory.
Simultaneously, fixed-income yields retreated. The 10-year Treasury yield softened to 4.18%, down from 4.22% late Wednesday, following benign producer price figures and stable wholesale margin metrics. This narrowing of real risk-free yields provided cover for asset managers to bid up forward price-to-earnings (P/E) multiples on cash-generative technology monoliths, brushing aside warnings of overextended chart technicals.
The Geopolitical Chessboard: The Beijing Conclave
While equity traders in New York were bidding up mega-cap tech, risk officers and macro strategists turned their undivided attention to the Chinese capital. A high-ranking U.S. diplomatic and economic delegation—comprising senior officials from the U.S. Department of the Treasury, the Department of Commerce, and the Office of the U.S. Trade Representative—formally convened with their counterparts in Beijing for high-stakes bilateral talks.
At the center of these discussions is the global supply chain architecture for advanced hardware and raw materials. For the past twenty-four months, both superpowers have executed carefully choreographed economic measures: the United States tightening unilateral restrictions on the export of advanced lithography systems, electronic design automation (EDA) software, and AI acceleration silicon; and Beijing countering with strict licensing regimes on critical mineral refinement, targeting rare earth elements essential for defense electronics, high-voltage electric vehicle drivetrains, and telecommunications hardware.
Diplomatic sources indicate that the Beijing talks are focused on four core pillars:
- Export Control Boundary Definitions: Defining transparent technical thresholds for dual-use technologies, giving global fabless semiconductor design firms operational predictability across the Asia-Pacific region.
- Critical Minerals Quota Stability: Securing long-term contractual and export quota predictability for high-purity gallium, germanium, and synthetic graphite, directly insulating Western industrial supply chains from sudden output stoppages.
- Cross-Border Cloud Data Compliance: Establishing regulatory mechanisms for enterprise multi-nationals operating distributed server farms within Chinese territorial waters, addressing cybersecurity audit mandates without compromising Western IP ownership.
- Capital Mobility & Portfolio Inflows: Calibrating the regulatory scope for global private equity and venture capital vehicles seeking to unwind or redeploy legacy non-sensitive investments in regional technology ecosystems.
The market's bullish close reflects an institutional consensus that neither superpower currently possesses the domestic appetite for an escalating trade disruption. With China balancing property-sector restructuring alongside industrial modernization, and the U.S. navigating election-cycle economic stewardship, derivatives markets are pricing in a constructive baseline: a calibrated status quo marked by pragmatic carve-outs rather than punitive tariff expansions.
Market Metrics & Valuation Overview
The divergence between defensive asset classes and capital-expenditure-heavy tech sectors highlights a distinct risk-on inflection point. The table below delineates the closing levels, trading variations, and valuation multiples across critical asset classes as of the May 14, 2026, market close.
| Index / Asset Class | Closing Level | Daily Change (Net / %) | Forward P/E Multiple | Primary Sector Driver |
|---|---|---|---|---|
| Dow Jones Industrial Average (.DJI) | 50,063.46 | +370.26 (+0.75%) | 21.4x | Enterprise Tech, Industrial Automation |
| S&P 500 Index (.SPX) | 6,432.10 | +68.90 (+1.08%) | 23.8x | Hyperscale Cloud, Semiconductor Foundry |
| Nasdaq Composite (.IXIC) | 21,245.30 | +298.15 (+1.42%) | 29.2x | Semiconductor IP, Scaled Software Platforms |
| Philadelphia Semiconductor (SOX) | 6,812.40 | +142.30 (+2.13%) | 31.5x | EUV Lithography, Memory Architecture |
| U.S. 10-Year Treasury Yield | 4.18% | -4.0 bps (-0.95%) | N/A | Wholesale Margin & PPI Deflation Signals |
| CBOE Volatility Index (VIX) | 12.45 | -0.85 (-6.39%) | N/A | Derivatives Hedging Demand Softening |
Industry & Strategic Implications: Winners, Losers, and Capital Allocation
The structural expansion of the broader equity market beyond traditional concentration barriers signals systemic changes for corporate treasury desks and institutional portfolios alike.
1. Who Wins: Silicon Architects and Critical Infrastructure Providers
The clear immediate beneficiaries are enterprise semiconductor firms and hyperscale infrastructure vendors. The convergence of Dow 50,000 and record multi-cloud deployments underscores that high-performance compute has decoupled from typical macroeconomic cyclicality. Advanced packaging providers, high-bandwidth memory (HBM) developers, and specialized data-center cooling infrastructure manufacturers are capturing record operating margins. Concurrently, major Wall Street prime brokers report that asset managers are actively unwinding short positions against Asia-Pacific supply-chain logistics plays, anticipating clear trade lane demarcations from the Beijing summit.
2. Who Faces Margin Compression: Capital-Constrained Legacy Operators
Conversely, mid-market enterprises burdened with variable-rate debt obligations are failing to match the performance of index heavyweights. While benchmark 10-year yields have stabilized, corporate debt refinancing costs remain structurally elevated relative to the zero-rate regime of the previous decade. Companies unable to demonstrate tangible enterprise ROI from technology licensing are experiencing multiple contraction. In particular, legacy consumer-goods producers are confronting margin compression as wholesale inventory costs remain sticky while consumer discretionary spending continues to bifurcate along income brackets.
3. Institutional Balance-Sheet Strategies
The prevailing portfolio construction strategy among top-tier sovereign wealth funds and corporate treasuries centers on balance-sheet liquidity and high interest-coverage ratios. Institutional asset allocators are deploying cash into large-cap tech equities that operate effectively as high-yield synthetic credit proxies—holding multi-billion-dollar net-cash balances, commanding aggressive pricing power, and consistently funding substantial equity repurchase programs to support earnings-per-share (EPS) trajectories.
Frequently Asked Questions (People Also Ask)
What drove the Dow Jones Industrial Average past the 50,000 milestone?
The Dow’s historic ascent to 50,063.46 was primarily fueled by an aggressive rerating of institutional enterprise technology valuations, coupled with durable balance-sheet performance among heavy industrial components. Rather than broad-based speculative fervor, the move was catalyzed by upward earnings revisions for cloud infrastructure providers, stabilizing long-term debt yields at 4.18%, and easing inflationary pressures in upstream supply chains.
Why are the May 2026 U.S.-China talks in Beijing critical for equity investors?
The bilateral negotiations in Beijing directly address the baseline operating margins and supply-chain access for the global technology ecosystem. Specifically, the talks seek to establish firm operational guidelines regarding advanced semiconductor export limitations, cybersecurity compliance mandates for multi-national corporations, and the stable delivery of essential refined minerals, including gallium and germanium. Constructive outcomes mitigate the probability of sudden, retaliatory trade measures that disrupt multinational corporate earnings.
How do rising tech capital expenditures affect long-term corporate valuation multiples?
Enterprise technology capital expenditures have increasingly shifted toward long-life infrastructure assets, such as accelerated compute clusters and high-efficiency power distribution networks. While this elevated CapEx temporarily increases cash outflow, it concurrently expands institutional valuation multiples by establishing deep, defensible operational moats and unlocking high-margin software revenues. When firms consistently convert this infrastructure into cash-generative enterprise ROI, equity analysts justify higher enterprise-value-to-EBITDA (EV/EBITDA) and forward P/E multiples.
What primary downside risks could destabilize the current market rally?
Despite the historic closing levels, market participants face three material risks: an unexpected breakdown in Beijing diplomatic talks leading to renewed export bans; structural persistence in core services inflation that forces the Federal Reserve to pause liquidity accommodation; and margin degradation if enterprise adoption of advanced technology fails to yield the productivity gains currently modeled into high forward-earnings multiples.
Future Outlook: Strategic Milestones to Watch
Over the next 72 to 96 hours, global financial desks will focus squarely on the joint communique expected at the conclusion of the Beijing economic summit. A formal, bilateral framework concerning export predictability will likely compress emerging-market sovereign risk spreads and provide fresh runway for cross-border mergers and acquisitions, which have hovered near multi-year lows.
Domestically, the trajectory of this equity rally faces an immediate analytical checkpoint with the forthcoming release of the Federal Reserve’s latest policy meeting minutes and benchmark Personal Consumption Expenditures (PCE) deflator figures. Should core PCE prints confirm the moderating trajectory exhibited by wholesale PPI indicators, the structural bid beneath equities is expected to broaden beyond tech champions into cyclically sensitive industrials, transportation networks, and commercial real estate debt securities.
For Chief Investment Officers and institutional treasury directors, the crossing of Dow 50,000 is less a destination than a re-anchoring of baseline market valuations. The macro operational environment demands disciplined capital allocation: hedging sovereign geopolitical tail-risks while maintaining exposure to scalable, cash-flow-accretive balance sheets capable of compounding earnings in an increasingly bifurcated global economic order.